RSS

After an Offer Is Accepted: Conditions and Closing in Nova Scotia

An accepted offer starts the next stage of the sale. During the buyer’s condition period, the buyer may arrange inspections and complete other steps set out in the Agreement of Purchase and Sale.

Once the buyer confirms their conditions and the sale is firm, we can focus on any agreed work, prepare for the move and get ready for closing. I’ll help keep the dates and next steps organized.

Buyer inspections happen during the condition period

The buyer typically arranges inspections during the condition period. Depending on the property and the terms of the offer, these may include a home inspection, a well inspection or water test, and a septic inspection.

If the property has a well or septic system, you are responsible for exposing—digging up—and marking the locations so the inspector can find and access them. We’ll coordinate the timing and access with the buyer’s representative.

The offer may include a water and septic schedule or other specific terms. I’ll review those with you so we know what the agreement requires and when. The Nova Scotia Real Estate Commission’s overview of real estate forms explains the purpose of the Agreement of Purchase and Sale and related schedules.


Complete agreed work after conditions are confirmed

If the buyer’s inspections lead to repairs or updates that become part of the sale agreement, arrange that work after the buyer confirms their conditions and before closing—or by another deadline agreed to in writing.

If the property has a septic system, it will typically need to be pumped before closing. We’ll check the agreement for the required timing and any documentation the buyer is to receive. Keep invoices or other records for agreed repairs and septic work so they can be provided as required.

If there is a change to the property or an agreed item cannot be completed on time, tell me promptly so we can address it with the buyer’s representative.

Home maintenance professional tightening a kitchen cabinet handle.

Arrange insurance and electricity before closing

Once the buyer’s conditions are confirmed, contact your insurance provider. Tell them the expected closing date and ask when your coverage should end. Keep coverage in place until the sale has closed and possession has transferred, and confirm how an early move-out could affect your policy.

If Nova Scotia Power supplies electricity to the property, arrange to stop your service for the appropriate date before closing. Nova Scotia Power asks for 10 days’ notice, and moving out does not automatically close your account. Contact them as soon as the sale is firm; if the property is supplied by a municipal utility, contact that provider instead. See Nova Scotia Power’s instructions for starting, stopping or moving service.

Keep essential services available for any remaining access or work required by the agreement. In colder weather, check before changing the heat settings or shutting off service.


Prepare for the buyer’s pre-closing viewing

The buyer may have a final pre-closing viewing under the terms of the agreement. Sometimes this is called a pre-closing inspection, but it is not a second home inspection. The Nova Scotia Real Estate Commission describes it as a final look to confirm that the property’s condition has not changed since the buyer agreed to purchase it. See the Commission’s explanation of the final pre-closing viewing.

Before the viewing, complete agreed work, remove your belongings and garbage, and leave items included in the sale. I’ll coordinate access with the buyer’s representative.

If you notice new damage or another change before closing, tell me right away so we can address it promptly.

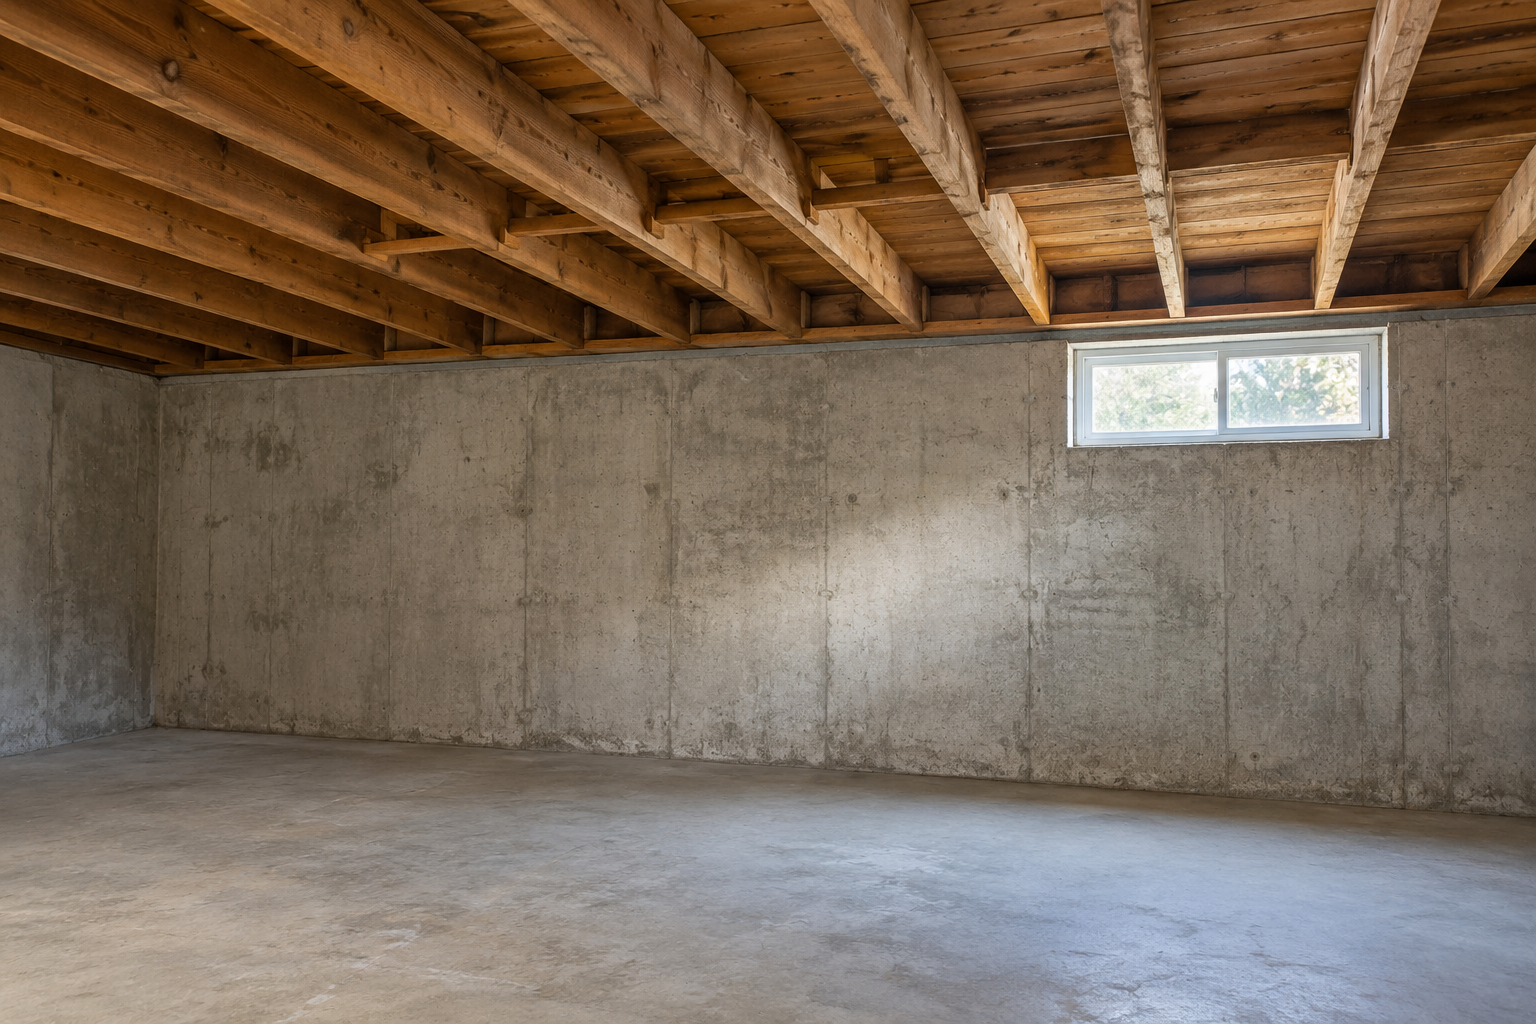
Empty home interior with clear floors and walkways, ready for inspection after the sellers have moved out.

Closing day and handing over the home

Your lawyer will guide you through the legal and financial steps and let you know what documents or information they need. Respond promptly to their requests, and ask them directly about the timing of the final accounting and sale proceeds.

Follow the agreement’s requirements for moving out and possession. Gather the keys, garage remotes and other access items for handover. I’ll confirm when the sale has closed and coordinate the handoff according to the agreement.

For the earlier offer-review stage, read Reviewing an Offer on Your Home in Nova Scotia. For the full selling process, visit my Selling Your Home in Nova Scotia guide.

I’ll help you keep track of what needs to happen between the accepted offer and closing day.

Read

Reviewing an Offer on Your Home in Nova Scotia

Receiving an offer is an important step, but the price is only one part of the decision. The conditions, deposit, closing date, included items and deadlines can all affect how the offer works for you.

I’ll review the written terms with you, explain how the pieces fit together and help you communicate your decision. We can compare an offer with your priorities and the plan we made for the sale.

Look at the whole offer

A strong offer is the one whose full terms fit your situation—not necessarily the one with the highest price.

When we review an offer, I’ll help you look at:

  • Price: How does it compare with your expectations and the market information we discussed?

  • Conditions: Has the buyer included conditions, such as financing, an inspection, or the sale of their current property? What are the deadlines?

  • Deposit: What amount is offered, when is it due, and what does the agreement say about it?

  • Closing date: Does the proposed date give you enough time to move and make your next arrangements?

  • Included or excluded items: Are fixtures, appliances or other items described clearly?

  • Other terms and deadlines: Are there requests or dates that affect your plans?

The written agreement matters. If something is unclear or an issue needs legal interpretation, I’ll help identify the question and involve your lawyer where appropriate.


Understand the conditions and timing

An offer may include conditions that give the buyer time to complete specific steps. The agreement should identify what the condition is and the deadline that applies. The wording and required notices matter, so we’ll read the actual terms rather than rely on assumptions about what a condition means.

A conditional offer is not the same as a completed sale with every step finished. We’ll keep track of the dates and required communication while the buyer works through the conditions. If a deadline or request raises a concern, we can discuss the available responses promptly.

Blank offer papers, a pen and a phone on a table during a home-sale discussion.

Decide whether to accept, reject or negotiate

You can accept an offer as written, reject it, or respond with different terms. A counteroffer may change the price, dates, included items or other terms. The buyer then decides whether to accept, reject or respond with another proposal.

Before deciding, we’ll consider what matters most to you. You might prefer a different closing date, clearer wording about an included item, or a change to another term. Negotiation should focus on the specific points you want addressed and the trade-offs involved.

The Nova Scotia Real Estate Commission explains the standard purchase and sale and counteroffer forms in its overview of Nova Scotia real estate forms.


After an offer is accepted

Once an offer is accepted, the Agreement of Purchase and Sale sets out the terms both parties must follow. If conditions remain, we’ll continue tracking the applicable deadlines and steps. I’ll keep you updated as the transaction moves forward and help coordinate communication with the buyer’s representative.

The offer-review stage follows the work that went into setting a price and bringing the home to market. You can revisit How to Price Your Home in the Annapolis Valley and From Pricing to Listing Day: How Your Nova Scotia Home Goes to Market.

When it’s time to sell, I’ll help you understand the offer in front of you, weigh the terms against your plans and decide how you want to respond. Visit my Selling Your Home in Nova Scotia guide to see the steps involved.

Read

From Pricing to Listing Day: How Your Nova Scotia Home Goes to Market

Putting a home on the market involves more than choosing an asking price and uploading a few photos. Before launch, the property details, presentation, timing and marketing plan all need to come together.

The process should fit the home and your plans. A property in town, an older home, an acreage and a waterfront property may each need a different approach to photography, information and marketing.


When Does Launch Planning Begin?

Launch planning starts before the listing appears online. We’ll discuss your timing, review the property and current competition, and decide what needs to be ready before the listing date.

That includes agreeing on a pricing strategy. My article How to Price Your Home in the Annapolis Valley explains how recent sales, competing properties and buyer response help inform that decision.

The timing also needs to work for you. We’ll discuss when you’d like the home to be available for showings, any scheduling limits and what needs to happen before photography.


Confirm the Details Before the Listing Is Written

A listing should describe the property clearly and accurately. Before launch, I’ll confirm the details that buyers are likely to look for, such as the home’s layout, features, services, heating, land and included items.

If there are property plans, service records, renovation details or other information that may help explain the home, we can review what you have. My article What to Prepare Before Listing covers records and property details that may be useful, depending on the home.

We’ll also clarify anything that could otherwise be easy to assume, such as what land or equipment is included and whether any items are rented or leased.

Homeowner checking a wall-mounted heat pump and recording a property detail before listing.

Prepare the Home for Photography

The goal of listing photography is to show the home accurately and help buyers understand the rooms, layout and important features. Preparation may involve tidying, cleaning, opening curtains, turning on appropriate lights and moving items that block a clear view.

Not every room needs to look staged, and preparation doesn’t automatically mean taking on a renovation. We can decide what is worth doing based on the home, its condition and your timing.

For more practical preparation ideas, read Preparing Your Home for Sale in Nova Scotia.


Choose Marketing That Fits the Property

Good listing information and photography are the foundation. Depending on the home, I may also recommend video, a virtual tour or drone imagery to help buyers understand the layout, land or surroundings.

Your listing is distributed through MLS® and major real estate websites. Social media and open houses may also be part of the plan when they suit the property and likely audience. Each tool has a purpose; the aim is to present the home clearly to the buyers who may be considering it.

REALTOR® photographing a wood staircase inside a home for its listing.

What Happens on Listing Day?

Before the listing goes live, I’ll check the details and media that are ready for publication. Once launched, buyers can view the listing online and contact their REALTOR® to arrange a showing.

We’ll make sure the showing instructions are clear, including any access details or practical considerations for the property. If your schedule, pets or other circumstances affect access, we’ll plan around them.


Make Showings Practical

Showings are a chance for buyers to experience the home in person after seeing it online. A simple routine can make it easier to keep the property presentable without having to reset everything each time.

Before a showing, put away personal documents and valuables, clear walkways, manage pets safely and leave access to the rooms and features buyers may want to see. If the property includes an outbuilding, gate or particular access route, we’ll make sure the instructions are understood.


Review the Early Response Together

After launch, we can review activity such as online attention, showing requests and feedback. These signals can help us understand whether the listing is reaching buyers and how they’re responding to the property and its price.

One comment or a quiet day doesn’t necessarily mean a change is needed. It’s more useful to look at patterns alongside current competition and any new sales.

If the response suggests we should revisit the plan, we can discuss the evidence and your priorities before deciding what to do.

REALTOR® and homeowner discussing showing feedback at a kitchen table.

The Plan Should Fit Your Home

No single marketing plan works for every property. The right mix depends on the home, its features, your timing and the buyers who may be interested in it.

My Selling Your Home in Nova Scotia guide covers preparation, pricing, marketing, offers, conditions and closing. If you’re considering a sale, a home evaluation gives us a chance to discuss your property and what a realistic launch plan could involve.

I’m always here to help.

Read

How to Price Your Home in the Annapolis Valley

Choosing an asking price is one of the most important decisions when preparing to sell. It can influence which buyers find your home, how they compare it with other properties and the conversations that follow once it is on the market.

There isn’t one formula that sets the right price for every Annapolis Valley home. A useful pricing strategy considers the property, recent sales, current competition and what buyers are responding to in the market.


What Shapes a Home’s Market Position?

A home’s market position reflects more than its square footage or the number of bedrooms. Buyers may also consider its location, condition, layout, features, lot, services and the work they expect to take on after moving in.

Two homes with similar sizes can appeal to different buyers and occupy different positions in the market. A home in town, an older house, a newer property and a home with acreage may each need a different comparison set.

That’s why pricing starts with understanding the specific property—not relying on a broad average or a single recent sale.

Annapolis Valley home and surrounding property

How a Comparative Market Analysis Helps

A Comparative Market Analysis, or CMA, is one way to study how your property fits into its current market. It considers relevant recent sales and homes currently competing for buyers, along with differences in location, condition, features and property type.

No two properties are identical. A CMA is not an appraisal or a guarantee of what a buyer will offer. It is a reasoned estimate that helps inform the asking-price decision.

The most useful comparisons help explain why a similar property may have sold for more or less. The sale price matters, but so do the property’s features, timing and the choices available to buyers at the time.

REALTOR® reviewing comparable home sales

Price Also Affects How Buyers Find Your Home

Buyers often search within selected price ranges. An asking price can affect which searches include your property and how buyers compare it with other options.

That doesn’t mean there is one perfect price point or that a particular search range guarantees more interest. It means the asking price is part of how your home is positioned for buyers to consider.

Recent sales help show what buyers have paid. Active listings show what they can choose from now, though an asking price does not prove what a property will sell for.


Market Conditions Can Change

Buyer demand, available listings, interest rates, financing conditions and broader economic circumstances can all influence how buyers approach a purchase. Local market activity can also vary between communities and property types.

Season and timing may affect the number of buyers who are active, but there is no single season that guarantees a stronger result for every home. The relevant question is how your property fits the conditions and competition at the time you plan to sell.

That’s one reason a pricing discussion should use current information. The market when you first considered selling may not be the same market you face when you are ready to list.

Hand using a blue pen to review charts showing market trends.

The Risks of Getting the Price Wrong

A price that is higher than the available evidence may cause some buyers to rule out the property or focus on alternatives. If a home stays on the market while competing properties attract interest, buyers may start asking why. A later price reduction can also change how they interpret the listing.

Pricing below the evidence has different risks. It may fail to reflect the property’s features, condition or current competition, and it can leave the seller wondering whether a different strategy would have been more appropriate.

Neither outcome can be predicted with certainty. A supported asking price gives you a more informed starting point and a clearer basis for reviewing buyer response.


What Buyer Response Can Tell You

Once the home is listed, buyer activity provides new information. Online views, showing requests and feedback can help show whether the listing is reaching buyers and how they are responding to the property and its price.

One comment or one quiet day does not necessarily call for a change. It is more useful to look for patterns and consider them alongside current competition and any new sales.

If buyers are showing interest but raising similar concerns, that feedback may help clarify how they see the property. If your home is receiving little activity while comparable properties are drawing attention, it may be time to review the overall position.

REALTOR® and homeowner discussing feedback at a kitchen table.

Practical Steps for Sellers

When you’re considering an asking price:

  1. Review recent sales of properties that are genuinely comparable to yours.

  2. Compare your home with current listings buyers may also consider.

  3. Look at your property’s location, condition, features and services.

  4. Consider current market activity and your timing.

  5. Listen for patterns in showing feedback and buyer response.

  6. Revisit the strategy when new information gives you a reason to do so.

A CMA can provide a data-informed starting point, while local knowledge helps explain how the comparisons relate to your particular property.


Pricing Is Part of the Selling Plan

Price works alongside preparation, photography, marketing and the terms you are willing to consider. My role is to review the property and market information with you, explain how the comparisons apply and discuss whether any adjustments make sense as buyer response comes in.

My Selling Your Home in Nova Scotia guide explains how pricing fits into the broader selling process. You can also review 9 Home Selling Mistakes to Avoid in Nova Scotia while preparing to list.

If you’re thinking about selling, you can request a home evaluation. When we meet, I’ll review your property, recent sales, current competition and plans with you. I’ll also provide a copy of my Complete Home Seller Handbook to help you follow the process.

I’m always here to help.

Read

What to Prepare Before Listing

Getting ready to sell involves more than deciding what to clean or repair. It also helps to gather information about the home, its systems, past work and the items that may stay with the property.

You may already have many of these details in a folder, email or service record. You don’t need to have everything assembled before we talk. Start with what you have, and we can identify what may be useful for your particular home.


What information should I gather before listing?

Start with the basic property information and any records you already have. This may include the civic address, property tax information, a survey or property plan, utility details, appliance manuals and warranties.

If you own more than one parcel, make a note of each parcel you believe is part of the sale. If you have a survey or plan, keep it with the other property information. Don’t rely on a fence or other visible feature to confirm a boundary.

The useful records will vary from one property to another. Gather what you have rather than delaying a conversation because you’re missing a particular document.

A homeowner and REALTOR® reviewing a room during a pre-listing walk-through.

What should I keep about repairs and improvements?

Make a simple list of significant work completed during your ownership. Include the approximate date, the type of work and any contractor or service information you still have.

Receipts, warranties, permits, manuals and service records can help explain what was done and when. Heat-pump installation or service records, roof work, window replacement and major renovations are examples of information a buyer may ask about.

If you aren’t certain of a date or detail, don’t guess. Note that you’re unsure, and we can decide how best to describe the information accurately.

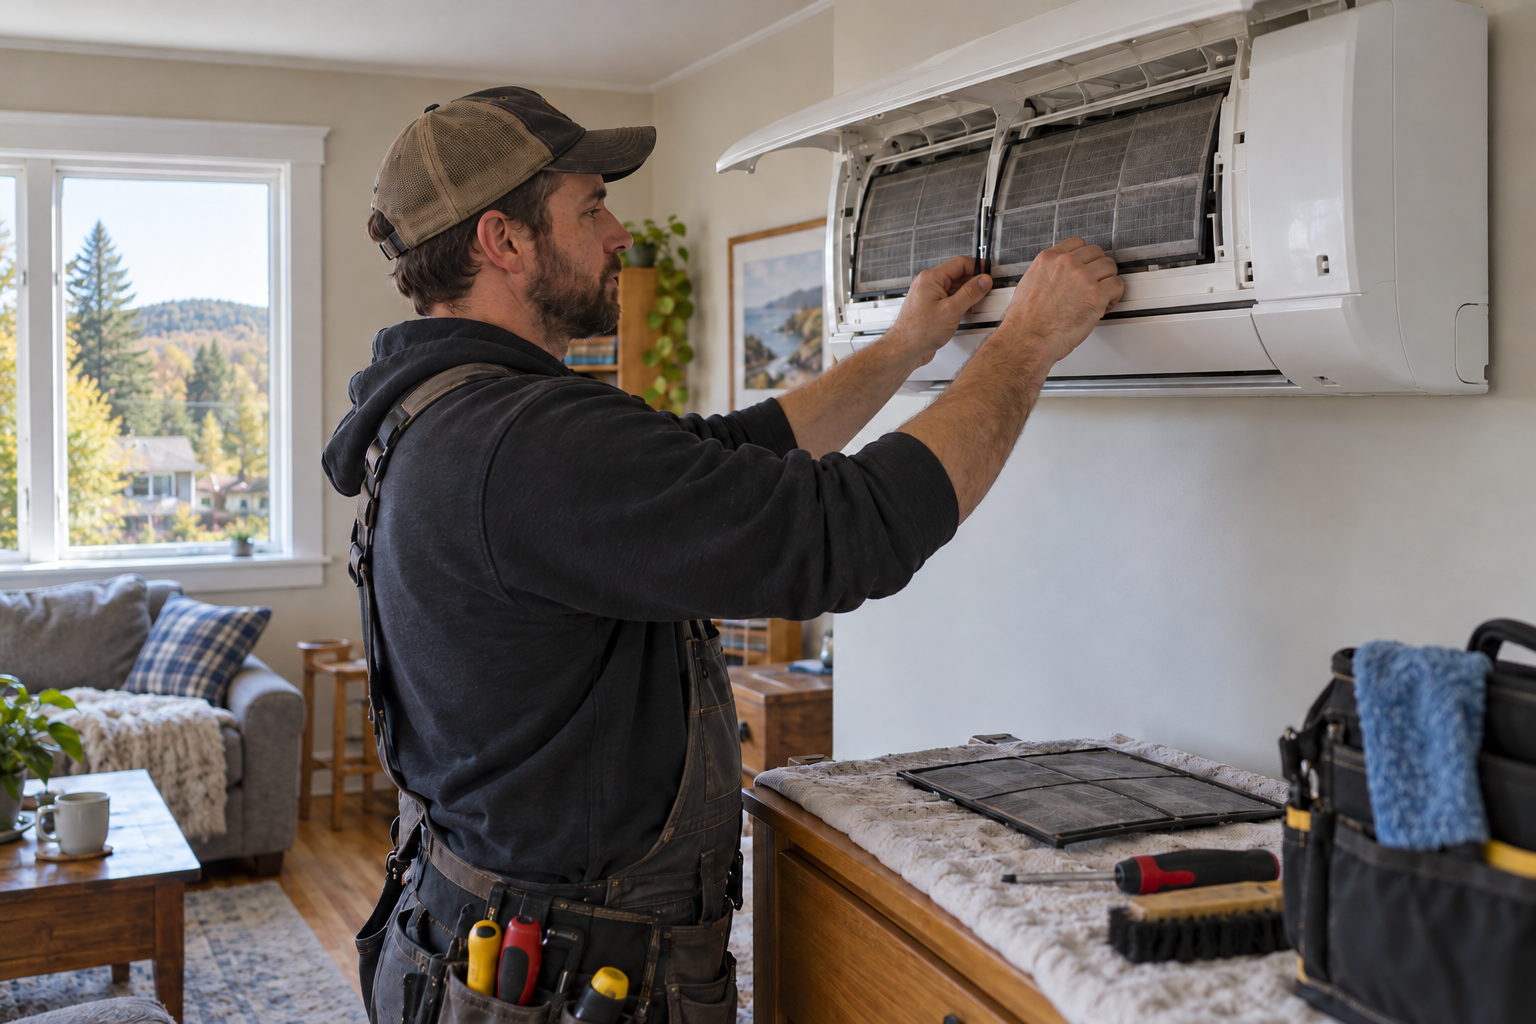
A home maintenance professional working on a heat pump in a house.

If your home has a private well

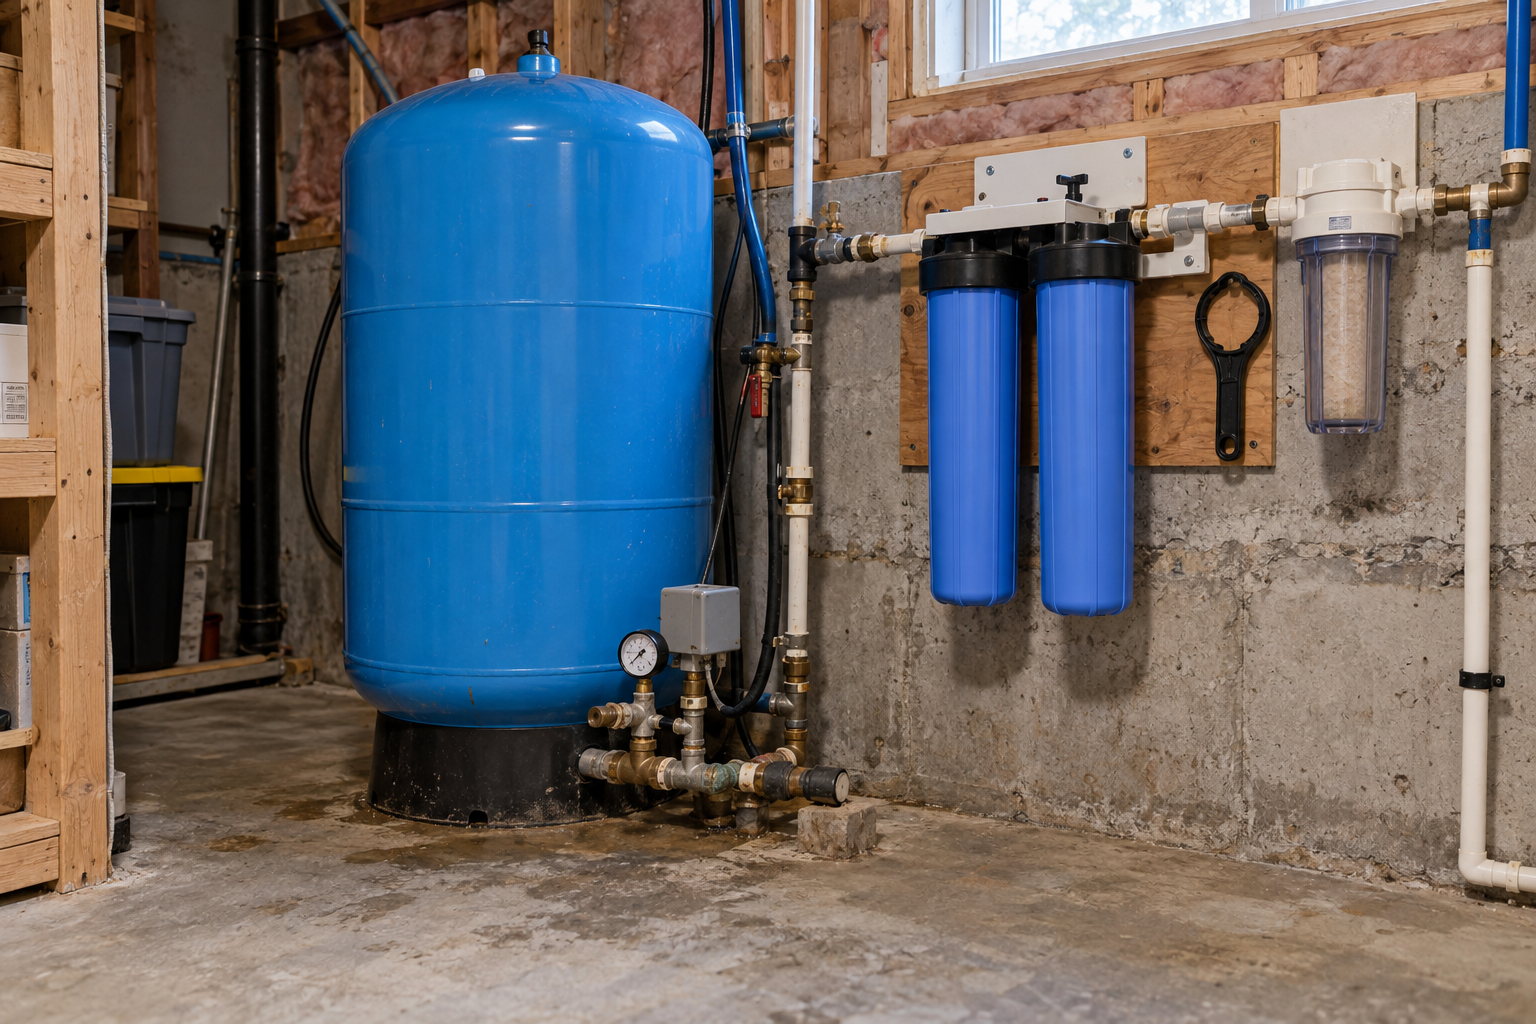
Private wells are found in rural areas and in some towns. If your home has one, gather any well installation, repair or service records you have. Water test results, pump or filter records and information about the well’s location may also be useful if available.

You don’t need to assume that every older record still exists or arrange new testing before we discuss the property. We can review what you have and consider whether anything else may be helpful for your listing.

A pressure tank and water-treatment equipment in a home with a private well.

If your home has a septic system

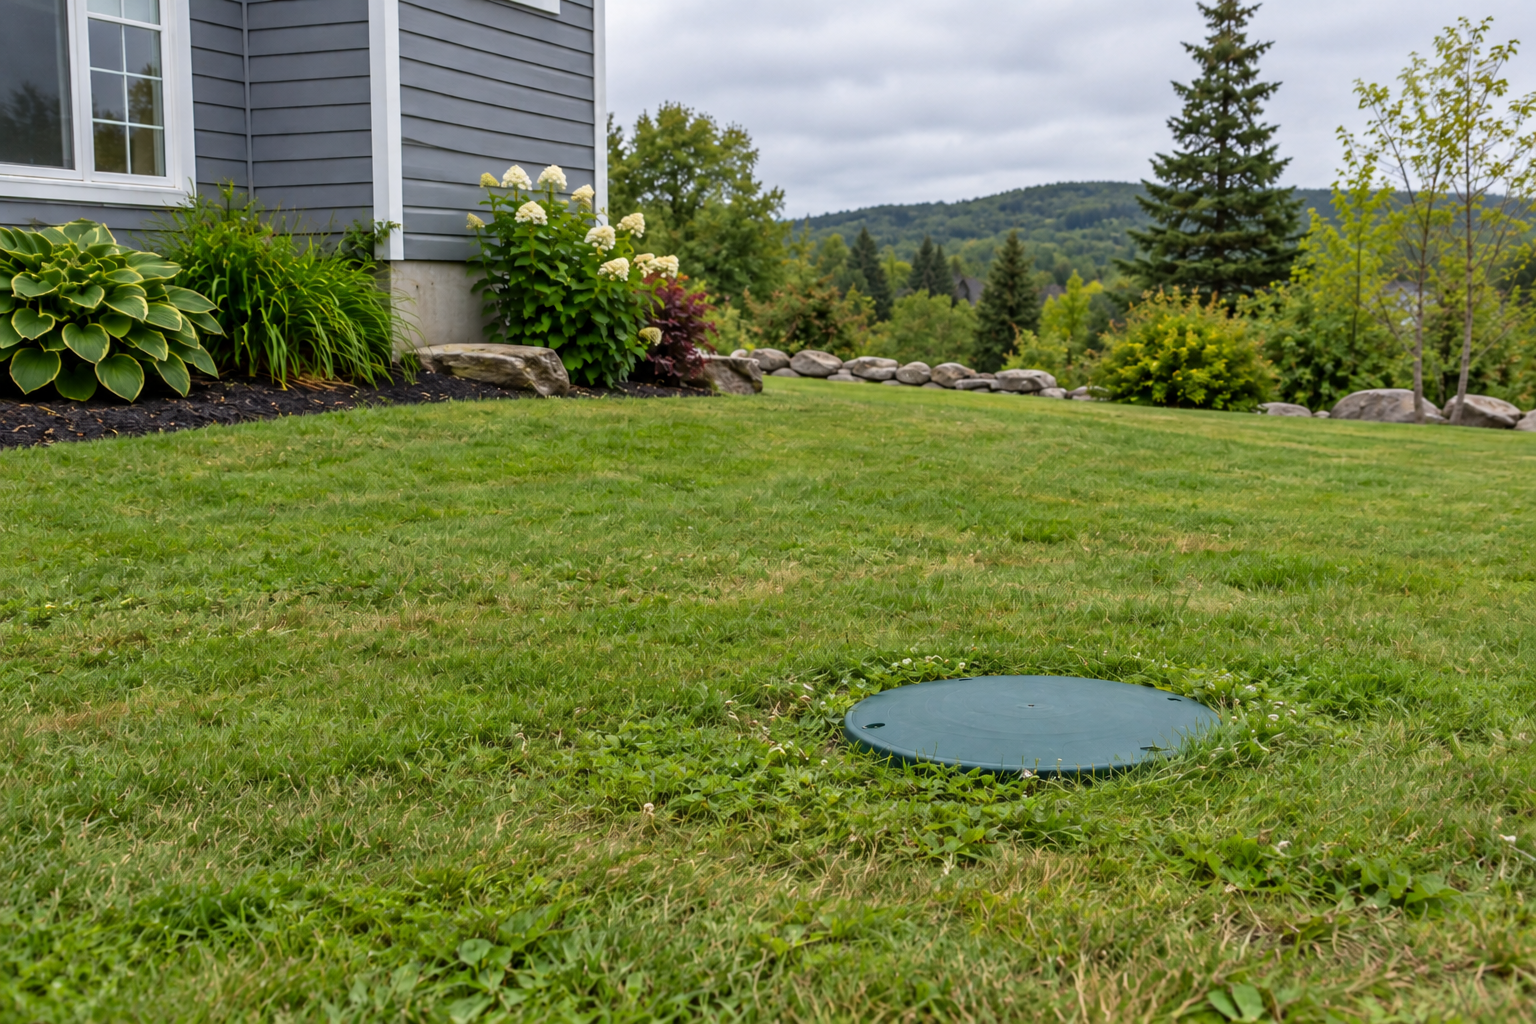
If your home has a septic system, gather any records you have about its type, location, installation, repairs, pumping or maintenance. A plan showing the system’s location may also be useful if you have one.

Records can be helpful even if they’re not recent. If you don’t know where the system is located or can’t find its paperwork, make a note of that rather than guessing. We can discuss the information you have and whether further investigation makes sense.

A green septic access cover visible in a residential lawn.

What if the property has heating equipment or leased items?

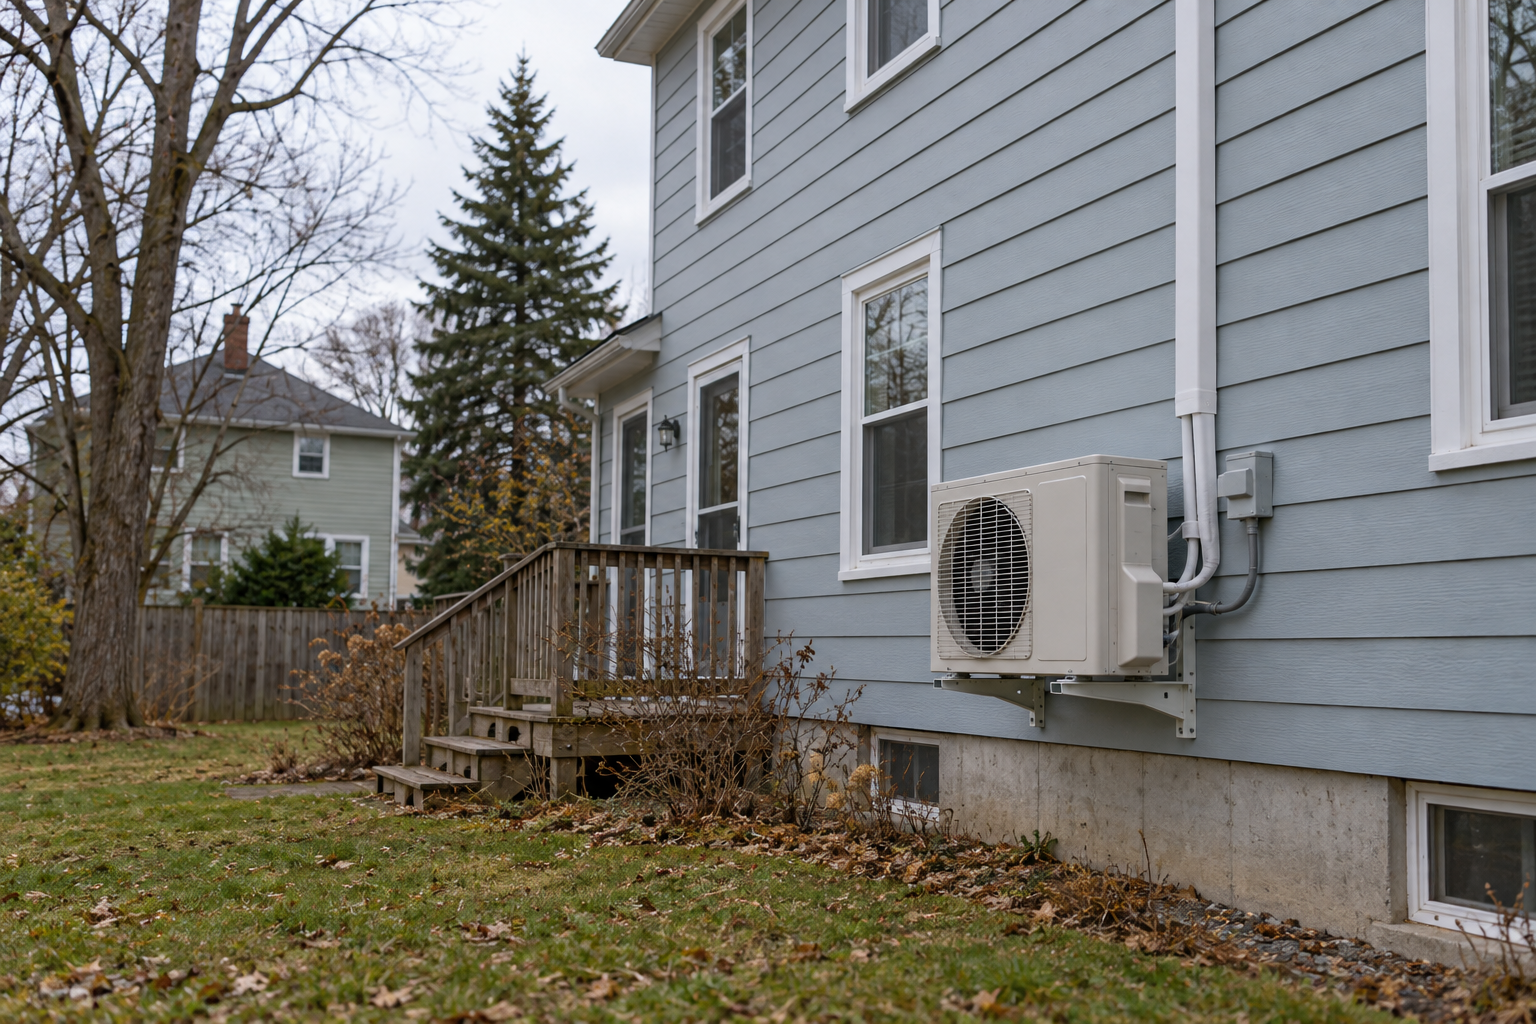
Make a note of the home’s main heating systems and any related service history you have. This may include heat pumps, oil or propane equipment, wood-burning appliances or other systems.

If equipment is rented or leased, gather the agreement and contact information for the provider. The same applies to other leased items or equipment connected with the property. Knowing what is owned, rented or subject to an agreement helps us describe it clearly.

An outdoor heat-pump unit mounted on an ordinary home in an inland residential neighborhood.

Does the property include land, access or outbuildings?

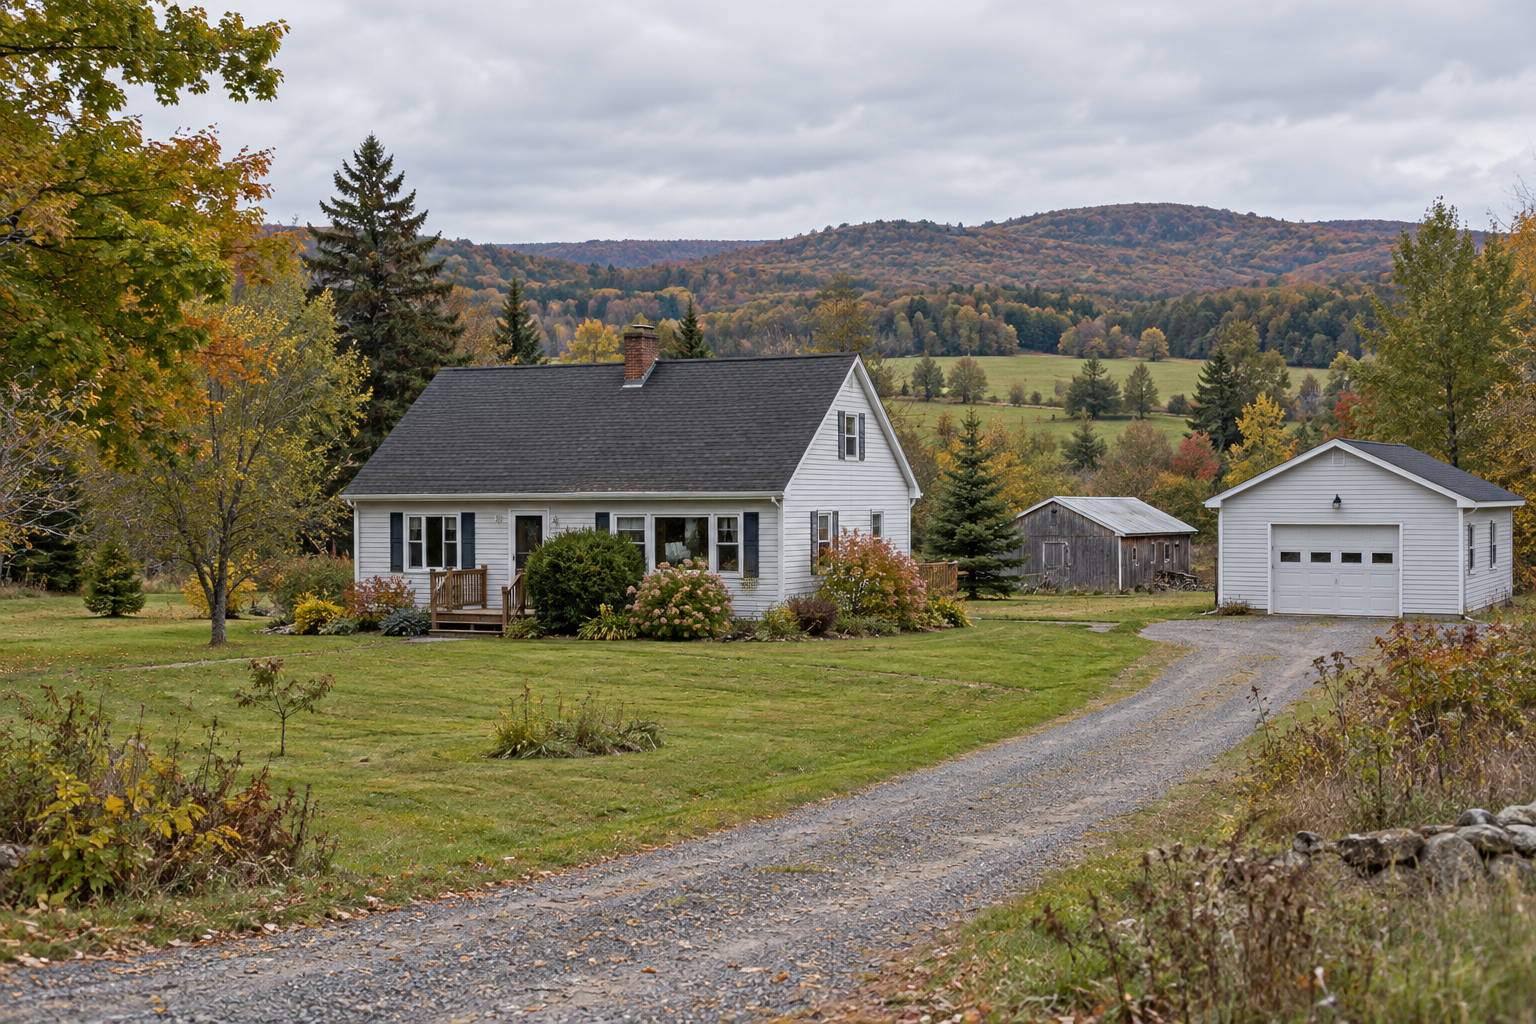
If the sale includes multiple parcels, an outbuilding or a private access arrangement, gather the information you already have about it. This might include property plans, road-maintenance agreements, access documents, building permits or records of work done to an outbuilding.

These details can matter for properties in town as well as those outside town boundaries. If the land, access or what’s included is unclear, don’t make assumptions. We can identify the question and decide who is best placed to answer it.

A driveway and outbuilding on a property in the Annapolis Valley.

What items will stay with the home?

Before listing, make a note of the appliances, fixtures and other items you expect to include, along with anything you intend to take with you. Also note any rented or leased equipment.

This gives us a chance to clarify expectations before the listing details and sale terms are prepared. Specific items can be easy to overlook when they’re part of everyday life in the home.


How should I organize everything?

A folder—paper or digital—is a simple place to keep the information together. You can add service records, receipts, warranties, plans and notes as you find them.

You don’t have to turn it into a complete property history. Start with the records you have and a short list of anything you’re unsure about. That will give us a useful starting point when we talk about the home and your plans.

For an overview of the selling process, read Selling Your Home in Nova Scotia.


Start with what you have

Every property is different, and the useful information depends on the home and its features. A private well, septic system, leased equipment, extra parcel or outbuilding may call for different details than a home with municipal services and no additional structures.

If you’re planning a sale, a home evaluation gives us a chance to discuss your property, timing and what may be worth gathering before listing.

Read

Preparing Your Home for Sale in Nova Scotia

Getting ready to sell doesn’t mean renovating every room or making your home look like somewhere else. The goal is to present it clearly, take care of the things that may distract buyers, and decide where your time and money are best spent.

The right preparation depends on the home, its condition, the likely buyers and your timing. Here’s a practical place to start for sellers in Nova Scotia and the Annapolis Valley.


Where should I start when preparing to sell?

Begin with a walk-through of your home as if you were seeing it for the first time. Look for things that may be difficult for buyers to overlook: unfinished repairs, cluttered surfaces, rooms that are hard to move through, or areas that need a good cleaning.

Make a short list and sort it into three groups:

  • Take care of: basic cleaning, easy maintenance and small repairs.

  • Consider: improvements that may help the home show better, depending on cost and condition.

  • Leave for now: projects that are expensive, disruptive or unlikely to make a meaningful difference.

You don’t need to have everything done before discussing a sale. A walk-through can help us identify what is worth addressing first and what may not be necessary.

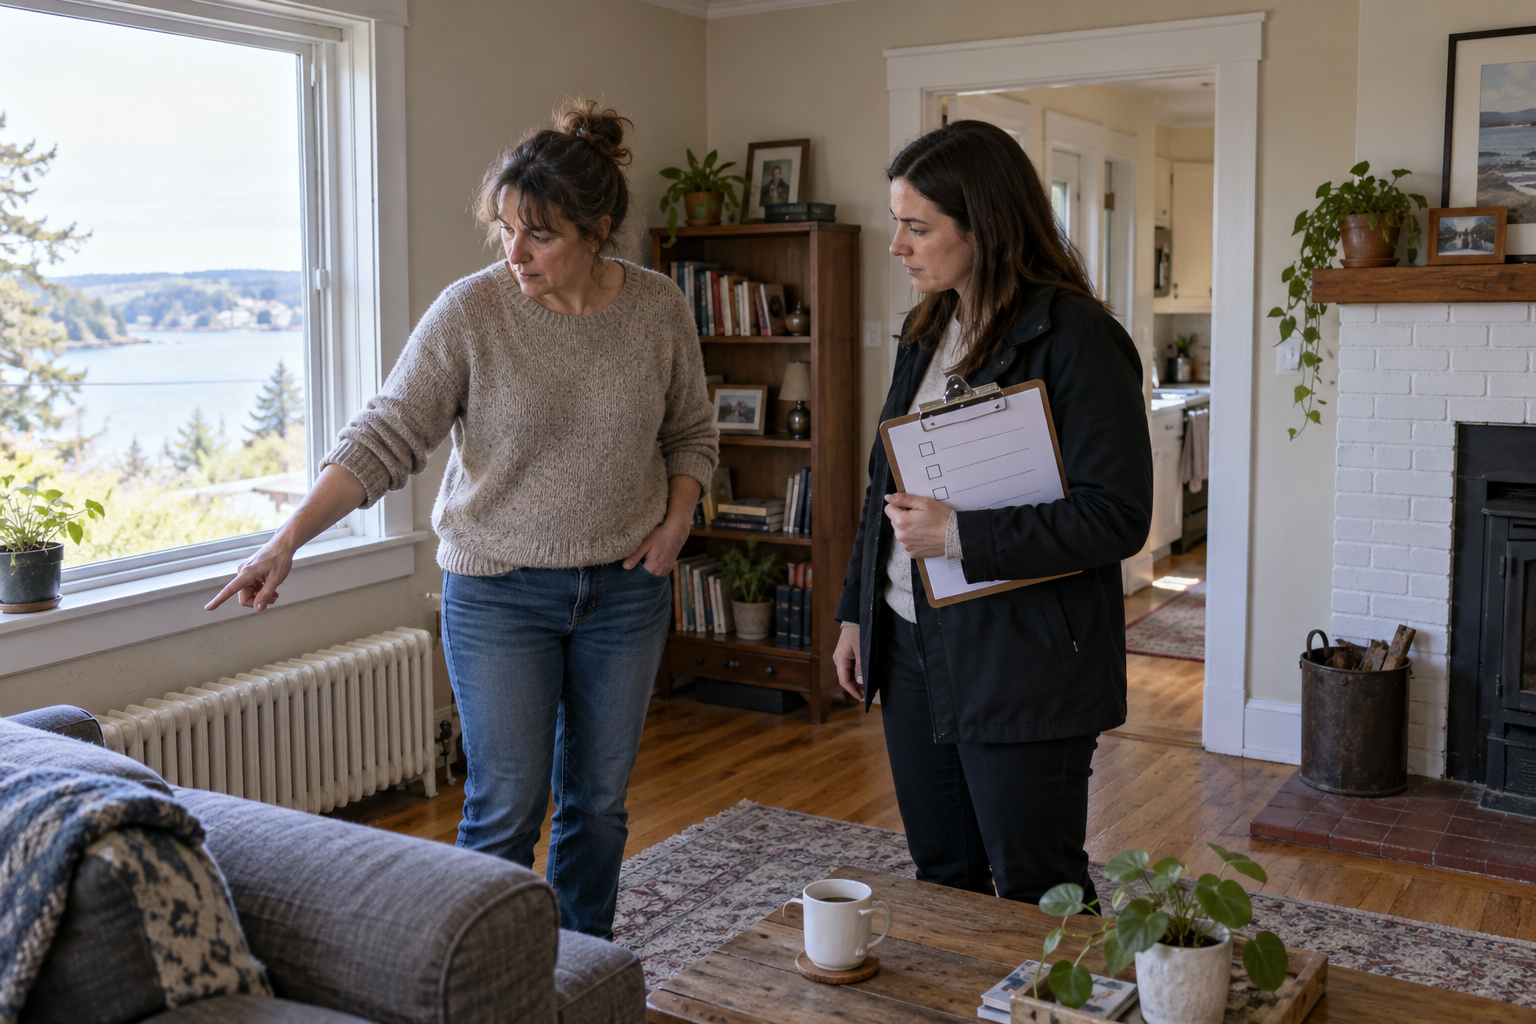
A homeowner and real estate professional assess a room during a home-selling preparation walk-through using a short checklist.

Which repairs should I do before listing?

Start with visible maintenance and items that affect how the home functions. That might include a dripping tap, a loose handle, a burned-out bulb, a sticking door or a damaged screen. A clean, well-maintained home helps buyers focus on the property rather than a list of small distractions.

Before starting a larger renovation, consider its cost, the home’s current condition and what buyers are likely to value. A project can improve presentation without returning its full cost in the sale.

It’s also helpful to make a note of repairs, upgrades and work completed over time. If you know of an issue with the property, let’s discuss it early so we can describe the home accurately and determine what information should be available to buyers.

For other decisions that can make a sale harder than it needs to be, see 9 Home Selling Mistakes to Avoid in Nova Scotia.

Hands tightening a loose kitchen cabinet handle with a screwdriver.

How should I prepare for listing photos?

The photos are often a buyer’s first look inside your home. Preparation doesn’t require removing every personal item; it means making the rooms easy to see and understand.

Before the photographer arrives:

  • Clear kitchen counters and bathroom surfaces where practical.

  • Put away loose items, cords, laundry and everyday clutter.

  • Make beds and straighten cushions, towels and rugs.

  • Clean mirrors, windows and reflective surfaces.

  • Open curtains or blinds to let in natural light.

  • Replace burned-out bulbs and turn on lights where appropriate.

  • Move vehicles and bins away from the front of the home if possible.

  • Tidy the entry, porch and the areas immediately around the house.

The goal is a clear, accurate view of the home—not a staged look that misrepresents how it feels to live there. If a room has an important feature, make sure it isn’t hidden behind furniture or belongings.

A homeowner tidies a lived-in living room before listing photography.

What should I do before each showing?

It helps to have a simple routine you can repeat without having to reset the whole house each time.

Before a showing, put away personal documents, valuables and medications. Make sure pets are safely managed, clear walkways and leave access to rooms and features buyers may want to see. If there are special instructions for the property, such as a gate, outbuilding or access route, we can plan how to communicate those clearly.

You don’t need to make the home look perfect. A tidy, comfortable and accessible home gives buyers a better opportunity to focus on the property.

A tidy home entrance with a clear walkway prepared for a real estate showing.

What should Annapolis Valley sellers consider outside?

The season and property type can change what needs attention. In warmer months, mow or tidy the lawn, clear the entry and keep outdoor areas reasonably accessible. In wet or muddy weather, pay attention to the walkway and entrance. In winter, keep the approach safe and make sure visitors can reach the home.

For rural properties, consider the areas buyers may want to explore: the driveway, yard, outbuildings and access points. Clear paths where practical and make sure gates or other access arrangements are understood. The aim is to help buyers see the property clearly and move around it safely.

A clear walkway leading to a home entrance in the Annapolis Valley.

What should I avoid doing before I sell?

Avoid taking on a large project just because you assume every buyer expects it. The best next step may be a small repair, a thorough cleaning or simply removing clutter—not a major renovation.

Try not to leave all preparation until the last few days before photos. A little time to sort, clean and complete small jobs can make the process less stressful.

And don’t worry if you’re unsure what matters most. We can look at the home, talk about your timing and decide which preparation steps make sense for your situation.


A practical plan for your home

Every home needs a different level of preparation. What makes sense for a newer home in town may be different from what helps an older home, acreage or waterfront property show well.

For a broader overview of the process, read Selling Your Home in Nova Scotia. If you’re deciding what to tackle before listing, a home evaluation gives us a chance to discuss your property, timing and preparation priorities.


Want help deciding what to do first?

You don’t need to finish every project before we talk. We can walk through your home, discuss your timing and identify the preparation that makes the most sense for your property.

If you’d like to start with a conversation about your home, book a home evaluation.

Read

Nova Scotia’s Property Tax CAP: What Home Buyers Need to Know

The property taxes shown in a listing can look reassuring. But before you use that amount in your ownership budget, there is an important question to answer:

Does the seller’s tax bill reflect a capped assessment that will change after you buy?

Nova Scotia’s Capped Assessment Program, usually called CAP, can make the seller’s current taxes a poor guide to your future costs.

When we review a home, I’ll help you look beyond the advertised tax amount and identify what needs to be confirmed before you rely on it.


CAP Limits Assessment Growth, Not Your Entire Tax Bill

CAP limits annual growth in eligible taxable assessments using a rate tied to Nova Scotia’s Consumer Price Index. For 2026, the CAP rate is 2.6%. That is an assessment adjustment, not a municipal tax rate or a guarantee about the increase in your bill. PVSC’s 2026 assessment information.

Property Valuation Services Corporation, or PVSC, assesses properties and administers CAP. Municipalities set tax rates and issue tax bills. PVSC does not set those rates or collect property taxes. About PVSC.

That distinction matters when you are trying to understand a number in a listing. We need to look at both the assessment and the municipal charges applied to it.


Buyer reviewing property assessment information

Understand the Different Assessment Figures

A Property Assessment Notice may show several values:

  • Assessed value: PVSC’s valuation of the property for the assessment year.

  • Capped assessment: The value calculated under CAP, where applicable.

  • Taxable assessed value: The value used for property-tax purposes.

The notice is separate from the municipal tax bill. PVSC’s guide to your assessment notice.

Where CAP applies, taxable assessment is the lower of assessed value and capped assessment. PVSC’s CAP guide.

For a buyer, the useful question is whether there is a substantial gap between those figures. I’ll help you identify that gap and put it into the context of your purchase.


Buyer discussing home ownership questions before purchasing

What Happens After You Buy?

For an ordinary purchase from an unrelated seller, CAP is removed for the assessment year following the sale. It can apply again the following year if the new owner and property qualify.

For example, under the current rules:

TimingAssessment treatment
Purchase during 2026Sale occurs
2027 assessmentCalculated without the seller’s CAP
2028 assessmentNew owner’s CAP can apply if eligible

This follows the purchase timeline explained by PVSC. The seller’s capped value does not simply become your ongoing assessment. PVSC’s CAP guide.

We’ll consider the years after closing when building your budget, rather than relying only on the tax amount available when you make your offer.


A Simple Example Shows Why It Matters

The following figures are hypothetical. They illustrate the effect of a different taxable assessment; they are not a forecast for a particular property or municipality.

Assume a tax rate of $1.00 per $100 of taxable assessment, with no additional charges included.

ExampleTaxable assessmentTax at the illustrative rate
Seller’s capped assessment$200,000$2,000 annually
Buyer’s later uncapped assessment$350,000$3,500 annually
Difference$150,000$1,500 annually

That is $125 more per month to include in a household budget.

The calculation is:

Taxable assessment ÷ 100 × rate per $100

Municipal taxes can also include area rates and other applicable charges. For example, the Municipality of the County of Kings identifies both its general rate and community-specific area rates as part of the calculation. Kings County property-tax information.

The example holds the rate constant to show the assessment effect. Actual assessments, rates and charges may change.


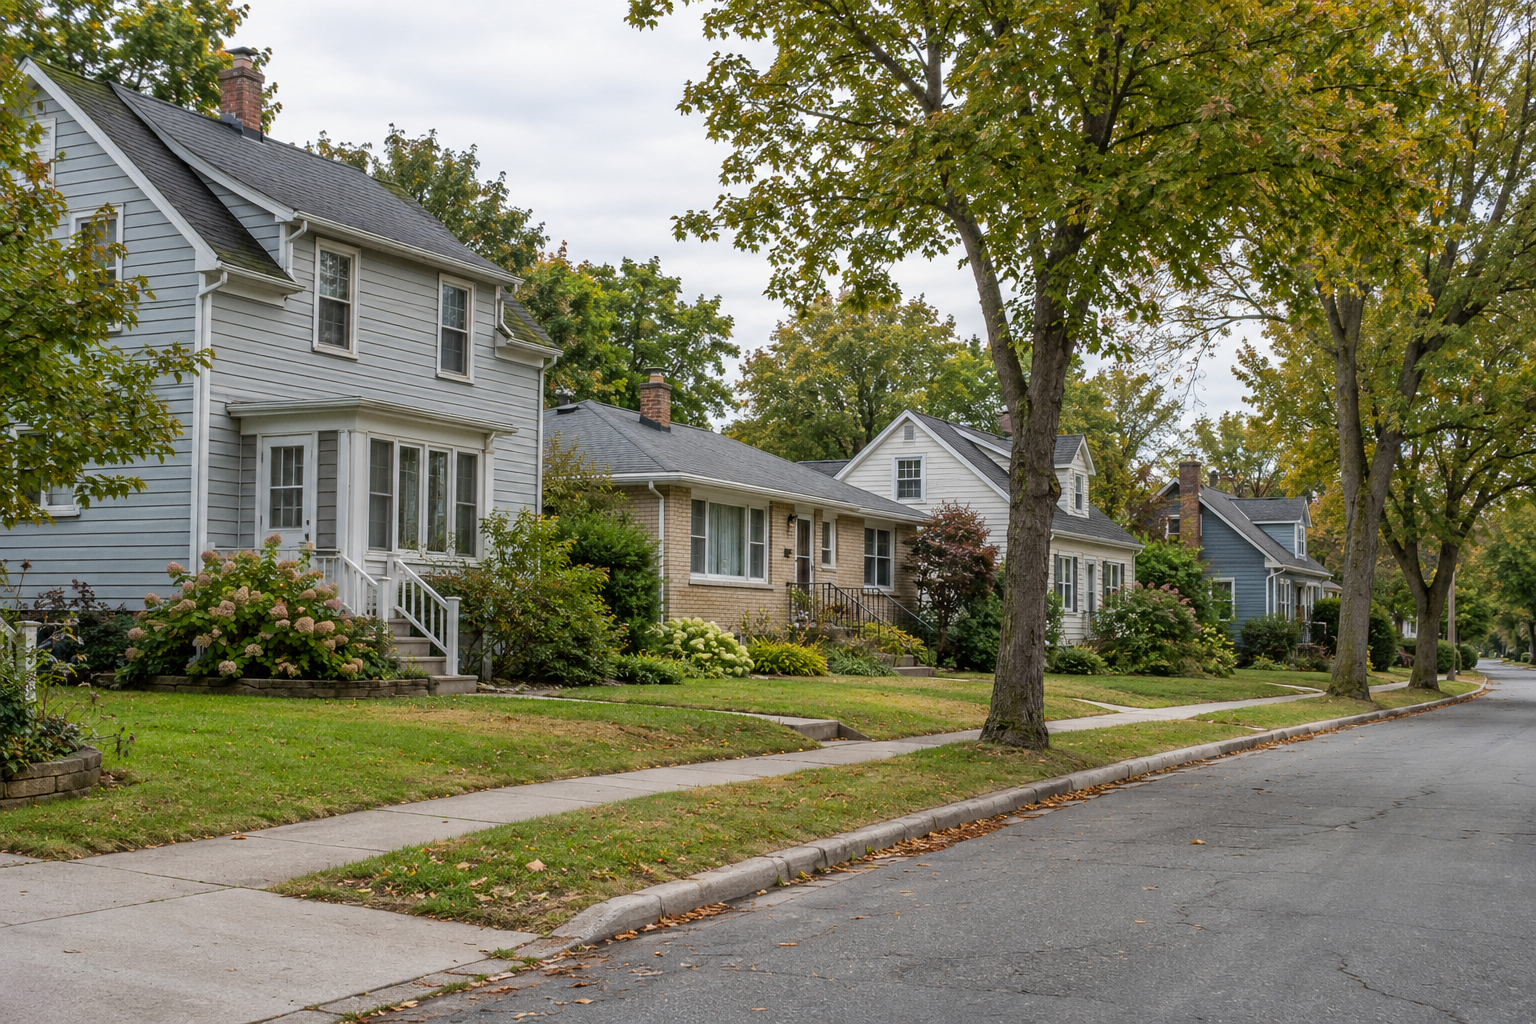
Different homes along an established residential street

Does the Assessment Become Your Purchase Price?

Do not assume that removing CAP means the next assessment will exactly equal the price you paid.

PVSC uses an annual valuation cycle. Its assessment reflects market value at a specified date and the property’s physical condition at another specified date. For example, 2026 assessments reflect market value as of January 1, 2025, and physical condition as of December 1, 2025. PVSC’s assessment timeline.

That timing is one reason an assessment and a current purchase price can differ.

When we review a property, I’ll keep the offer-price discussion separate from the tax estimate. Comparable sales help us consider an offer; the applicable assessment and municipal rates help us investigate taxes.

Neither the seller’s tax bill nor today’s assessment guarantees your future bill.


Eligibility Needs to Be Confirmed

General CAP requirements include at least 50% ownership by a Nova Scotia resident, qualifying property type and ownership duration. Condominiums must be owner-occupied. Certain family transfers have exceptions to the usual sale treatment.

New construction can also affect the calculation: its assessed value is added to the capped amount. PVSC’s CAP guide.

If you are relocating, buying with someone who lives outside Nova Scotia, purchasing through a company or considering a property with several uses, we’ll identify the questions to put directly to PVSC.

The same applies to a family transfer. Before relying on an exception, have PVSC and your lawyer confirm how the particular ownership arrangement will be treated.


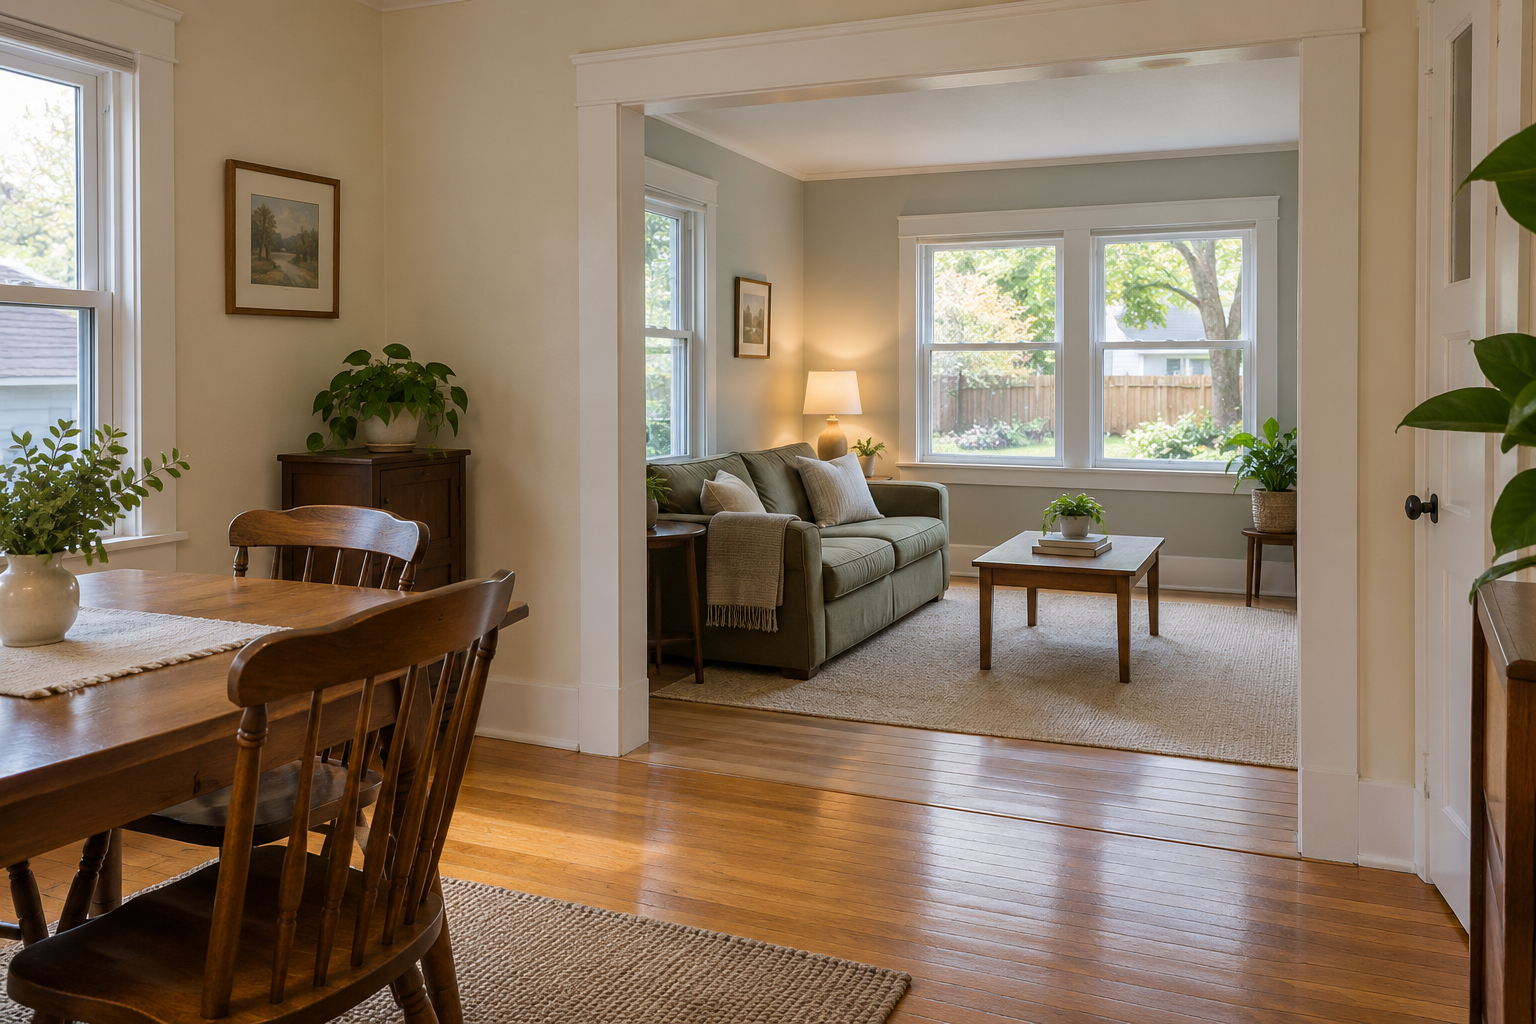
Older home with an adjoining finished living space

Renovation Plans Belong in the Conversation

If you intend to add living space, finish an area or undertake substantial work, include assessment questions in your planning.

PVSC’s annual assessment process accounts for physical changes, including renovations, additions and demolition. PVSC’s assessment timeline.

I’ll help you flag planned work that deserves a conversation with PVSC. Ask how the proposed change could affect the assessment and when it would be reflected.

Avoid building your long-term budget around an assumption that the current assessment will continue unchanged after improvements.


Buyer gathering information about property taxes

How We’ll Check Taxes Before You Make an Offer

When we are considering a property, I’ll help you gather the available information and separate confirmed amounts from estimates.

We’ll work through these questions:

  • What year does the tax amount in the listing cover?

  • What are the current assessed, capped and taxable values?

  • What municipal and area rates apply to this address?

  • Are there separate charges that need to be included?

  • What should PVSC confirm about the purchase and CAP eligibility?

  • What allowance should you make for future changes?

PVSC provides a public assessment search by civic address or assessment account number. Find an assessment through PVSC.

The municipality can explain the rates and charges for the property. I’ll help you bring those pieces together into a working estimate, with any remaining uncertainty clearly identified.


Compare Homes Using Your Expected Costs

A home with lower advertised taxes is not necessarily the less expensive home for you to own.

When comparing properties, we’ll look beyond the seller’s current bill. A difference may reflect assessment history, municipal rates, services or other property-specific circumstances.

For a move within Nova Scotia, we’ll also review the property you are buying on its own merits. Your existing home’s tax amount is not a reliable budget for the next one.

This matters particularly when downsizing. A smaller home may reduce some expenses, but I’ll help you check the numbers before assuming every ownership cost will fall.

The guide How Much Does It Really Cost to Buy a Home in Nova Scotia? covers other expenses to include alongside property taxes.


Read Your Assessment Notice After the Purchase

When your notice arrives, check the property details, assessment figures and CAP treatment.

If something appears incorrect, contact PVSC promptly. An assessment appeal must be received within 31 days of the date on the notice; use the deadline printed on your own notice. PVSC’s assessment-notice guidance.

Keep the assessment notice and municipal tax bill together so you can understand how the figures connect.

Questions about valuation or CAP go to PVSC. Questions about the tax rate, billing or payment arrangements go to the municipality.


Modest home with a small established garden

Build Your Budget Around the Home You Are Buying

Property taxes deserve attention before you commit to a purchase, especially when the seller’s taxable assessment is substantially below the assessed value.

I’ll help you review the available information, identify the questions for PVSC and the municipality, and consider the result alongside your other ownership costs.

The seller’s tax bill is useful background. Your budget needs to reflect what may apply after you buy.

Considering a home in the Annapolis Valley or South Shore? Ask Rob about your next steps. We can review the property and identify the tax questions worth resolving before you make an offer.

Explore the Buyer Resource Centre for more practical guidance on buying and owning a home in Nova Scotia.

Read

Competing Offers: What Happens When More Than One Buyer Wants the Home?

Finding a home that feels right can quickly become more complicated when another buyer wants it too.

You may wonder whether to increase your price, change your conditions or make a decision faster than you expected. You may also have very little information about the other offers.

Understanding how competing offers work in Nova Scotia can help you make a clear decision while keeping your finances, property questions and priorities in view.

For the broader process, start with Making an Offer on a House in Nova Scotia: How the Process Works.


What Is a Competing-Offer Situation?

A competing-offer situation arises when a seller receives more than one written offer on the same property.

A busy showing schedule or someone saying they intend to offer is not the same as another written offer. The Nova Scotia Real Estate Commission specifically distinguishes verbal interest from competing written offers. NSREC guidance on competing offers.

I’ll help you separate what has actually been communicated from expectations about other buyers. A busy showing schedule can create urgency, but your decision should be based on confirmed information.


Buyer and REALTOR® discussing the competing-offer process

What Will You Know About the Other Offers?

In Nova Scotia, the seller directs their brokerage or designated agent on whether to disclose the existence of competing offers and the number received.

The listing representative must not disclose the contents of those offers. Knowing that competition exists does not entitle you to see another buyer’s price, conditions or closing date. NSREC By-law 737.

The Commission also prohibits indirect disclosure, such as telling a competing buyer where their offer ranks or that another offer is higher. NSREC guidance on offer confidentiality.

That leaves uncertainty. Your decision needs to be grounded in the property, your circumstances and the terms you are comfortable offering.


What Can the Seller Do?

The seller may accept an offer, counter one while setting others aside, or reject all of them. A properly structured backup agreement may also be considered.

You should not count on another opportunity to revise your offer. Prepare an offer you would be comfortable having accepted as written. NSREC guidance on the seller’s options.

It helps to think through your response before submitting. If the seller accepts, are you ready to proceed on those terms? If the seller counters, which parts would you reconsider?


Buyers considering how a home fits their needs

The Whole Offer Matters

Price deserves careful attention, but your offer contains several commitments.

Consider the proposed closing date, deposit arrangements, included items, conditions and the time available to complete them. A change that seems small during negotiations may have practical consequences later.

For example, an earlier closing date might require temporary accommodation, a change to your rental arrangements or a different financing plan. A larger deposit requires access to those funds when the agreement says they are due.

Before offering flexibility, check whether it works for you.

A term is only useful if you can carry it out.


Buyer reviewing purchase priorities before making an offer

Set Your Price Limit Before the Pressure Builds

Decide what you are comfortable paying before a competing-offer conversation becomes urgent.

We’ll review comparable sales alongside the home’s condition, location and likely ownership costs. We’ll also consider the work you already know you would want or need to do.

Then consider how the purchase would affect your everyday finances. What would remain available for closing costs, repairs and unexpected expenses?

The asking price is a reference point. Your decision also needs to reflect the property itself and your circumstances.

The guide How Much Does It Really Cost to Buy a Home in Nova Scotia? can help you think beyond the purchase price.

A useful question is: Would I still be comfortable with this purchase if I learned there had been less competition than I expected?


Mortgage Pre-Approval Does Not Approve Every Property

A mortgage pre-approval does not guarantee final financing. The lender still considers the property, and its valuation can affect the amount it will lend.

If you are considering a higher offer, speak with your mortgage professional about that specific price and property. Ask what would happen if the lender’s valuation were lower than your agreed purchase price, and whether additional cash might be required. Financial Consumer Agency of Canada: mortgage pre-approval.

Do not assume that room within a pre-approved maximum resolves every financing question.


Basement framing and foundation in an older home

Conditions Should Reflect What You Still Need to Know

Competition can create pressure to remove an inspection condition or shorten the time available to investigate the home.

The Commission recommends a home inspection and cautions that a seller’s disclosure statement reflects the seller’s knowledge; it does not establish that every defect is known. NSREC guidance on home inspections.

Consider the questions still unanswered about this particular property. Can it be financed and insured on acceptable terms? What investigations remain outstanding? Are there documents your lawyer needs to review?

Our guide Conditions in a Real Estate Offer: What Nova Scotia Buyers Should Know explains how those questions relate to the agreement.

Before changing a condition, ask the relevant professional what the change would mean. If you are considering a shorter deadline, check actual appointment availability and turnaround times.

An unanswered question remains unanswered even when another buyer wants the home.


An Offer Review Date Is Not a Guarantee That the Seller Will Wait

A seller may set a date for reviewing offers. However, the Commission explains that the seller can consider an earlier offer, including one that expires before the announced review date.

This is often called a pre-emptive offer. The seller may accept it, reject it, counter it or leave it unanswered. NSREC guidance on offer review dates.

I’ll clarify the seller’s current instructions, explain your offer’s expiry time and keep you informed of changes communicated to me.


Escalation Clauses Are Not an Available Shortcut

You may encounter advice from other markets suggesting an offer that automatically increases above a competing offer.

The Nova Scotia Real Estate Commission states that licensees cannot use escalation clauses when preparing an Agreement of Purchase and Sale. Adding one in a schedule does not make it compliant. NSREC guidance on escalation clauses.

I’ll help you assess the available sales information and prepare an offer at a specific price you understand and are comfortable paying.


Buyer discussing an offer decision by phone

You Can Decide to Hold Your Position

Learning about competition does not mean you must increase your price or change your terms. We’ll review your options together, including keeping your offer as written. If you are considering withdrawing it, I’ll confirm its status and explain when legal advice is needed before you act.

You may decide the offer already reflects what the property is worth to you. You may also decide that a proposed change would leave too little financial room or too much uncertainty.

Those are reasonable limits to establish before the conversation becomes rushed.


If Your Offer Is Not Accepted

It is disappointing to miss a home you had begun imagining yourself living in.

Before changing your approach for the next property, review the experience. Were you comfortable with your price? Did you understand the terms? Did the home suit your needs well enough to justify the commitments you offered?

Avoid assuming that one unsuccessful offer means you should remove protections or stretch further next time.

If a backup agreement is proposed, I’ll walk you through its terms and help identify anything your lawyer should clarify. Before signing, you should understand when it could take effect, how long you would be committed and what it would mean for your continued search.


Maintained home in an established residential neighbourhood

Make an Offer You Can Live With

A competing-offer situation can move quickly. Preparing your limits in advance gives you more space to think when decisions are time-sensitive.

I’ll help you assess the property, review the available sales information and understand the commitments in your offer. We’ll discuss where you have flexibility and which questions still need answers from your lender, inspector, insurer or lawyer.

The right offer is one you understand and are prepared to carry through if accepted.

Considering an offer on a home in the Annapolis Valley or South Shore? Ask Rob about your next steps. We can work through the property, your priorities and the questions that matter before you decide how to proceed.

Explore the Buyer Resource Centre for more practical guidance on buying a home in Nova Scotia, from evaluating a property to preparing an offer and planning for ownership.

Read

Conditions in a Real Estate Offer: What Nova Scotia Buyers Should Know

You’ve found a home you want to buy.

But there are still things you need to confirm.

Will your lender approve the financing for this particular property? What will the inspection reveal? Can you obtain suitable insurance? If the home has a private well and septic system, what should you investigate?

Those questions are part of deciding whether you’re comfortable completing the purchase.

The conditions in your offer help establish what needs to be investigated or arranged, and when those decisions must be made.

Understanding them before you sign is an important part of buying a home in Nova Scotia.


What Is a Condition in a Real Estate Offer?

A condition makes the purchase subject to a specified requirement under the terms of the agreement.

For example, a buyer may need satisfactory financing, a property inspection or an opportunity to review information about the property.

The standard Nova Scotia Agreement of Purchase and Sale includes a buyer’s conditions section with options covering financing, property inspections, insurance and certain documents. The conditions selected and any additional wording need to reflect the transaction. NSREC’s standard purchase agreement

Before agreeing to a condition, understand:

  • What you need to obtain, investigate or review

  • Who is responsible for doing it

  • What deadline applies

  • What notice the agreement requires

  • What happens if the requirement isn’t satisfied

The wording matters as much as the name of the condition.


Start With the Questions This Property Raises

It is tempting to think of conditions as a standard checklist that gets attached to every offer.

A better starting point is the property itself.

An older rural home may raise questions about water, septic, heating, outbuildings and access.

A condominium may require careful review of documents about the corporation and its finances.

A home in a leased-land community involves a different ownership arrangement from a conventional freehold property.

Your own circumstances matter too.

Do you need mortgage financing?

Does the purchase depend on selling your existing home?

Are you buying because you intend to operate a business, add another dwelling or keep animals?

Explain those plans early.

Something that is essential to your decision should be discussed before the offer is prepared.


Buyer discussing mortgage requirements with a lending professional

A Financing Condition Deserves More Than a Pre-Approval

A mortgage pre-approval helps establish what you may be able to borrow, but it does not guarantee that your mortgage will ultimately be approved.

The Financial Consumer Agency of Canada explains that a lender may still decline the mortgage because of the property, its appraised value or other requirements. FCAC’s mortgage pre-approval guidance

During your financing investigation, ask your mortgage professional:

Has the lender reviewed this specific property and purchase price?

Is an appraisal required?

Are any documents still outstanding?

Are there requirements involving my down payment or existing home?

Is there anything unresolved that affects my ability to complete the purchase?

Try to obtain a clear explanation of what has been approved and what remains to be done.

A reassuring conversation is useful. Understanding the outstanding requirements is more useful when you’re deciding whether to waive a financing condition.


Home inspector examining kitchen plumbing while a buyer observes

An Inspection Condition Gives You Information to Evaluate

A showing helps you decide whether you like a home.

A home inspection gives you an opportunity to investigate its condition more closely.

NSREC strongly recommends a home inspection and notes that a seller’s Property Disclosure Statement reflects the seller’s knowledge, which may not include every defect. NSREC’s home-inspection guidance

Think beyond simply booking an appointment.

You also need time to receive the findings, ask questions and decide whether further investigation is appropriate.

If an inspector recommends an electrician, roofer or structural professional, that recommendation may introduce another step before you’re ready to make a decision.

My guide to home inspections explains what buyers should expect from the inspection itself.

For your offer, the practical question is:

Does the condition and its timeline allow the investigation this property may need?


Water sample being collected for testing during a property investigation

Some Properties Need Additional Testing

A general inspection may be only part of your due diligence.

Depending on the property, you may want to discuss:

  • Well-water testing

  • Water-supply information

  • Septic-system inspection

  • Wood-burning appliance inspection

  • Specialist assessment of a building component

  • Review of permits or renovation records

  • Investigation of access or boundary questions

NSREC provides a Water and Septic Schedule, along with other schedules for particular property types. These can add requirements beyond those in the main agreement. NSREC’s guide to real estate forms

Don’t assume that saying “home inspection” automatically addresses every concern.

Explain what you need to learn so the appropriate investigation and contract wording can be considered.

Beyond the Home Inspection explores the additional tests and investigations a buyer may need.


Older home showing roof, chimney and exterior electrical service

Insurance Should Be Investigated Early

Before committing to a purchase, find out whether you can obtain suitable insurance for the property and your intended use.

An insurer may ask about the home’s electrical system, heating equipment, roof and other features. The Insurance Bureau of Canada specifically identifies these as factors insurers consider. IBC’s explanation of home-insurance factors

When discussing coverage, ask:

Does this quote reflect the actual property information?

Is additional documentation required?

Would any work need to be completed?

Are there exclusions or limitations I should understand?

Does the proposed coverage fit how I plan to use the property?

Give the insurer accurate information about matters such as a wood stove, rental use or an expected period of vacancy.

The purpose is to understand the arrangement you can actually obtain before making your decision.


Reviewing Documents Is Part of the Investigation

Some important questions won’t be answered by walking through the house.

You may need to review a Property Disclosure Statement, equipment information, restrictive covenants or documents associated with the property type.

A PDS records information based on the seller’s knowledge. NSREC describes receiving it as the beginning of a conversation and directs buyer representatives to pursue relevant follow-up questions. NSREC’s disclosure guidance

Read the answers carefully.

A reference to a previous leak may deserve another question.

A description of leased equipment may lead you to ask about the contract.

A restriction affecting the property may matter if you’re planning a particular use.

Receiving a document and understanding its implications are separate steps.


Special Property Types Can Bring Additional Conditions

The documents needed for one purchase may be quite different from those needed for another.

NSREC’s forms include schedules for resale condominiums, vacant land, mini/mobile/manufactured homes and leased-land communities, and multi-unit residential income properties. NSREC’s guide to real estate forms

For a buyer, the practical lesson is to look beyond the main offer form.

Read the attached schedules.

Ask which information must be supplied and which matters require your review.

If you don’t understand something in a schedule, raise it before signing rather than assuming it is routine wording that won’t affect you.


What If You Need to Sell Your Current Home?

If buying depends on selling your existing property, explain that when discussing the offer.

NSREC has a Sale of Buyer’s Property Schedule for transactions where the sale of the buyer’s current property is made a condition of the purchase. NSREC’s explanation of the sale-of-property schedule

Before proceeding, discuss questions such as:

  • Does your home need to be listed, sold or closed?

  • What happens if another buyer becomes interested in the property you want?

  • Could you complete the purchase if your sale were delayed?

  • What financing would be available?

  • How do the two transactions’ dates fit together?

Don’t assume that a general financing discussion has resolved all the risks of coordinating two properties.

Your REALTOR®, mortgage professional and lawyer may each have a part in working through the arrangement.


Buyer discussing a purchase agreement with a lawyer

Lawyer Review Has Its Own Purpose

Legal questions deserve legal advice.

A lawyer can help you understand the agreement and the legal issues associated with the purchase.

Under the standard Nova Scotia APS, lawyer review concerns the wording and content of the agreement, with the lawyers acting reasonably. It has its own deadline and notice provisions. NSREC’s standard purchase agreement

Arrange legal representation early and make sure your lawyer receives the documents promptly.

Also explain anything unusual about your plans for the property.

If your concern is whether you can operate a business, build an addition or use an access route, say so explicitly. Don’t assume another professional knows why that issue is important to you.


Give Yourself Enough Time to Investigate

A short condition period can sound appealing during negotiation.

But the useful question is whether the work can actually be completed.

Before proposing a deadline, consider:

  • Inspector and specialist availability

  • Laboratory processing time

  • Documents your lender still needs

  • Insurer response times

  • Your lawyer’s availability

  • Access to the property

  • Weekends and holidays

  • Time to understand the results

For example, having an inspection on the final afternoon may leave very little opportunity to investigate a concern it uncovers.

Build the schedule around the work, including the possibility of follow-up questions.

A deadline should allow time for a decision, not just an appointment.


Buyer coordinating property investigations by phone

Use the Condition Period Actively

Once the offer is accepted, begin the agreed work promptly.

Send the purchase documents to your lender and lawyer.

Book inspections.

Contact your insurer.

Request outstanding information.

Keep track of what has arrived and what remains unresolved.

A simple working list can help:

Investigation or document

Person responsible

Expected completion

Outstanding questions

Decision required

This is particularly useful when several professionals are involved. One person’s part may be complete while another is still waiting for information.

Stay involved in the results. The professionals provide information and advice, but you need to understand what you’re being asked to accept.


Being Satisfied and Providing Notice Are Separate Steps

For conditions requiring Form 408, you must provide the completed form to the seller or seller’s representative by the agreed deadline, clearly waiving all applicable conditions.

If that does not happen, the agreement is deemed terminated.

Signing the form without delivering it is not enough. NSREC’s Form 408 guidance

Before authorizing the notice, ask your REALTOR® to explain exactly which conditions it covers.

Make sure your decision reflects the information you have received and any outstanding questions.


Not Every Condition Uses Form 408

The standard lawyer-review, title-investigation and condominium estoppel-certificate clauses use notice of dissatisfaction rather than Form 408.

Other schedules can have their own procedures.

Follow the wording and deadlines in your agreement. NSREC’s explanation of different notice procedures

For practical purposes, avoid treating the purchase as though it has one deadline and one form that settles everything.

Ask for a clear explanation of which steps belong to you, your REALTOR® and your lawyer.


What If You Need More Time or Find a Problem?

You can propose an amendment requesting an extension or another solution. The seller may accept, reject or ignore it, or propose different terms.

Until an amendment is accepted, the original terms and deadline remain in effect. A terminated agreement cannot be revived by amendment. NSREC’s guidance on amendments and deadlines

Raise delays and concerns as soon as they appear.

If you’re waiting for a specialist, make that known while there is still time to consider options.

If an inspection finding changes your view of the purchase, my guide The Inspection Found Problems — What Happens Next? explains the decisions that may follow.


What If You Remain Unsatisfied?

Under the standard buyer-condition process, a buyer who is unsatisfied may terminate before the deadline in accordance with the agreement.

Discuss the appropriate steps with your REALTOR® and obtain legal advice where needed. NSREC’s buyer-condition guidance

Explain the actual concern and the information behind your decision.

Don’t rely on assumptions about what a condition allows, particularly if the wording has been changed or the issue is disputed.


A Terminated Agreement Doesn’t Automatically Release the Deposit

Termination and release of money held in trust are separate matters.

NSREC explains that a brokerage must retain the deposit until it receives the required written mutual direction or a court order authorizing disbursement. This applies even where the funds are not being disputed. NSREC’s deposit guidance

If the purchase ends, ask what documentation is required and who is arranging it.

Understanding that process can prevent confusion about when the money will become available.


Be Careful About Removing a Condition Before You Have Answers

A decision to proceed should reflect what you know and the uncertainty you are prepared to accept.

Before waiving a condition, ask yourself:

Have I received the information I was waiting for?

Do I understand the findings?

Have I spoken with the appropriate professional?

Is there an unresolved issue that could affect my decision?

Am I relying on an assumption that still needs to be checked?

If you feel rushed, explain why.

Perhaps a report has arrived but you haven’t discussed it with the inspector. Perhaps the lender has responded but you don’t understand an outstanding requirement.

Identify the gap before making the decision.


Buyer taking another look through a home before deciding to proceed

Conditions Work Best When They Lead to Better Information

The purpose of this stage is to understand the purchase more fully.

Can you arrange the financing?

Does the property’s condition work for you?

Can you obtain suitable insurance?

Do the documents raise questions that need answers?

Are there additional investigations appropriate for this home?

A useful condition addresses a real question, allows time to investigate it and provides a clear process for deciding what happens next.

Before you agree to proceed, understand what you have learned—and what you are accepting.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read