
You’ve found a home you want to buy.
But there are still things you need to confirm.
Will your lender approve the financing for this particular property? What will the inspection reveal? Can you obtain suitable insurance? If the home has a private well and septic system, what should you investigate?
Those questions are part of deciding whether you’re comfortable completing the purchase.
The conditions in your offer help establish what needs to be investigated or arranged, and when those decisions must be made.
Understanding them before you sign is an important part of buying a home in Nova Scotia.
What Is a Condition in a Real Estate Offer?
A condition makes the purchase subject to a specified requirement under the terms of the agreement.
For example, a buyer may need satisfactory financing, a property inspection or an opportunity to review information about the property.
The standard Nova Scotia Agreement of Purchase and Sale includes a buyer’s conditions section with options covering financing, property inspections, insurance and certain documents. The conditions selected and any additional wording need to reflect the transaction. NSREC’s standard purchase agreement
Before agreeing to a condition, understand:
What you need to obtain, investigate or review
Who is responsible for doing it
What deadline applies
What notice the agreement requires
What happens if the requirement isn’t satisfied
The wording matters as much as the name of the condition.
Start With the Questions This Property Raises
It is tempting to think of conditions as a standard checklist that gets attached to every offer.
A better starting point is the property itself.
An older rural home may raise questions about water, septic, heating, outbuildings and access.
A condominium may require careful review of documents about the corporation and its finances.
A home in a leased-land community involves a different ownership arrangement from a conventional freehold property.
Your own circumstances matter too.
Do you need mortgage financing?
Does the purchase depend on selling your existing home?
Are you buying because you intend to operate a business, add another dwelling or keep animals?
Explain those plans early.
Something that is essential to your decision should be discussed before the offer is prepared.
A Financing Condition Deserves More Than a Pre-Approval
A mortgage pre-approval helps establish what you may be able to borrow, but it does not guarantee that your mortgage will ultimately be approved.
The Financial Consumer Agency of Canada explains that a lender may still decline the mortgage because of the property, its appraised value or other requirements. FCAC’s mortgage pre-approval guidance
During your financing investigation, ask your mortgage professional:
Has the lender reviewed this specific property and purchase price?
Is an appraisal required?
Are any documents still outstanding?
Are there requirements involving my down payment or existing home?
Is there anything unresolved that affects my ability to complete the purchase?
Try to obtain a clear explanation of what has been approved and what remains to be done.
A reassuring conversation is useful. Understanding the outstanding requirements is more useful when you’re deciding whether to waive a financing condition.
An Inspection Condition Gives You Information to Evaluate
A showing helps you decide whether you like a home.
A home inspection gives you an opportunity to investigate its condition more closely.
NSREC strongly recommends a home inspection and notes that a seller’s Property Disclosure Statement reflects the seller’s knowledge, which may not include every defect. NSREC’s home-inspection guidance
Think beyond simply booking an appointment.
You also need time to receive the findings, ask questions and decide whether further investigation is appropriate.
If an inspector recommends an electrician, roofer or structural professional, that recommendation may introduce another step before you’re ready to make a decision.
My guide to home inspections explains what buyers should expect from the inspection itself.
For your offer, the practical question is:
Does the condition and its timeline allow the investigation this property may need?
Some Properties Need Additional Testing
A general inspection may be only part of your due diligence.
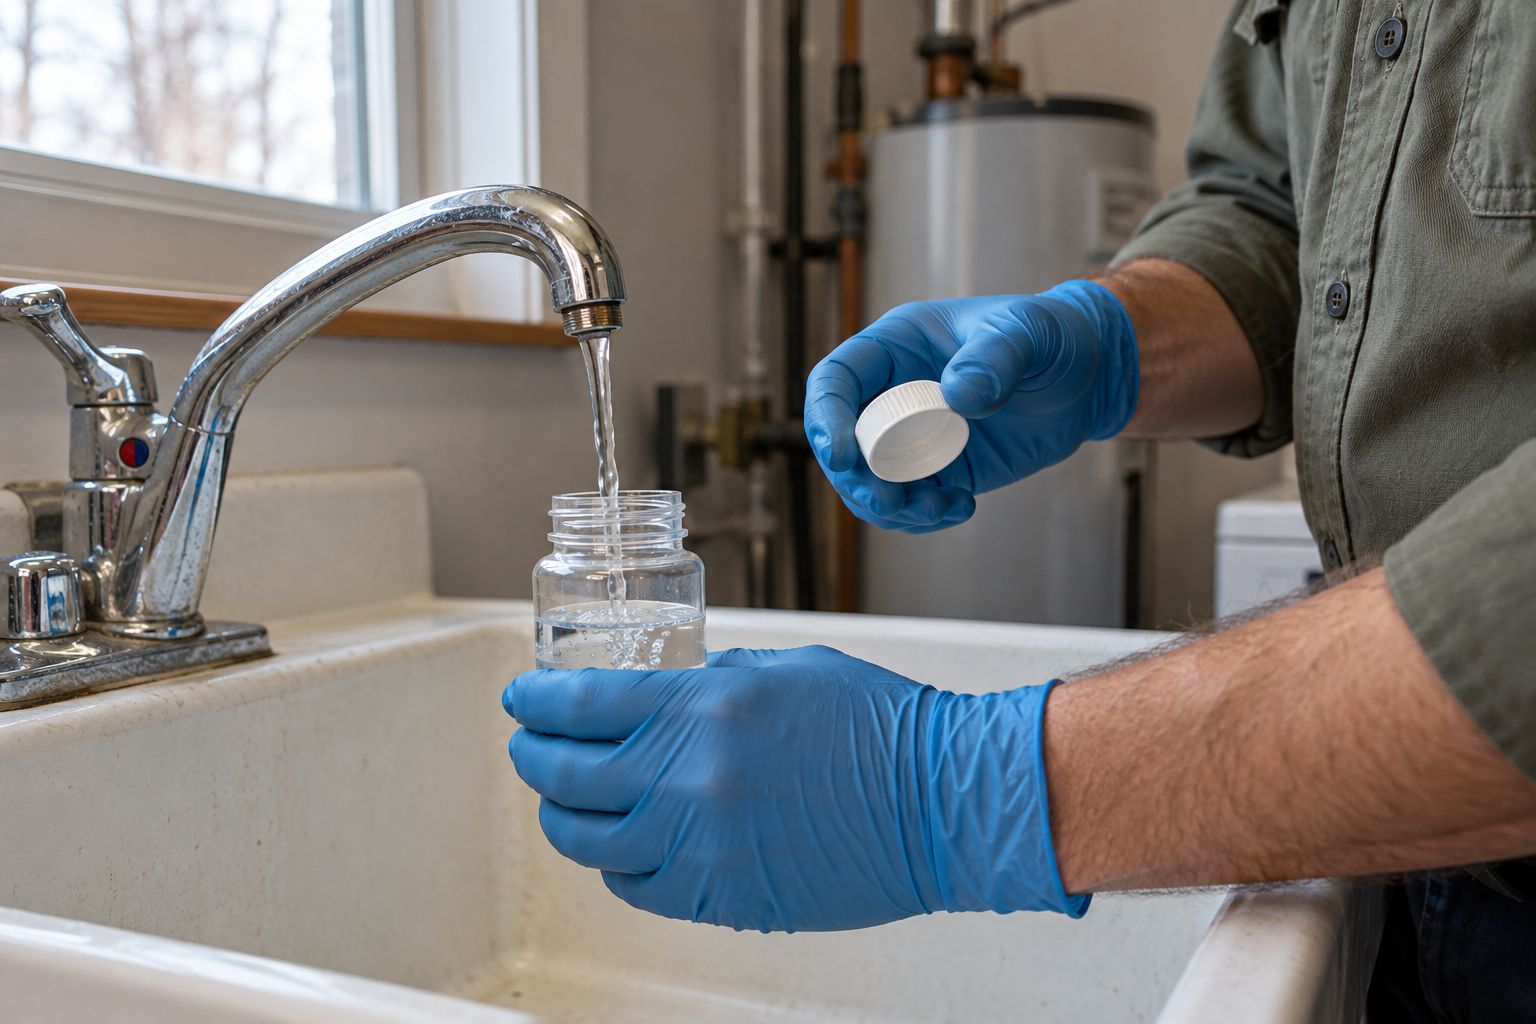
Depending on the property, you may want to discuss:
Well-water testing
Water-supply information
Septic-system inspection
Wood-burning appliance inspection
Specialist assessment of a building component
Review of permits or renovation records
Investigation of access or boundary questions
NSREC provides a Water and Septic Schedule, along with other schedules for particular property types. These can add requirements beyond those in the main agreement. NSREC’s guide to real estate forms
Don’t assume that saying “home inspection” automatically addresses every concern.
Explain what you need to learn so the appropriate investigation and contract wording can be considered.
Beyond the Home Inspection explores the additional tests and investigations a buyer may need.
Insurance Should Be Investigated Early
Before committing to a purchase, find out whether you can obtain suitable insurance for the property and your intended use.
An insurer may ask about the home’s electrical system, heating equipment, roof and other features. The Insurance Bureau of Canada specifically identifies these as factors insurers consider. IBC’s explanation of home-insurance factors
When discussing coverage, ask:
Does this quote reflect the actual property information?
Is additional documentation required?
Would any work need to be completed?
Are there exclusions or limitations I should understand?
Does the proposed coverage fit how I plan to use the property?
Give the insurer accurate information about matters such as a wood stove, rental use or an expected period of vacancy.
The purpose is to understand the arrangement you can actually obtain before making your decision.
Reviewing Documents Is Part of the Investigation
Some important questions won’t be answered by walking through the house.
You may need to review a Property Disclosure Statement, equipment information, restrictive covenants or documents associated with the property type.
A PDS records information based on the seller’s knowledge. NSREC describes receiving it as the beginning of a conversation and directs buyer representatives to pursue relevant follow-up questions. NSREC’s disclosure guidance
Read the answers carefully.
A reference to a previous leak may deserve another question.
A description of leased equipment may lead you to ask about the contract.
A restriction affecting the property may matter if you’re planning a particular use.
Receiving a document and understanding its implications are separate steps.
Special Property Types Can Bring Additional Conditions
The documents needed for one purchase may be quite different from those needed for another.
NSREC’s forms include schedules for resale condominiums, vacant land, mini/mobile/manufactured homes and leased-land communities, and multi-unit residential income properties. NSREC’s guide to real estate forms
For a buyer, the practical lesson is to look beyond the main offer form.
Read the attached schedules.
Ask which information must be supplied and which matters require your review.
If you don’t understand something in a schedule, raise it before signing rather than assuming it is routine wording that won’t affect you.
What If You Need to Sell Your Current Home?
If buying depends on selling your existing property, explain that when discussing the offer.
NSREC has a Sale of Buyer’s Property Schedule for transactions where the sale of the buyer’s current property is made a condition of the purchase. NSREC’s explanation of the sale-of-property schedule
Before proceeding, discuss questions such as:
Does your home need to be listed, sold or closed?
What happens if another buyer becomes interested in the property you want?
Could you complete the purchase if your sale were delayed?
What financing would be available?
How do the two transactions’ dates fit together?
Don’t assume that a general financing discussion has resolved all the risks of coordinating two properties.
Your REALTOR®, mortgage professional and lawyer may each have a part in working through the arrangement.
Lawyer Review Has Its Own Purpose
Legal questions deserve legal advice.
A lawyer can help you understand the agreement and the legal issues associated with the purchase.
Under the standard Nova Scotia APS, lawyer review concerns the wording and content of the agreement, with the lawyers acting reasonably. It has its own deadline and notice provisions. NSREC’s standard purchase agreement
Arrange legal representation early and make sure your lawyer receives the documents promptly.
Also explain anything unusual about your plans for the property.
If your concern is whether you can operate a business, build an addition or use an access route, say so explicitly. Don’t assume another professional knows why that issue is important to you.
Give Yourself Enough Time to Investigate
A short condition period can sound appealing during negotiation.
But the useful question is whether the work can actually be completed.
Before proposing a deadline, consider:
Inspector and specialist availability
Laboratory processing time
Documents your lender still needs
Insurer response times
Your lawyer’s availability
Access to the property
Weekends and holidays
Time to understand the results
For example, having an inspection on the final afternoon may leave very little opportunity to investigate a concern it uncovers.
Build the schedule around the work, including the possibility of follow-up questions.
A deadline should allow time for a decision, not just an appointment.
Use the Condition Period Actively
Once the offer is accepted, begin the agreed work promptly.
Send the purchase documents to your lender and lawyer.
Book inspections.
Contact your insurer.
Request outstanding information.
Keep track of what has arrived and what remains unresolved.
A simple working list can help:
Investigation or document
Person responsible
Expected completion
Outstanding questions
Decision required
This is particularly useful when several professionals are involved. One person’s part may be complete while another is still waiting for information.
Stay involved in the results. The professionals provide information and advice, but you need to understand what you’re being asked to accept.
Being Satisfied and Providing Notice Are Separate Steps
For conditions requiring Form 408, you must provide the completed form to the seller or seller’s representative by the agreed deadline, clearly waiving all applicable conditions.
If that does not happen, the agreement is deemed terminated.
Signing the form without delivering it is not enough. NSREC’s Form 408 guidance
Before authorizing the notice, ask your REALTOR® to explain exactly which conditions it covers.
Make sure your decision reflects the information you have received and any outstanding questions.
Not Every Condition Uses Form 408
The standard lawyer-review, title-investigation and condominium estoppel-certificate clauses use notice of dissatisfaction rather than Form 408.
Other schedules can have their own procedures.
Follow the wording and deadlines in your agreement. NSREC’s explanation of different notice procedures
For practical purposes, avoid treating the purchase as though it has one deadline and one form that settles everything.
Ask for a clear explanation of which steps belong to you, your REALTOR® and your lawyer.
What If You Need More Time or Find a Problem?
You can propose an amendment requesting an extension or another solution. The seller may accept, reject or ignore it, or propose different terms.
Until an amendment is accepted, the original terms and deadline remain in effect. A terminated agreement cannot be revived by amendment. NSREC’s guidance on amendments and deadlines
Raise delays and concerns as soon as they appear.
If you’re waiting for a specialist, make that known while there is still time to consider options.
If an inspection finding changes your view of the purchase, my guide The Inspection Found Problems — What Happens Next? explains the decisions that may follow.
What If You Remain Unsatisfied?
Under the standard buyer-condition process, a buyer who is unsatisfied may terminate before the deadline in accordance with the agreement.
Discuss the appropriate steps with your REALTOR® and obtain legal advice where needed. NSREC’s buyer-condition guidance
Explain the actual concern and the information behind your decision.
Don’t rely on assumptions about what a condition allows, particularly if the wording has been changed or the issue is disputed.
A Terminated Agreement Doesn’t Automatically Release the Deposit
Termination and release of money held in trust are separate matters.
NSREC explains that a brokerage must retain the deposit until it receives the required written mutual direction or a court order authorizing disbursement. This applies even where the funds are not being disputed. NSREC’s deposit guidance
If the purchase ends, ask what documentation is required and who is arranging it.
Understanding that process can prevent confusion about when the money will become available.
Be Careful About Removing a Condition Before You Have Answers
A decision to proceed should reflect what you know and the uncertainty you are prepared to accept.
Before waiving a condition, ask yourself:
Have I received the information I was waiting for?
Do I understand the findings?
Have I spoken with the appropriate professional?
Is there an unresolved issue that could affect my decision?
Am I relying on an assumption that still needs to be checked?
If you feel rushed, explain why.
Perhaps a report has arrived but you haven’t discussed it with the inspector. Perhaps the lender has responded but you don’t understand an outstanding requirement.
Identify the gap before making the decision.
Conditions Work Best When They Lead to Better Information
The purpose of this stage is to understand the purchase more fully.
Can you arrange the financing?
Does the property’s condition work for you?
Can you obtain suitable insurance?
Do the documents raise questions that need answers?
Are there additional investigations appropriate for this home?
A useful condition addresses a real question, allows time to investigate it and provides a clear process for deciding what happens next.
Before you agree to proceed, understand what you have learned—and what you are accepting.
Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Comments:
Post Your Comment: