RSS

Buying Waterfront Property in Nova Scotia: What Should You Investigate?

There's something special about living beside the water.

It might be a cottage overlooking a quiet lake, a home along the Annapolis River, a property beside a tidal inlet, or an oceanfront home with views across the Bay of Fundy.

Waterfront properties can offer privacy, scenery, recreation and a lifestyle that's difficult to duplicate.

But buying waterfront property involves more than evaluating the house and enjoying the view.

The water itself, the surrounding land and the rules governing how the property can be used all deserve careful investigation.

Flooding, shoreline erosion, insurance, building restrictions, septic systems, drinking water and legal access can all affect whether a property is suitable for your plans.

When I'm helping buyers consider waterfront homes in Nova Scotia, I encourage them to look beyond the appearance of the property and understand how it functions throughout the year.

Here are the important areas I recommend investigating before committing to a waterfront purchase.


Not All Waterfront Properties Have the Same Risks

One of the first things to understand is that waterfront properties can be very different depending on the type of water they border.

An oceanfront property may experience tides, storm surge, salt exposure and coastal erosion.

A lakefront property may experience seasonal changes in water levels, shoreline erosion, ice movement or flooding during periods of heavy rainfall.

Riverfront properties may be affected by spring runoff, heavy rain, ice jams and flooding from upstream.

Properties along tidal rivers and estuaries can experience a combination of river flooding and coastal water-level changes.

Even two properties on the same lake or river may have very different risks depending on their elevation, shoreline conditions and surrounding terrain.

Being beside the water doesn't automatically make a property high risk, but it does mean the location deserves more investigation than the view alone.


Is the Property Actually Waterfront?

A listing may describe a property as waterfront, water access or water view.

Those descriptions don't necessarily mean the same thing.

A waterfront property may have direct frontage on the ocean, a lake or a river.

A water-access property might be separated from the shoreline but have a deeded right-of-way or shared access area.

A water-view property may simply overlook the water without any legal right to reach it.

It's important to understand exactly what you're purchasing.

Questions worth investigating include:

  • Does the property legally extend to the shoreline?

  • Is there a road, separate parcel or Crown land between the property and the water?

  • Is access private, shared or provided through a right-of-way?

  • Are there restrictions on using the shoreline?

  • Does an existing dock or wharf belong to the seller?

  • Are there rights or easements benefiting neighbouring properties?

In Nova Scotia, ownership of waterfront land doesn't automatically mean ownership of the submerged land or every part of the shoreline.

Coastal submerged land is generally provincial Crown land unless a recognized exception applies. Inland water boundaries can also involve specific legal considerations.

When waterfront boundaries or access rights are important to a purchase, I encourage buyers to have their lawyer review the title and any relevant surveys or easements.

A licensed land surveyor may also be needed to establish where the property boundaries actually lie.

Never assume that a visible shoreline, pathway or dock is legally included simply because it appears to be part of the property.


Flood Zones and Flood History Should Be Investigated

Flooding is one of the most important considerations when buying waterfront property.

And it isn't limited to oceanfront homes.

River valleys, lakeshores, low-lying land and properties near streams can all experience flooding under certain conditions.

In Nova Scotia, potential causes include:

  • Heavy or prolonged rainfall

  • Rapid snowmelt

  • River overflow

  • Ice jams

  • Storm surge and unusually high tides

  • Blocked drainage systems or culverts

  • Changes in upstream water flow

  • Water collecting in low-lying areas

The Annapolis River and its tributaries are examples of waterways where buyers should consider surrounding terrain and the possibility of high-water events.

Along the Bay of Fundy and other coastal areas, tides and storm surge introduce additional considerations.

One of the first steps is to investigate whether the property is located within a known flood-risk area.

Municipal planning departments may have floodplain information, development restrictions or mapping relevant to a particular location.

For coastal properties, the Nova Scotia Coastal Hazard Map can help buyers investigate potential coastal flooding and erosion risks. However, it does not provide a complete assessment of river or lake flooding.

The absence of a property from a flood map doesn't guarantee that it has never flooded or cannot flood in the future.

Flood mapping has limitations, and not every watercourse or potential flood area has been mapped in the same detail.

I encourage buyers to ask about previous flooding, review available mapping and consider professional advice when the location raises concerns.
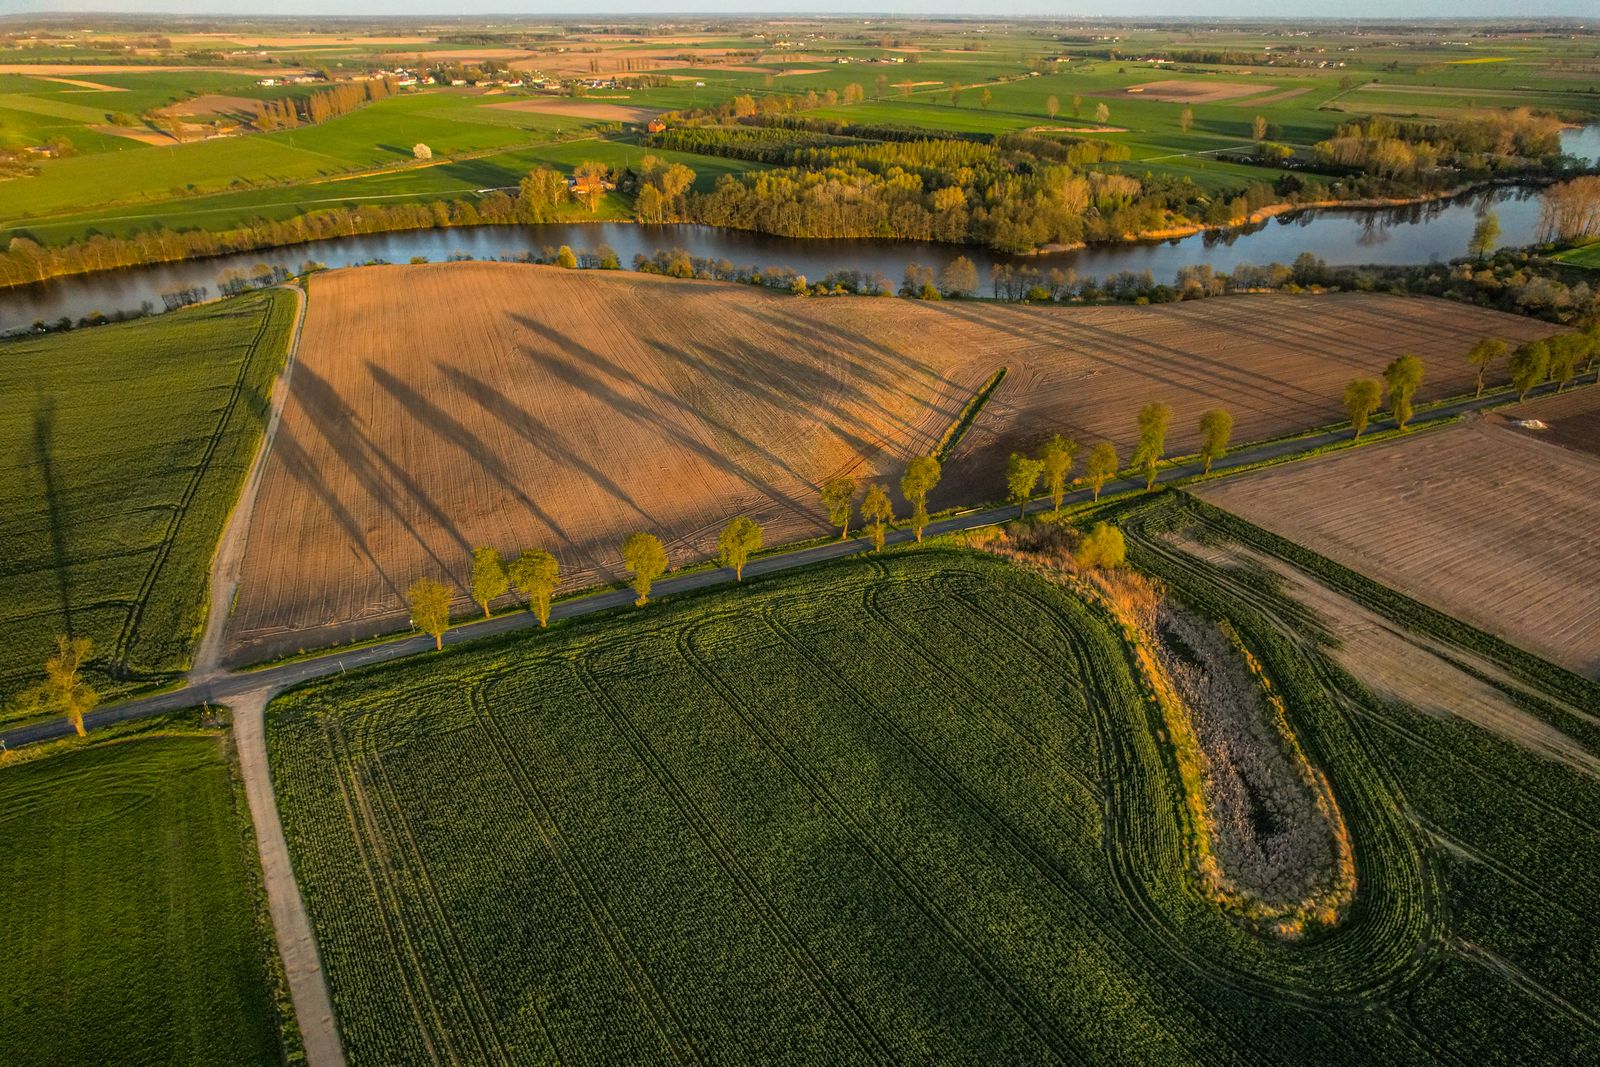
River and low-lying land in the Annapolis Valley

Look for Evidence of Previous Flooding

Maps are useful, but the property itself may also provide important information.

During a viewing, I pay attention to the surrounding land as well as the house.

Potential indicators worth investigating include:

  • Water staining in a basement or crawl space

  • Repeated repairs to lower-level finishes

  • Erosion or deposited debris along the shoreline

  • Drainage channels leading toward the home

  • Low areas where water may collect

  • Sump pumps or drainage systems

  • Evidence of previous shoreline protection work

  • Changes in grading around the foundation

None of these automatically proves that a property has experienced damaging flooding.

A sump pump, for example, may simply be part of an appropriate drainage system.

But these features can justify additional questions.

Ask whether the seller is aware of previous flooding, water intrusion, erosion or insurance claims.

Where appropriate, a home inspector, drainage specialist, engineer or other qualified professional can help assess concerns.

A property that looks dry during a summer viewing may behave very differently during spring runoff or a major rainstorm.


Shoreline Erosion Can Change a Property Over Time

Waterfront land isn't always static.

Waves, currents, ice, storms and changing water levels can gradually alter the shoreline.

Some properties have rocky shorelines that are relatively resistant to erosion.

Others have softer soil, steep banks or exposed areas where erosion may be more noticeable.

This can affect more than the appearance of the property.

Over time, erosion may threaten:

  • Buildings located close to the shoreline

  • Decks, stairs and walkways

  • Driveways and access routes

  • Septic systems

  • Landscaping and retaining structures

  • The amount of usable land

Existing retaining walls, rock protection or other shoreline structures should also be examined.

Their presence doesn't necessarily mean the shoreline is permanently protected.

Repairs or new shoreline protection work may require permits or professional design.

For oceanfront buyers, Nova Scotia provides a Coastal Hazard Map and a property-specific Coastal Hazard Assessment Report service.

These can be useful starting points, but they aren't substitutes for a site-specific professional assessment when erosion is a serious concern.

A beautiful waterfront location today should also be evaluated for how it may change in the years ahead.
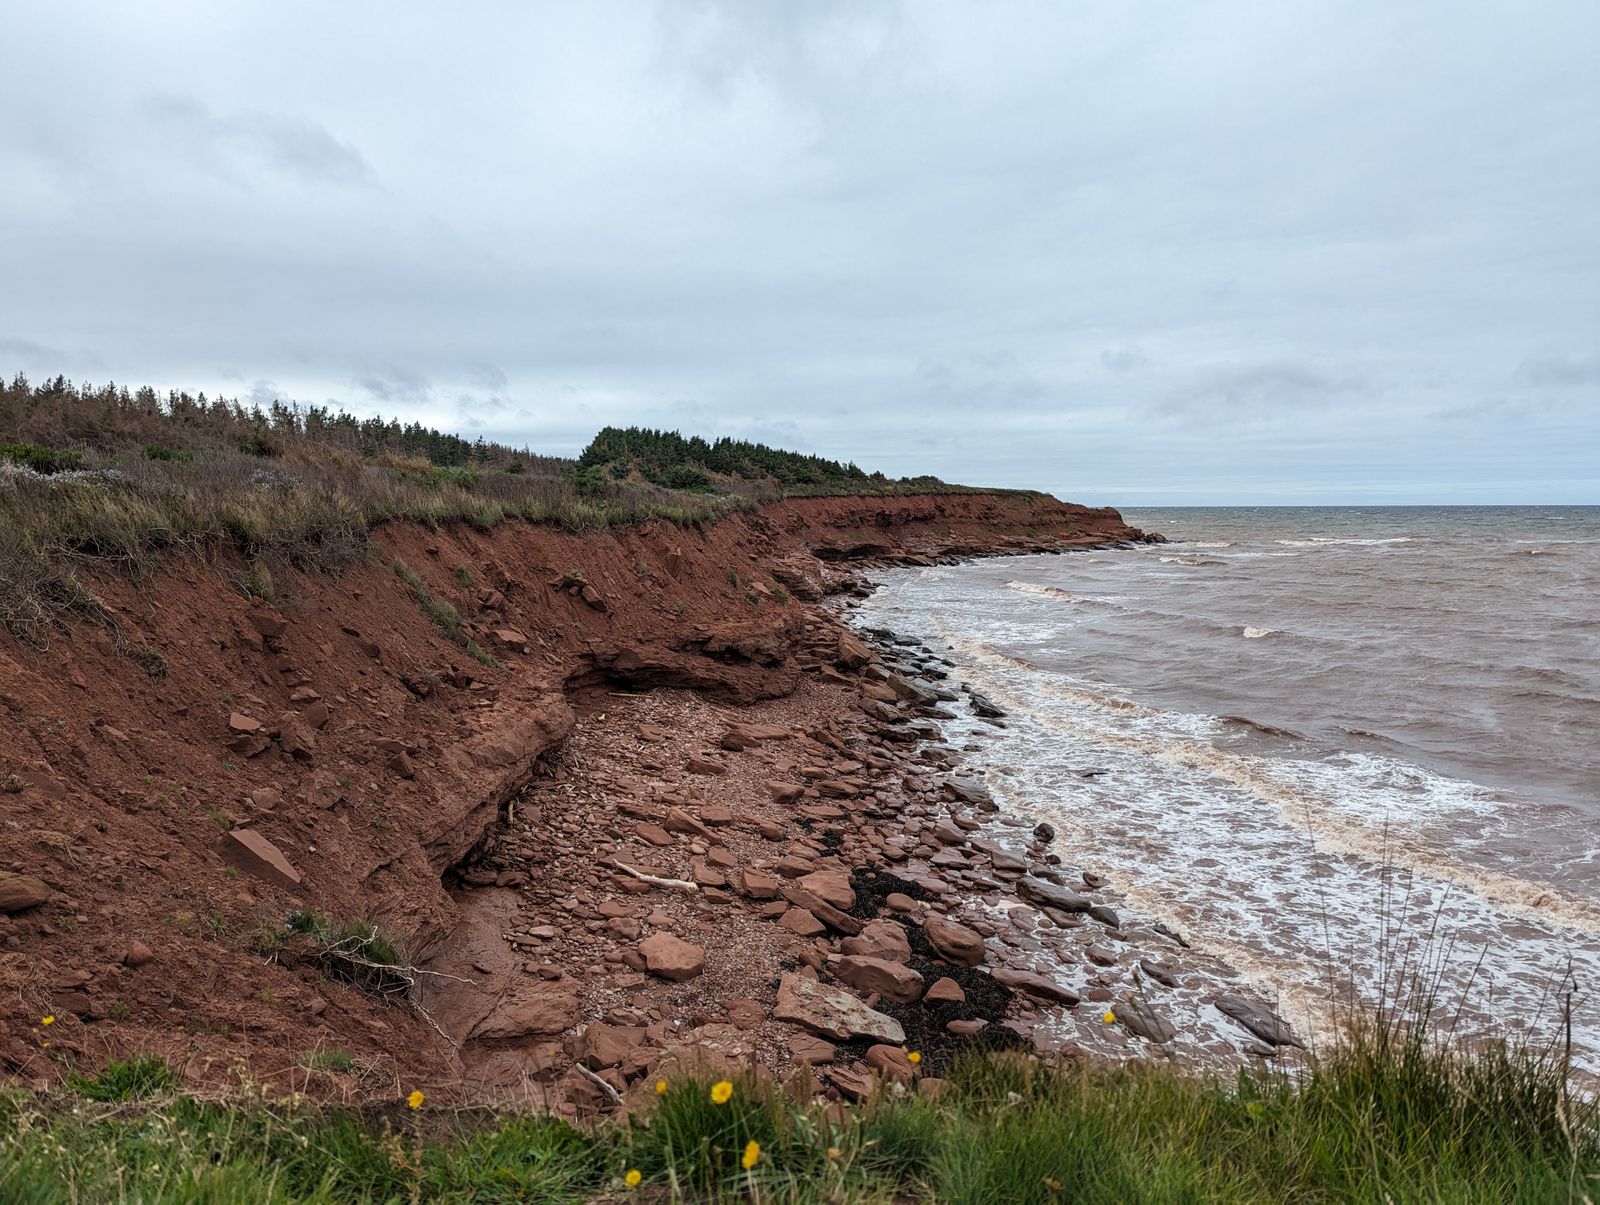
Natural shoreline bank along a Nova Scotia waterfront

Insurance Can Be More Complicated Near Water

Home insurance is another important part of waterfront due diligence.

A standard home insurance policy doesn't necessarily cover every type of water-related damage.

For example, coverage for sewer backup, overland flooding and coastal flooding may be treated differently depending on the insurer and policy.

Some types of coverage may be optional, restricted or unavailable for certain properties.

Insurance companies may consider factors such as:

  • Distance from the shoreline

  • Property elevation

  • Flood history and mapped risk

  • Proximity to rivers or other watercourses

  • Construction type and foundation

  • Whether the property is seasonal or occupied year-round

  • Previous claims

  • Access for emergency services

An insurer may provide coverage for the home while excluding certain flood-related losses.

That distinction matters.

Having home insurance doesn't automatically mean every potential source of waterfront flooding is insured.

I encourage buyers to speak directly with an insurance broker or provider early in their purchase conditions.

Ask specifically what types of water damage are covered, what exclusions apply, whether deductibles differ and whether the insurer has any property-specific requirements.

If you're obtaining a mortgage, the lender will also need to be satisfied with the insurance arrangements.

An insurance problem can therefore become a financing problem.


Check Local Zoning, Building Setbacks and Development Restrictions

One of the biggest mistakes a waterfront buyer can make is assuming that owning the property means they can build wherever they want.

Municipal land-use bylaws may establish restrictions involving:

  • Minimum setbacks from shorelines or watercourses

  • Building setbacks from property boundaries

  • Minimum lot sizes

  • Building height and permitted uses

  • Development within floodplains

  • Construction on steep slopes

  • Accessory buildings, garages and boathouses

  • Renovations or expansions of existing buildings

  • Subdivision of waterfront land

Requirements vary by municipality, zoning designation and property.

A setback is generally the minimum required distance between a building or development and a specified boundary or feature.

On a waterfront lot, that feature may include a shoreline, watercourse or wetland.

A property may have a substantial amount of land on paper but a much smaller area where construction is permitted.

This is particularly important when buying vacant waterfront land or a cottage you hope to expand.

An existing building close to the water may also be subject to rules that limit reconstruction or expansion.

The fact that a building already exists doesn't automatically mean you can enlarge it, replace it in the same location or rebuild it after major damage.

Before relying on future development plans, I encourage buyers to contact the municipality's planning or development department and obtain property-specific guidance.

Depending on the proposed work, provincial or federal requirements may also apply.


Can You Build a Dock, Wharf or Shoreline Structure?

A dock can be a major attraction when purchasing waterfront property.

But installing or replacing one isn't always as straightforward as it appears.

Different rules may apply to:

  • Floating docks

  • Permanent docks and wharves

  • Boat launches

  • Shoreline stairs and access structures

  • Retaining walls and erosion protection

  • Dredging or shoreline excavation

  • Culverts and watercourse crossings

In Nova Scotia, alterations to the bed or bank of a watercourse, or to water flow, may require a provincial notification or approval.

Buyers planning shoreline work should review the Nova Scotia watercourse alteration requirements to understand when provincial authorization may be necessary.

Work involving submerged Crown land may require separate authorization.

Federal requirements may also apply to certain projects affecting navigation or fish habitat.

The exact requirements depend on the location and type of work.

If a property already has a dock, ask whether permits or other authorizations were required and obtained.

If you intend to install one, investigate the requirements before purchasing.

Don't assume that because neighbouring properties have docks, you will automatically be permitted to build one.
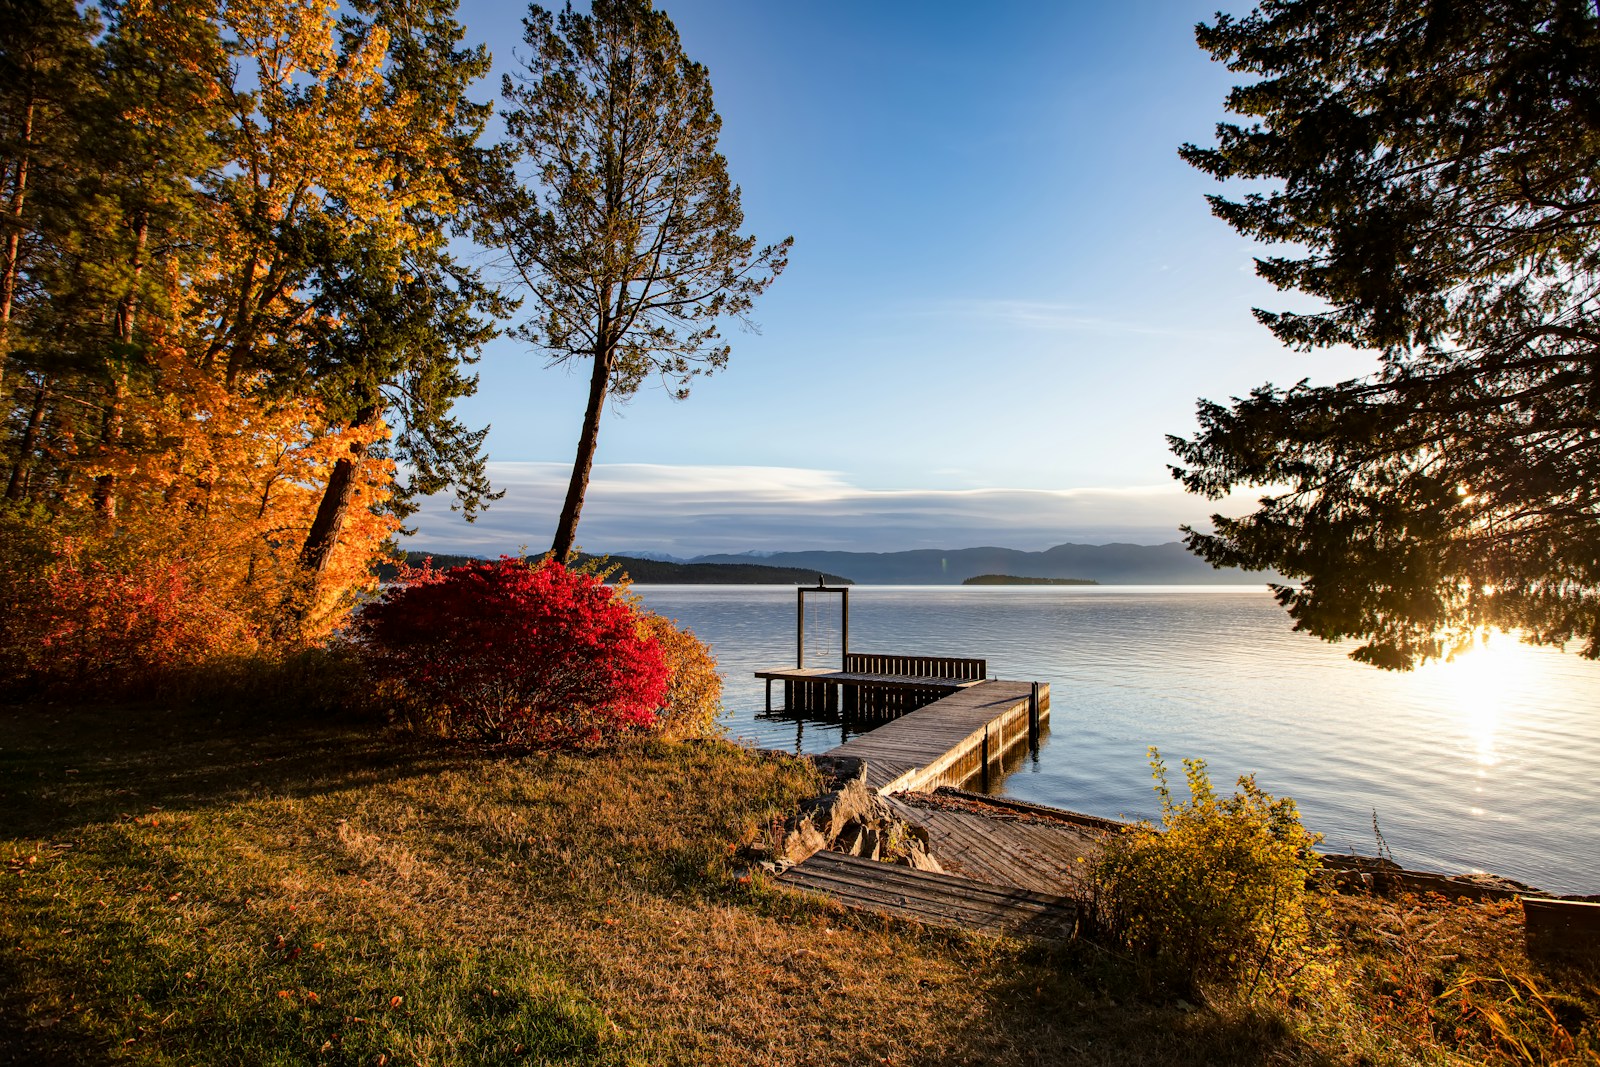
Small wooden dock extending into a Nova Scotia lake

Wetlands and Environmentally Sensitive Areas Can Affect Your Plans

Not every part of a waterfront property is suitable for development.

Some lots include wetlands, marshes, seasonal drainage areas or other environmentally sensitive features.

These areas can play an important role in water filtration, wildlife habitat and floodwater storage.

They may also be subject to restrictions on filling, draining, excavation or construction.

A wet area that appears insignificant during a dry summer may be part of a larger wetland or drainage system.

If you're purchasing land with the intention of building, clearing or landscaping near the water, it's important to establish whether protected or regulated features are present.

A municipality, Nova Scotia Environment and Climate Change, or a qualified environmental professional may need to be consulted.


Septic Systems Deserve Special Attention on Waterfront Properties

Many waterfront homes and cottages in Nova Scotia use private septic systems.

Their location and condition can be especially important when the property is close to a lake, river or ocean.

A septic system generally includes a tank and a disposal area that treats wastewater through the surrounding soil.

Waterfront lots may present challenges involving:

  • Limited space between the house and shoreline

  • High groundwater

  • Shallow soil or bedrock

  • Poor drainage

  • Steep terrain

  • Older or undocumented systems

  • Difficulty locating a suitable replacement area

A system that appears to be functioning today may still create problems if it needs to be replaced.

For example, a small waterfront lot may have limited room for a new disposal field that meets current requirements.

That's why I encourage buyers to investigate not only the condition of the existing system but also its location and available documentation.

A septic inspection can help identify concerns, but it doesn't automatically establish that a replacement system could be installed in the same location.

If the septic system fails in the future, where could a replacement system go?

That question is particularly important for small waterfront lots.


Investigate the Well and Drinking Water Supply

A waterfront location doesn't guarantee a reliable or safe drinking water supply.

Many Nova Scotia waterfront properties rely on private wells.

Others, particularly older cottages, may draw water from a lake, river, spring or another surface-water source.

It's important to establish exactly where the household water comes from.

Private wells

Water testing is an important part of investigating a private drinking water supply.

Nova Scotia recommends testing private well water for bacteria every 6 months and chemical contaminants at least every five years. More frequent testing may be appropriate depending on the well's condition or potential contamination risks. Buyers can review Nova Scotia's well water testing recommendations for guidance on testing and interpreting results.

A satisfactory water test provides information about the sample collected at that time. It does not guarantee that water quality or quantity will remain unchanged.

For a drilled or dug well, buyers should investigate:

  • The type and location of the well

  • Available well records

  • Water quantity and recovery

  • Bacterial water quality

  • Chemical water quality

  • Proximity to septic systems and potential contamination sources

  • Whether the well has experienced shortages

  • Whether treatment equipment is installed

Waterfront properties can have additional concerns where groundwater interacts with nearby surface water.

Low-lying areas may also be more vulnerable to contamination during flooding.

Along coastal properties, saltwater intrusion can sometimes affect groundwater supplies.

Testing for chloride and related indicators may be appropriate where saltwater intrusion is suspected.

In Nova Scotia, naturally occurring substances such as arsenic, uranium and manganese are also important considerations for private well owners.

Lake, river or spring water

Some cottages use water drawn directly from a lake, river or spring.

This should not be treated as equivalent to a properly constructed private well.

Surface water can contain bacteria, parasites and other contaminants, even when it looks clear.

A surface-water supply intended for household drinking water generally requires appropriate filtration, disinfection, testing and ongoing maintenance.

The source may also be affected by seasonal water levels, drought or freezing.

When I'm helping buyers consider a property with an unconventional water supply, I encourage them to involve a qualified water-treatment professional and confirm that the system can reliably provide water suitable for its intended use.

Being surrounded by water doesn't mean you have an adequate supply of safe drinking water.
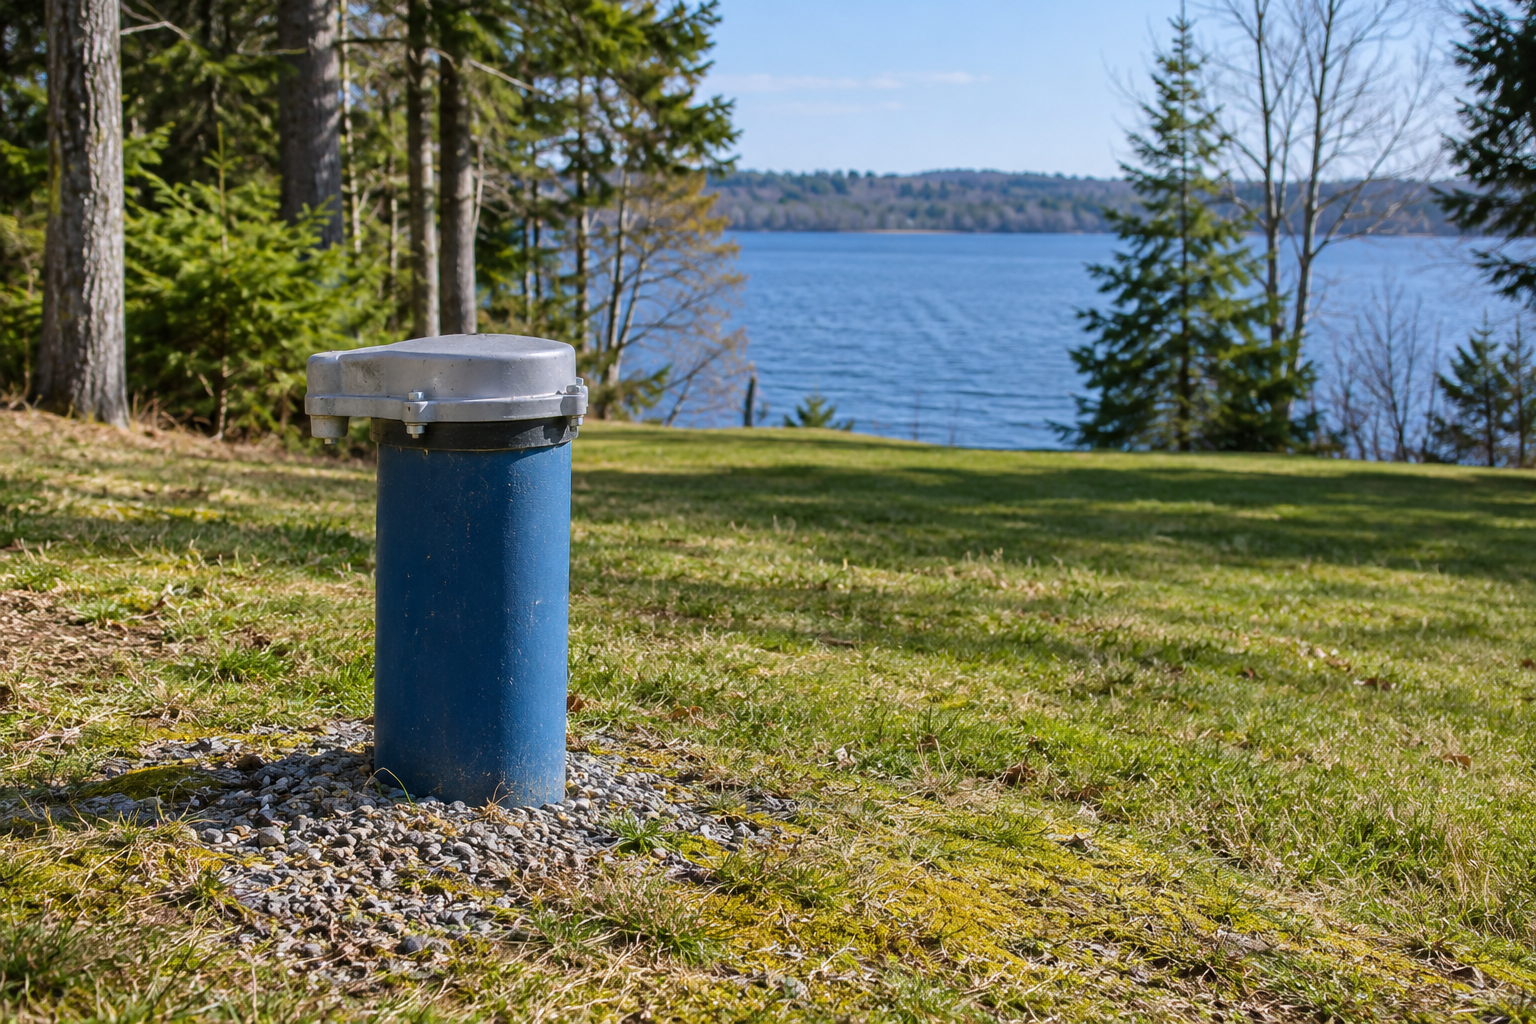
Private drilled well on a waterfront residential property

Is the Property Accessible Year-Round?

Some of Nova Scotia's most attractive waterfront properties are located along private roads or seasonal access routes.

That can be part of their appeal, but it also deserves investigation.

Questions include:

  • Is the road publicly maintained or privately owned?

  • Who is responsible for grading, repairs and snow removal?

  • Is there a formal road maintenance agreement?

  • Are there annual fees?

  • Is access legally registered?

  • Can emergency vehicles reach the property?

  • Is the road vulnerable to flooding or washouts?

  • Are bridges or culverts maintained?

  • Can the property be accessed during winter?

A cottage that is easy to reach in July may be more challenging during a February snowstorm.

If you plan to live there year-round, reliable access becomes particularly important.

Road conditions and legal access can also affect insurance and financing.


Understand Seasonal Water Levels and Recreational Use

Waterfront properties often look their best during the summer.

But water levels can change significantly throughout the year.

On lakes and rivers, spring runoff and heavy rainfall can raise water levels.

During dry periods, water may recede, exposing mud, rocks or shallow areas.

On tidal waterfront, the shoreline may look completely different at high tide and low tide.

This is especially noticeable around the Bay of Fundy.

If swimming, boating or fishing is important to you, investigate the actual conditions.

Consider:

  • Water depth near the shore

  • Rocky, muddy or sandy bottom conditions

  • Currents and tidal movement

  • Seasonal weeds or aquatic vegetation

  • Water quality and swimming advisories

  • Boat access at different water levels

  • Whether the water is suitable for the type of boat you intend to use

  • Winter ice conditions

  • Nearby recreational activity and noise

A property with a beautiful view may not provide the swimming or boating experience you expect.

When possible, I encourage buyers to see the shoreline under different conditions rather than relying entirely on listing photographs.


Existing Buildings and Cottages May Have Additional Limitations

Many older homes and waterfront cottages were built decades ago, sometimes under different building standards or planning requirements.

Some were originally designed for seasonal use and later converted for year-round living.

That history can raise questions involving:

  • Insulation and heating

  • Foundation construction

  • Plumbing and freeze protection

  • Electrical systems

  • Septic capacity

  • Permits for additions or renovations

  • Legal use and occupancy

  • Insurance eligibility

  • Mortgage financing

An attractive renovated cottage isn't automatically suitable for year-round use.

If you're planning to convert a seasonal cottage into a permanent residence, investigate the building, services and applicable municipal requirements before assuming that conversion is possible.


Consider Ongoing Maintenance and Long-Term Costs

Waterfront ownership may involve maintenance that isn't typical of an inland property.

Depending on the location, this could include:

  • Shoreline vegetation management

  • Dock removal and installation

  • Maintaining shoreline stairs or walkways

  • Erosion monitoring

  • Drainage and culvert maintenance

  • Salt-related corrosion

  • Repairs to private roads

  • Maintaining water-treatment equipment

  • Septic system maintenance

  • Higher or more specialized insurance costs

Not every waterfront property will have these expenses.

However, buyers should understand which responsibilities apply to the property they're considering.

A relatively inexpensive cottage can become costly if major shoreline, access or infrastructure work is required.


Questions to Ask Before Buying Waterfront Property

Before removing your purchase conditions, I encourage buyers to work through questions such as these:

  1. Does the property legally include waterfront frontage, or is access shared or provided through an easement?

  2. Are the boundaries and shoreline ownership clear?

  3. Has the property experienced flooding, erosion or water intrusion?

  4. Is it within a mapped flood-risk or coastal hazard area?

  5. What flood-related losses are covered or excluded by insurance?

  6. Are there municipal shoreline setbacks or restrictions on construction?

  7. Can existing buildings legally be expanded or replaced?

  8. Are permits required for a dock, wharf, retaining wall or shoreline work?

  9. Are there wetlands or other regulated environmental features?

  10. Where are the septic tank and disposal field located, and is there room for a replacement system?

  11. What is the drinking water source, and has it been properly tested?

  12. Is there reliable legal and physical access throughout the year?

  13. How do seasonal water levels affect the shoreline and recreational use?

  14. Are existing structures and improvements properly authorized?

  15. Are there ongoing maintenance costs or responsibilities that aren't immediately obvious?

Not every property will require the same level of investigation.

A modern year-round home on a large lakefront lot may present different concerns from an older cottage on a narrow tidal shoreline.

The goal is to identify the questions that matter for the specific property.
Buyer and real estate professional examining a waterfront property

Waterfront Living Can Be Wonderful — When You Understand What You're Buying

Waterfront property can offer an exceptional lifestyle.

Whether you're looking for a lakefront cottage, a riverfront home in the Annapolis Valley or a property overlooking the Bay of Fundy, the setting may be one of the biggest reasons you're interested.

But the most important details aren't always visible during a showing.

Flood exposure, erosion, legal boundaries, insurance, drinking water, septic systems and development restrictions can all affect how you use and maintain the property.

When I'm helping buyers explore waterfront properties in Nova Scotia, I encourage them to investigate these issues early and involve the appropriate professionals when additional information is needed.

A waterfront property doesn't need to be free of every potential concern. You need to understand the risks, restrictions and responsibilities before deciding whether it's the right property for you.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.

Read

Your Mortgage Is Pre-Approved — So Why Can Financing Still Fall Through?

You've spoken with a mortgage broker or bank, provided your financial information and received a mortgage pre-approval.

You know approximately how much you can borrow, you've established a budget, and you're ready to start looking at homes.

Then you find a property you love.

Your offer is accepted, and everything seems to be moving in the right direction.

So why would financing still be a concern?

Because a mortgage pre-approval is not the same as final mortgage approval for the home you're purchasing.

A lender needs to approve both your ability to repay the mortgage and the property being used as security for the loan.

Even after an offer is accepted, there may be outstanding requirements involving an appraisal, income verification, the down payment, property insurance or the home's condition.

Understanding these differences can help you avoid an unexpected financing problem during your purchase.


What Does a Mortgage Pre-Approval Actually Mean?

A mortgage pre-approval is an important starting point when buying a home.

Depending on the lender and the type of pre-approval, it may involve reviewing your income, debts, credit history, available down payment and other financial information.

It can help establish:

  • Approximately how much you may qualify to borrow

  • An estimated mortgage payment

  • The mortgage rate or rate hold available to you

  • A realistic starting budget for your home search

Some pre-approvals involve a detailed review of supporting documents, while others are more preliminary.

That's an important distinction.

A pre-approval based largely on information you've provided may still require substantial verification before the lender makes a final decision.

Even a thoroughly reviewed pre-approval is generally subject to additional conditions.

Being pre-approved means you're in a better position to start shopping. It doesn't mean every property within your price range will qualify for financing.


The Lender Must Also Approve the Property

This is one of the most important parts of mortgage financing that buyers sometimes overlook.

You might qualify financially to purchase a $400,000 home.

But that doesn't automatically mean a lender will approve a mortgage on every property selling for $400,000.

The lender also needs to be satisfied with the property securing the mortgage.

That assessment may consider:

  • The property's market value

  • Its condition and construction

  • Its location

  • Whether it is suitable for year-round residential use

  • The property type and intended occupancy

  • Whether acceptable insurance can be obtained

  • Whether it meets the lender's or mortgage insurer's requirements

This becomes particularly relevant in Nova Scotia, where buyers encounter a wide range of properties.

A conventional home in a subdivision may present different lending considerations from a century-old farmhouse, seasonal cottage, manufactured home or unusually constructed rural property.

When I'm helping buyers evaluate a property that has unusual features, I encourage them to discuss those details with their mortgage professional before making assumptions about financing.

A property can be attractive, well maintained and reasonably priced without necessarily meeting every lender's requirements.


What Happens If the Appraisal Comes in Too Low?

One of the most common concerns after an accepted offer is the property appraisal.

A lender may require an appraisal or another form of valuation to determine whether the property's value supports the proposed mortgage.

An appraisal is not the same as a home inspection.

The appraiser's primary purpose is to assess the property's market value for the lender, not to provide a comprehensive evaluation of its condition.

And the agreed purchase price isn't automatically the appraised value.

For example, imagine you agree to purchase a home for $400,000.

You plan to provide a 20% down payment of $80,000 and borrow $320,000.

But the lender's appraisal comes back at $375,000.

If the lender will finance only 80% of the appraised value, the maximum mortgage would be $300,000 instead of $320,000.

That means you would need an additional $20,000 to complete the purchase, bringing your total required contribution to $100,000.

You would need to find an acceptable way to address that difference, such as contributing additional funds or negotiating a different purchase price if the seller agrees.

This is a simplified example. Actual financing depends on the lender, mortgage product, down payment and any applicable mortgage insurance requirements.

An appraisal shortfall doesn't automatically end a purchase, but it can change how much money you need to complete it.

Property appraiser assessing the exterior of a residential home

Rural and Unusual Properties Can Require More Investigation

The Annapolis Valley has many properties that don't fit neatly into the typical suburban-home category.

You may find homes with extensive acreage, hobby farms, converted buildings, unusual construction or multiple outbuildings.

Some properties have been expanded or renovated over many years.

Others may have a main residence alongside agricultural buildings or structures that contribute to the property's asking price.

A lender may assess these features differently from a buyer.

For example, a buyer may see considerable value in a large workshop, barn or additional acreage.

The lender may place less value on some of those features when determining how much it is prepared to finance.

Other considerations can include whether the property is accessible year-round, whether it is primarily residential, and whether comparable sales are available to support the valuation.

This doesn't mean unusual properties cannot be financed.

It means some may require a more specialized lender, additional documentation or a different financing structure.

When I'm helping buyers consider rural acreage or an unconventional home, I encourage them to provide the property details to their mortgage professional as early as possible.

The property's uniqueness may be exactly what makes it appealing to you, but it can also require additional attention from the lender.

Rural Annapolis Valley home with acreage and outbuildings

Older Homes and Property Condition Can Affect Financing

Nova Scotia has many older homes that are more than 100 years old.

Some have been extensively renovated, while others still contain older heating, electrical, plumbing or structural components.

Age alone doesn't automatically prevent mortgage approval.

However, lenders and mortgage insurers may have requirements concerning the property's condition and suitability.

Potential concerns could include:

  • Significant structural deterioration

  • An unsafe or inadequate heating system

  • Major roof problems

  • Serious water damage

  • Unfinished or incomplete construction

  • A property that isn't suitable for its intended residential use

  • Conditions that prevent acceptable property insurance

A lender might request further information, require an appraisal, or impose conditions that must be addressed before funds are advanced.

In some cases, a property may need repairs that the buyer or seller isn't prepared to complete.

This is one reason I encourage buyers to consider their home inspection findings alongside their financing and insurance requirements.

A home inspector, mortgage lender and insurance company are evaluating different aspects of the same property. An acceptable result from one doesn't guarantee acceptance by the others.

Older Nova Scotia home with traditional wooden construction

Home Insurance Can Become a Financing Problem

Home insurance is closely connected to mortgage financing.

Most lenders require acceptable property insurance before advancing mortgage funds.

If an insurance company refuses coverage, requires major repairs or imposes restrictions that don't meet the lender's requirements, financing may be affected.

This is particularly important when buying a property with:

  • An older oil tank

  • A wood stove, fireplace or wood-fired furnace

  • Older electrical systems

  • A deteriorated roof

  • A history of water damage

  • Unusual construction

  • Seasonal or vacant occupancy

Some homes over 100 years old may also require additional insurance investigation.

The insurance company determines whether it will provide coverage, while the lender determines whether that coverage meets its requirements.

When I'm helping buyers purchase older or rural homes, I encourage them to investigate insurance during their purchase conditions rather than waiting until closing approaches.

A mortgage approval may still depend on obtaining acceptable insurance for the property.


Changes to Your Employment or Income Can Affect Approval

Mortgage pre-approval is based on your financial circumstances at the time of the review.

If those circumstances change, your financing may need to be reassessed.

For example:

  • You change employers

  • You leave a salaried position to become self-employed

  • Your hours are reduced

  • Your employment becomes temporary or seasonal

  • You lose your job

  • A significant portion of your expected income can no longer be verified

Even a positive career change can create complications.

A new job with a higher salary may sound like good news, but the lender may want additional documentation or confirmation of employment terms.

If you're relocating to Nova Scotia, this can be especially important.

Perhaps you've been pre-approved based on your current employment in another province, but you plan to leave that position when you move.

The lender needs to understand how your income will continue after the relocation.

For military buyers, employment may be more straightforward, but posting-related documentation and the timing of the move can still be relevant.

Before changing jobs or making a significant employment decision, speak with your mortgage professional about how it could affect your approval.


Taking on New Debt Before Closing Can Create Problems

After receiving a pre-approval, it may be tempting to make purchases for your new home.

A new vehicle, furniture, appliances or a line of credit might seem manageable within your budget.

But taking on additional debt can change the financial picture the lender originally reviewed.

Mortgage qualification considers more than income.

It also considers your existing financial obligations.

A new car payment, increased credit card balance or additional loan may affect the amount you're eligible to borrow.

Even applying for new credit can introduce questions that need to be reviewed.

The safest approach is to avoid significant new borrowing or financial commitments until your purchase has closed, unless you've discussed them with your mortgage professional.

Being pre-approved for a mortgage isn't a reason to make large purchases before you receive the keys.


Your Down Payment Must Be Verified

Having enough money for the down payment is only part of the requirement.

The lender may also need to verify where the funds came from and confirm that they're available.

Depending on the circumstances, this could involve:

  • Bank or investment statements

  • Records showing funds transferred between accounts

  • Documentation of proceeds from another property sale

  • A gift letter and supporting information

  • Evidence of other approved down payment sources

Large deposits or unexplained transfers may lead to additional questions.

For example, if a family member is contributing money toward your down payment, the lender may need to establish whether it is a genuine gift or a loan that must be repaid.

That distinction can affect qualification.

Moving funds between accounts isn't necessarily a problem, but it may create additional documentation requirements.

If you're planning to use gifted funds, investments or proceeds from another sale, discuss the arrangements with your mortgage professional early.

The lender needs to be satisfied not only that you have the money, but also that its source meets the applicable requirements.

Homebuyer reviewing financial records for mortgage down payment verification

Don't Forget About Closing Costs

A mortgage pre-approval doesn't mean the lender will finance every expense associated with purchasing a home.

You'll also need to account for closing costs.

In Nova Scotia, these may include:

  • Legal fees and disbursements

  • Deed transfer tax, where applicable

  • Property tax adjustments

  • Appraisal costs, if charged to the buyer

  • Inspection costs

  • Other transaction-related expenses

The amount will depend on the municipality, property, financing arrangements and your individual circumstances.

If you're moving from another province, remember that relocation and moving expenses may also require a substantial amount of money.

Some buyers have enough saved for the down payment but haven't allowed sufficient funds for closing.

Your lender may require evidence that these additional funds are available.

When I'm helping buyers plan their purchase, I encourage them to understand the full financial commitment rather than focusing only on the down payment and monthly mortgage payment.


A Mortgage Rate Hold Has an Expiry Date

Some pre-approvals include an interest rate hold for a specified period.

That can be helpful when you're searching for a home.

However, the rate hold and the mortgage approval are not the same thing.

A rate hold may expire before you find a property or before your transaction is completed.

The lender may also have specific requirements concerning the mortgage product, closing date and circumstances under which the rate can be used.

If interest rates or qualification requirements change, your available options may be different when the original arrangement expires.

Ask your mortgage professional how long your pre-approval and any rate hold remain valid, and what happens if your purchase takes longer than expected.


Why the Financing Condition in Your Offer Matters

In Nova Scotia, an accepted Agreement of Purchase and Sale may include a financing condition.

This gives the buyer an agreed period to investigate whether satisfactory financing can be arranged, according to the terms of the agreement.

It's an important protection because a pre-approval doesn't confirm that the lender will finance the particular property.

During the conditions period, the mortgage professional may need to submit the accepted agreement, verify documents, arrange a property valuation and obtain a lending decision.

The exact process varies by lender and transaction.

The financing condition has a deadline.

Under Nova Scotia's standard buyer-condition process, a buyer who is satisfied with the applicable conditions provides the required written waiver using Form 408 within the agreed timeframe.

If the buyer isn't satisfied, the agreement and the applicable condition provisions determine the next steps.

An extension or amendment may be proposed, but the seller isn't automatically required to agree.

A verbal assurance that financing looks good isn't the same as confirming that all important lending requirements have been addressed.

When I'm helping buyers through the conditions period, I keep track of the deadlines, coordinate the real estate documentation and encourage direct confirmation with their mortgage professional before they make a final decision.

Homebuyer and real estate professional reviewing purchase conditions

What Does “Approved Subject to Conditions” Mean?

You may hear that your mortgage has been approved, but that the approval is still subject to certain requirements.

This is common.

Those conditions could involve:

  • A satisfactory appraisal

  • Updated income verification

  • Confirmation of down payment funds

  • Proof of property insurance

  • Additional documentation

  • Mortgage insurer approval, where required

  • Final lender instructions and other funding requirements

Not all outstanding conditions carry the same level of risk.

Some may be routine administrative items.

Others, such as an incomplete appraisal or unresolved property concern, could materially affect whether the mortgage proceeds.

Before waiving a financing condition, ask your mortgage professional which requirements remain outstanding and whether any could still prevent funding.

The important question isn't simply “Am I approved?” It's “What still needs to happen before the lender will release the money?”


Can Financing Fall Through After Conditions Are Waived?

Yes.

This is a distinction buyers need to understand.

Even after a lender has approved the mortgage and the buyer has waived the financing condition, circumstances can arise that affect funding.

For example, the lender may discover a significant change in income, new debt, an issue with down payment verification or an unresolved requirement concerning the property.

A buyer who has already waived the applicable purchase conditions may no longer have the same contractual protection if financing fails.

That can create serious consequences.

Depending on the agreement and circumstances, the buyer may be unable to complete the purchase and could face financial or legal liability.

A deposit isn't necessarily the limit of a buyer's potential exposure.

This is why I encourage buyers to maintain stable financial circumstances between mortgage approval and closing, and to respond promptly to requests from their mortgage professional and lawyer.

Don't treat the financing process as finished until the mortgage funds are available for closing.


What Should You Do If Financing Is Delayed or Declined?

First, find out exactly what the problem is.

A financing delay doesn't always mean the lender has declined the application.

Perhaps the lender is waiting for an appraisal, updated employment confirmation or another document.

If financing is declined, ask your mortgage professional to explain the reason and whether alternatives are available.

Depending on the circumstances, possibilities may include:

  • Providing additional documentation

  • Considering another lender

  • Adjusting the mortgage amount

  • Increasing the down payment, if feasible

  • Reviewing a different financing product

  • Investigating whether a property concern can be resolved

  • Discussing a proposed amendment to the purchase agreement

Not every alternative will be practical, and some may involve additional costs or risks.

Timing is especially important. If the financing condition deadline is approaching, it's essential to understand your options before that deadline passes.

As I explain in my article, The Inspection Found Problems — What Happens Next?, understanding your purchase conditions and their deadlines is an important part of protecting your interests during the buying process.

When I'm helping buyers navigate financing difficulties, I work with them to understand where the transaction stands, communicate with the seller's representative when appropriate, and address any proposed changes through the proper agreement process.

The mortgage professional handles the financing options, while a lawyer can advise on legal obligations and consequences.

The earlier a financing problem is identified, the more opportunity there may be to investigate a solution.


Questions to Ask Before Waiving Your Financing Condition

Before making your final decision, consider asking your mortgage broker or lender:

  1. Has the lender approved my application for this specific property?

  2. Has the property valuation been completed or accepted?

  3. Are there any concerns about the property's condition, construction, location or intended use?

  4. Is mortgage insurer approval required, and has it been obtained?

  5. Have my income, employment, credit and down payment been adequately verified?

  6. Are there any outstanding requirements that could change the mortgage amount or prevent funding?

  7. Is acceptable property insurance required, and have the lender's requirements been confirmed?

  8. What documents or steps remain before closing?

  9. Are there any financial changes I should avoid before the mortgage funds are advanced?

  10. Is there anything about this transaction that needs further review before my financing condition deadline?

Your mortgage professional is best positioned to explain the status of the application and any remaining lending requirements.


A Pre-Approval Is the Beginning, Not the End

Getting pre-approved is one of the best steps you can take before starting your home search.

It helps you establish a realistic budget and gives you a clearer understanding of your borrowing options.

But a pre-approval is only one stage of the financing process.

The lender still needs to be satisfied with the property, the supporting documentation and any outstanding conditions.

For buyers considering older homes, rural acreage, unusual construction or properties requiring repairs, additional investigation may be especially important.

When I'm helping buyers purchase a home in the Annapolis Valley or elsewhere in Nova Scotia, I encourage them to involve their mortgage professional early, understand the financing condition and avoid making major financial changes before closing.

The goal isn't to make the process complicated.

It's to identify potential problems while there's still time to address them.

A mortgage pre-approval gives you a place to start. Confirmed financing for the property you're buying is what helps you move toward closing with confidence.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.
Read

Home Insurance When Buying in Nova Scotia: What Can Cause Problems?

Buying a home involves more than finding the right property, arranging a mortgage and completing inspections.

You also need to know whether you can insure it.

For many buyers, home insurance seems like a straightforward final step. They expect to contact an insurance company, provide the property details, receive a quote and arrange coverage for closing.

Often, that's exactly what happens.

But some homes raise questions that aren't immediately obvious during a showing.

A home that's more than 100 years old, an aging oil tank, a wood stove, certain electrical systems, a deteriorating roof or even the property's location can affect the insurance available.

And if you're buying with a mortgage, an insurance problem can become a financing problem.

The time to discover an insurance concern is while you're investigating the property—not a few days before closing.


Why Home Insurance Matters Before Closing

Most mortgage lenders require acceptable property insurance before they will advance funds for a home purchase.

The insurance generally needs to be in place for the closing date and meet the lender's requirements.

If an insurer declines the property, requires work that cannot be completed in time, or offers coverage that doesn't satisfy the lender, closing could be affected.

Even when buying without a mortgage, appropriate insurance is an important part of protecting what may be one of your largest investments.

A common misconception is that if a home passes its inspection, obtaining insurance should be automatic.

It isn't.

A home inspection evaluates the visible condition of the property and its systems.

An insurance company assesses the risks it is prepared to insure, using its own underwriting requirements.

Those assessments can produce different conclusions about the same property.


An Insurance Quote Isn't Always Final Approval

There is an important difference between receiving an estimated premium and having an insurance company confirm that it will issue a policy.

An initial quote may be based on information you provide about the property.

The insurer may subsequently ask for photographs, inspection reports, details about heating systems, or confirmation of previous improvements.

In some situations, an insurer may require work before coverage begins or impose conditions that must be satisfied afterward.

A quote may also change if new information becomes available.

Before removing your purchase conditions, ask whether the insurer has sufficient information to accept the property and whether any outstanding requirements could affect coverage.

Knowing the estimated annual premium is useful. Knowing the home can actually be insured is more important.


Homes Over 100 Years Old Can Be More Difficult to Insure

Nova Scotia has an abundance of older homes, including many that are more than 100 years old.

These properties can offer beautiful architectural details, craftsmanship and character that are difficult to find in newer construction.

However, the age of a home can sometimes create additional challenges when arranging insurance.

Some insurance companies have specific underwriting guidelines for older properties, particularly homes that are 100 years old or more.

That doesn't mean these homes are uninsurable.

It does mean that insurers may want more information before agreeing to provide coverage.

They may ask about:

  • The age of the home and its construction

  • Whether the electrical system has been updated

  • The condition and age of the plumbing

  • The type and age of the heating system

  • When the roof was last replaced

  • Whether major renovations or structural improvements have been completed

  • Whether original building materials or unusual construction methods could make repairs more complicated

One important distinction is that the age of the home and the age of its major systems are not necessarily the same thing.

A home built in 1890 may have modern wiring, updated plumbing, a newer roof and a recently installed heating system.

Another home of the same age may still contain several original or outdated components.

Those two properties could be viewed quite differently by an insurance company.

Some insurers may decline older homes based on their underwriting guidelines, while others may offer coverage after reviewing the property's condition and improvements.

When I'm helping buyers consider a century home, I encourage them to contact their insurance provider early and provide as much information as possible about renovations and major system upgrades.

A home's age shouldn't automatically discourage you from buying it, but it should be part of your insurance investigation before you commit to the purchase.

Architectural details of an older Nova Scotia home

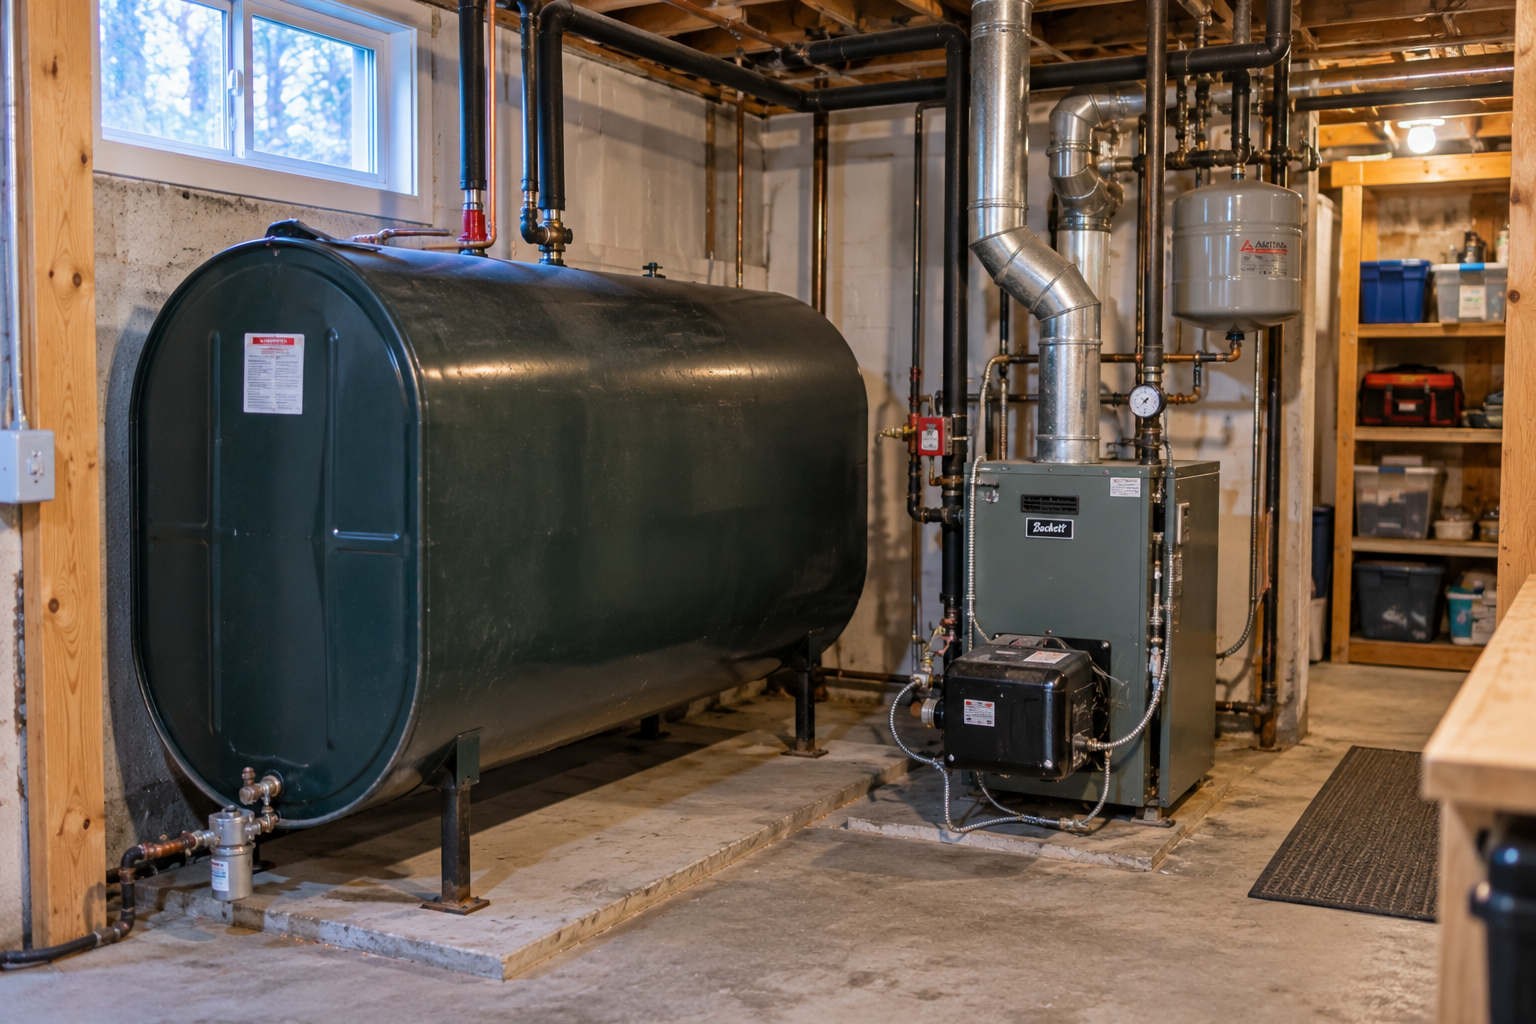
Oil Tanks Can Create Insurance Complications

Oil heating remains common in Nova Scotia, particularly in older homes.

An oil-fired furnace or boiler doesn't automatically make a property difficult to insure, but the oil storage tank can be an important consideration.

Insurance companies may ask:

  • How old is the tank?

  • Is it located indoors or outdoors?

  • Is it steel, fibreglass or another approved construction?

  • Is it a single-wall or double-wall tank?

  • Is there evidence of corrosion, damage or leakage?

  • Is documentation available showing when it was installed?

Some insurers apply age limits or other requirements to particular tank types.

A tank may appear to be functioning normally but still fall outside an insurer's guidelines.

For example, a buyer might discover that the insurer requires replacement of an older tank before issuing coverage.

That creates an unexpected expense and potentially a timing problem if closing is approaching.

If the property has oil heating, ask about the tank's age and installation history early, rather than assuming that a functioning heating system will be acceptable.

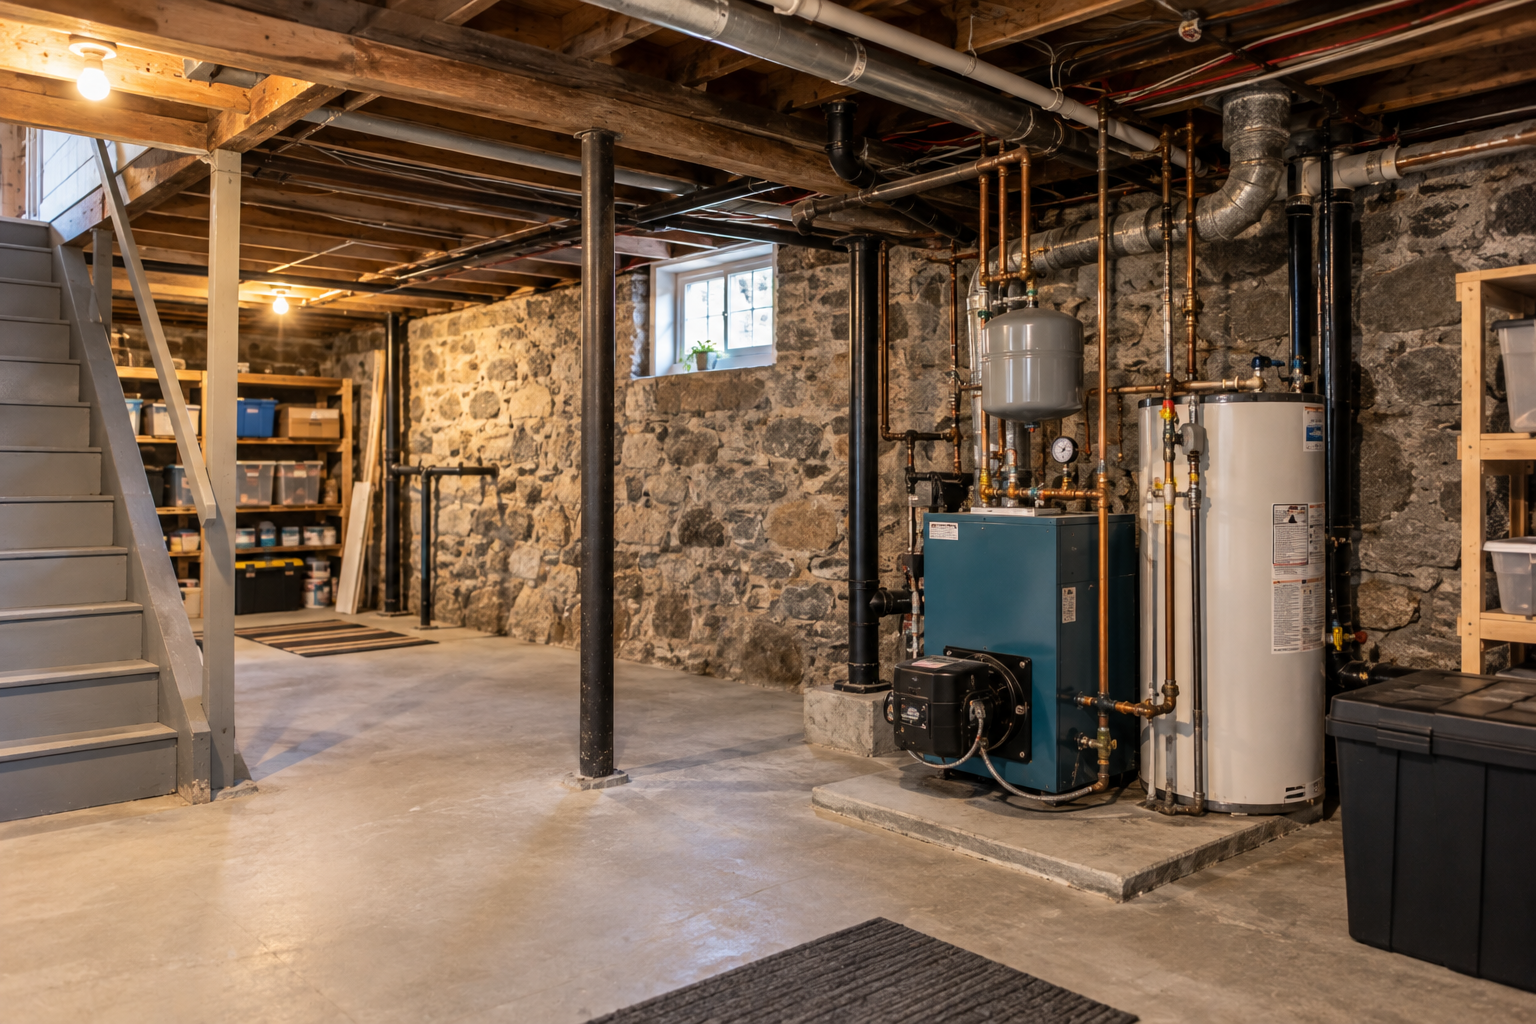
Residential heating oil storage tank in a Nova Scotia home basement

Wood Stoves, Fireplaces and Wood Furnaces May Require Additional Documentation

Wood-burning heating systems are common throughout rural Nova Scotia.

While wood stoves and fireplaces are often used for supplemental heating, some homes have wood-fired furnaces or boilers that provide much of the home's heat.

Other properties have combination heating systems, such as wood-and-oil furnaces.

These systems can be economical and practical, but they can also create additional insurance requirements.

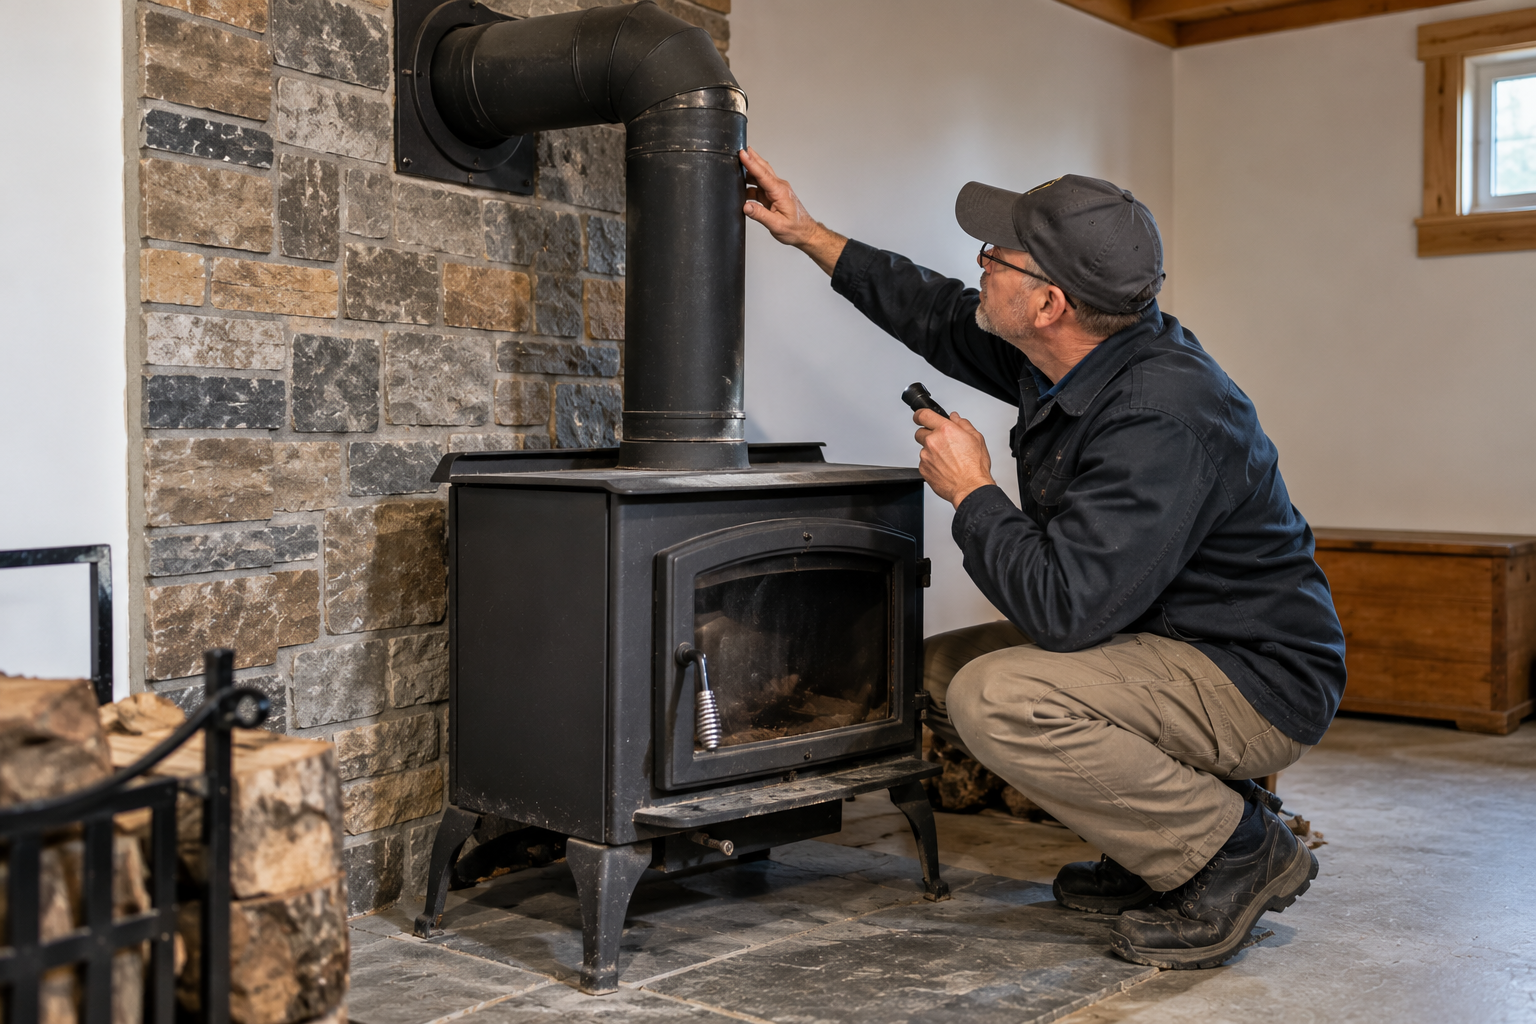
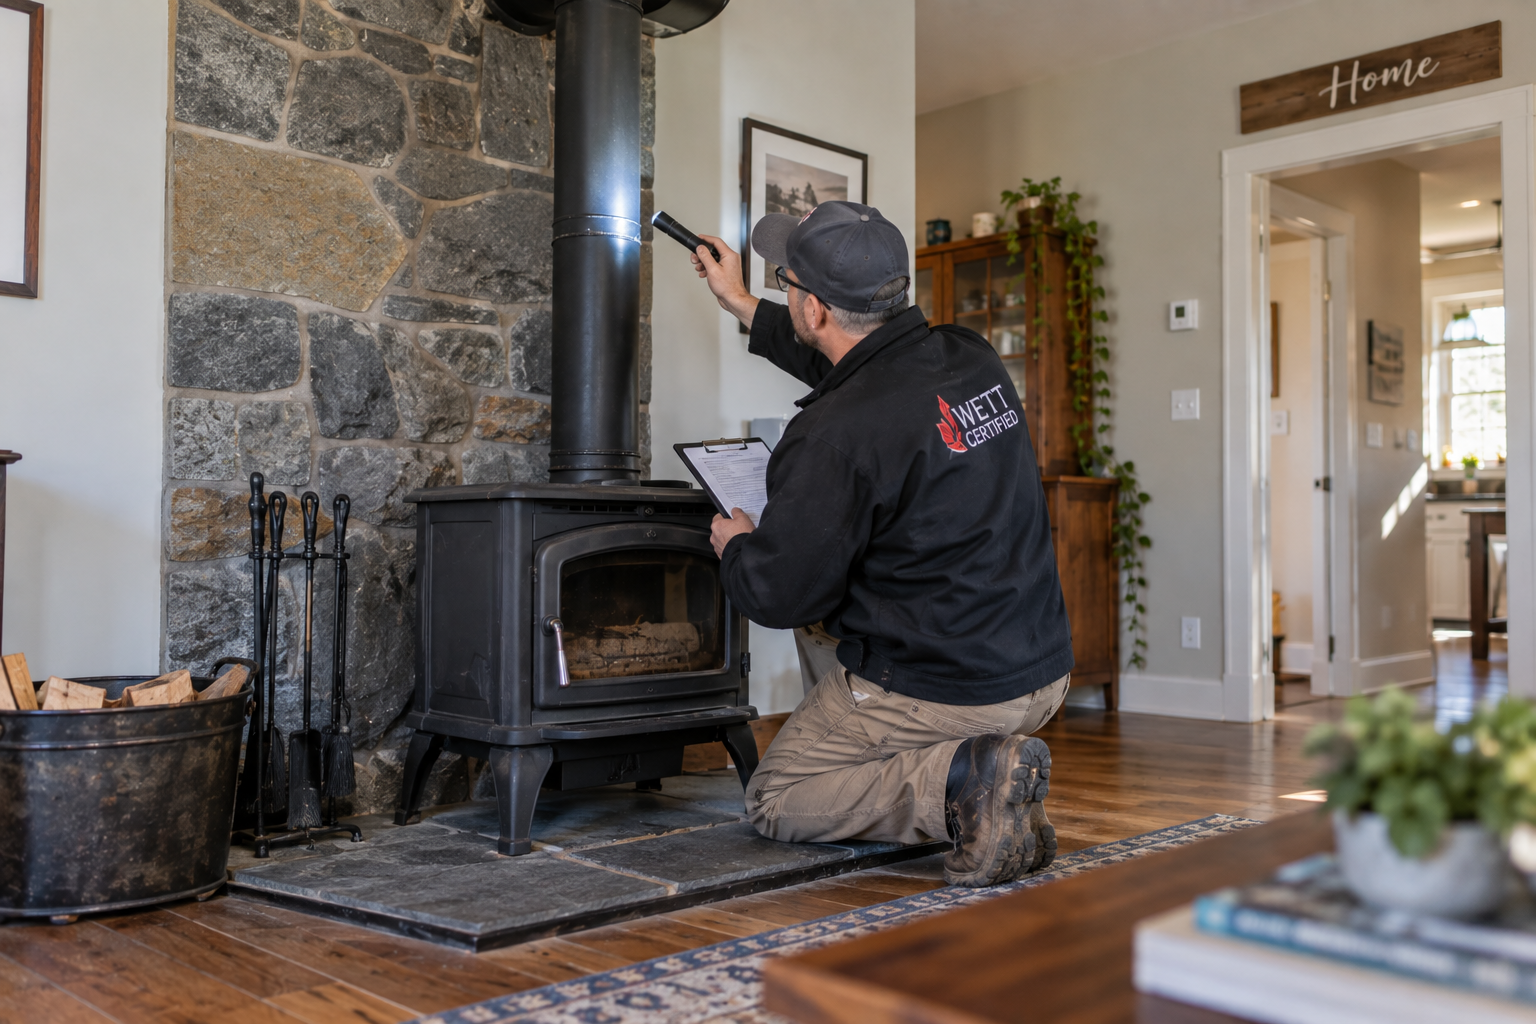
One common requirement is a WETT inspection.

WETT stands for Wood Energy Technology Transfer. A WETT-trained professional can examine a wood-burning installation and document observations concerning its condition and installation.

Depending on the equipment, an insurer may require a WETT inspection for:

  • Wood stoves

  • Wood-burning fireplaces and fireplace inserts

  • Wood-fired furnaces

  • Wood-fired boilers

  • Combination wood-and-oil heating systems

Potential concerns include:

  • Clearance from combustible materials

  • Chimney and flue condition

  • Proper installation of the appliance

  • Floor and wall protection

  • Visible deterioration or unsafe modifications

  • Connections between heating appliances and the chimney

A WETT inspection isn't an insurance approval or a blanket certification that every aspect of an installation is compliant.

The insurer determines what documentation it will accept.

Some insurers may also ask whether wood is the primary or supplemental heating source.

When I'm helping buyers consider a property with wood-burning equipment, I encourage them to confirm the insurer's requirements early, particularly when a wood furnace or combination heating system is involved.

If a home has a wood stove, fireplace, wood furnace or other solid-fuel heating appliance, find out what the insurer requires before your purchase conditions expire.

Professional examining the flue connection of a residential wood stove during an inspection

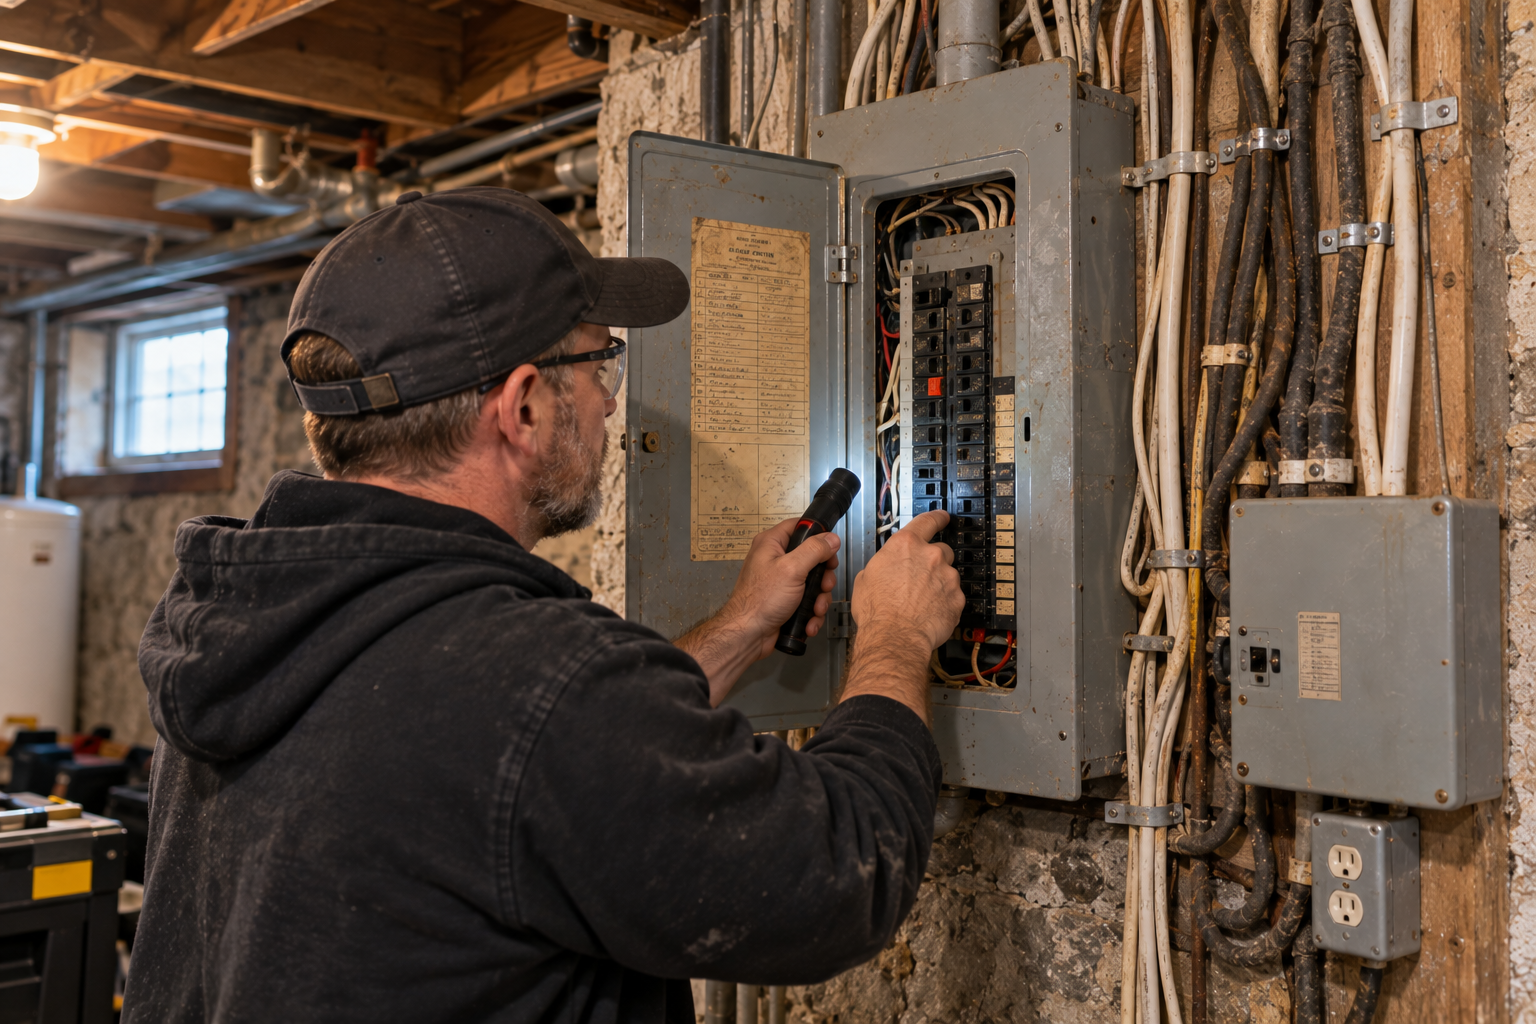
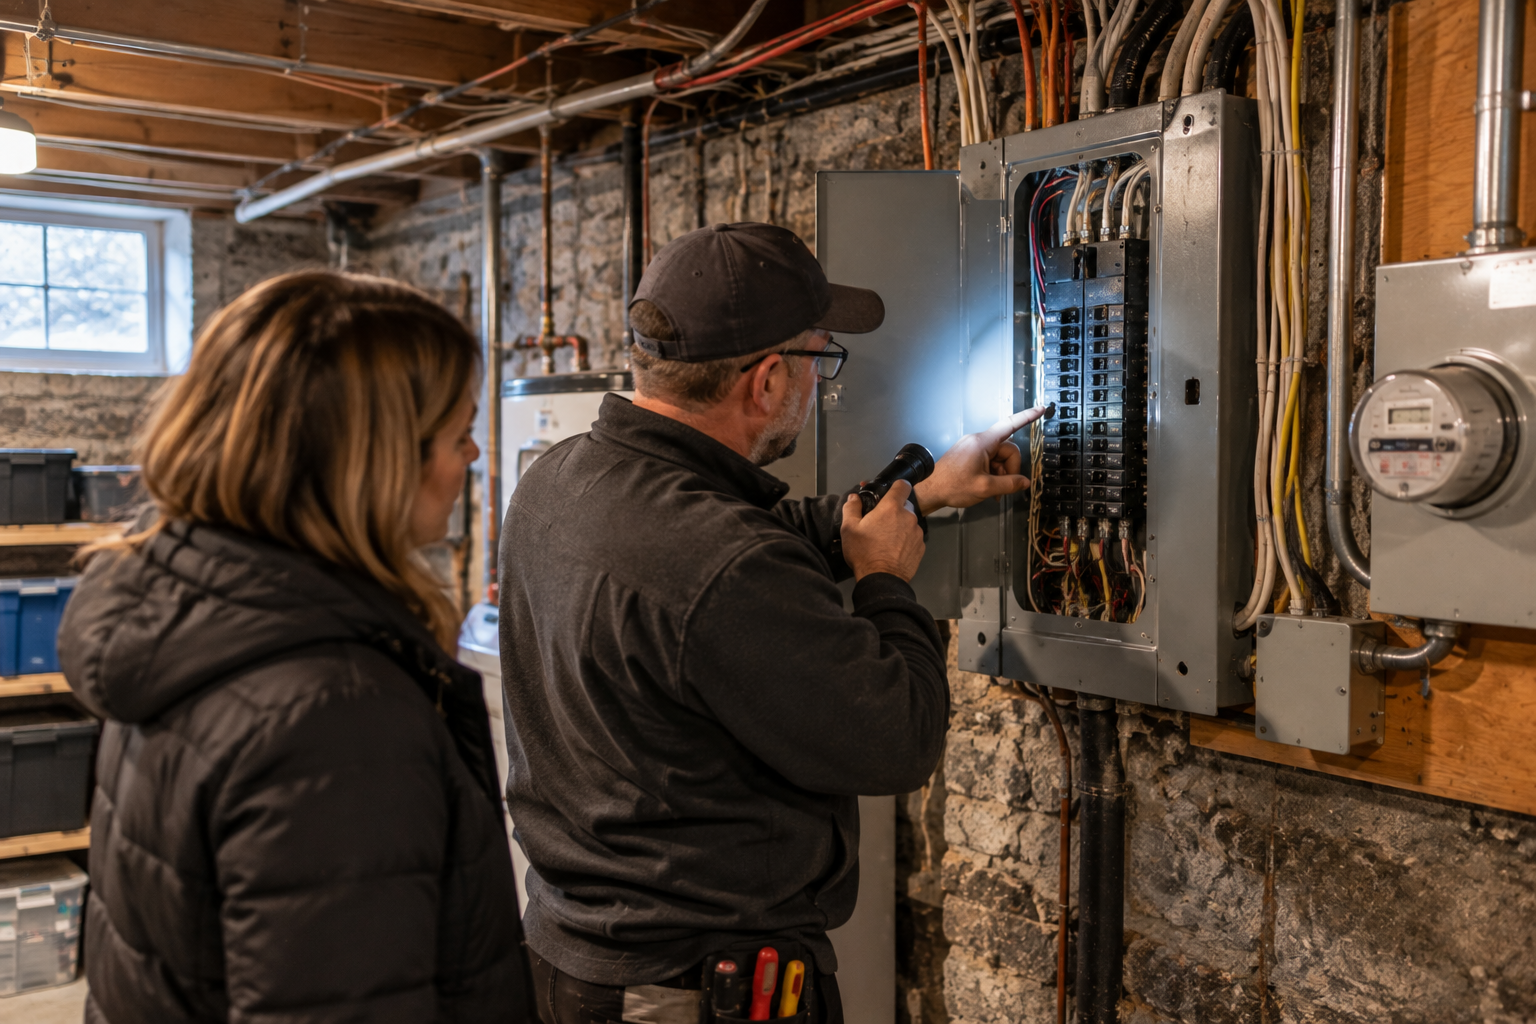
Older Electrical Systems Can Be a Concern

Nova Scotia has many older homes, including properties that have been renovated and expanded over several decades.

Some contain a combination of newer electrical components and older wiring.

Insurance companies may have concerns about:

  • Knob-and-tube wiring

  • Aluminum branch-circuit wiring

  • Older fuse panels

  • Certain electrical panel models with known safety concerns

  • Visible unsafe electrical installations

  • Electrical work that requires further professional assessment

Not every older electrical installation is automatically unacceptable.

For example, a properly maintained older system may be treated differently from one with evidence of overheating, damaged wiring or unsafe modifications.

An insurer may request an electrician's report or require specific upgrades.

It's also important not to assume that replacing an electrical panel automatically resolves concerns elsewhere in the system.

If an inspection identifies an electrical concern, I encourage buyers to have it assessed by a qualified electrician and confirm any insurance requirements before making a decision.

The insurance question is not simply whether the electricity works. It's whether the insurer considers the installation acceptable.

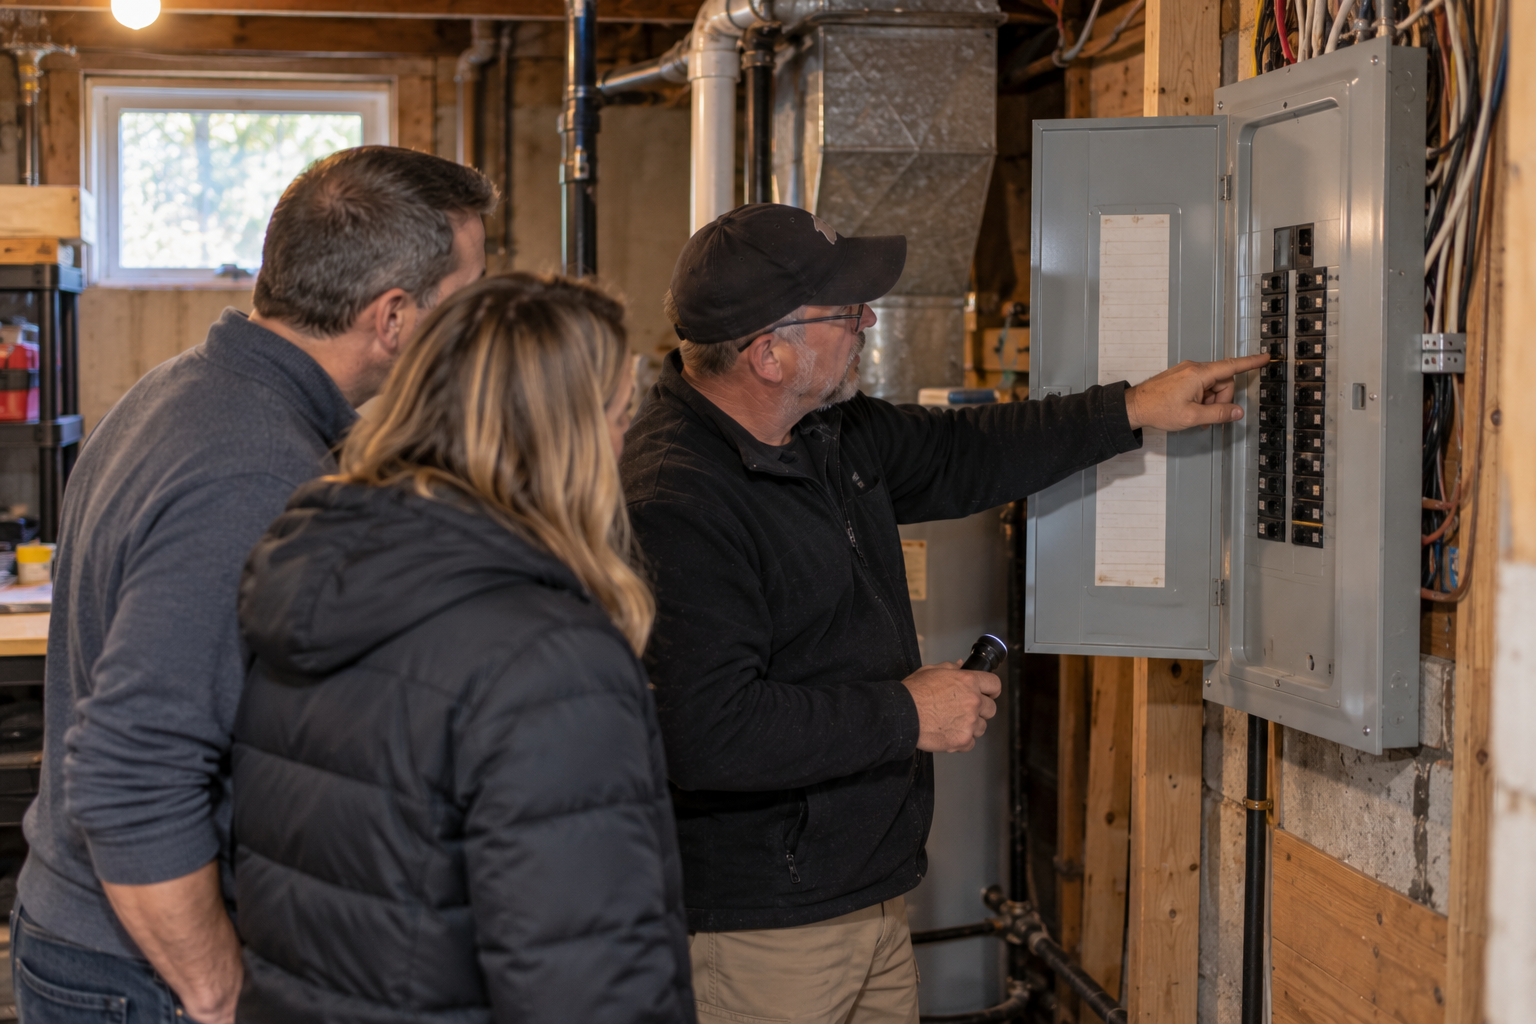
Electrician assessing an electrical panel in an older residential home

Roof Age and Condition Can Affect Coverage

A roof doesn't have to be new to obtain home insurance.

However, insurers may consider its age, roofing material, visible condition and history of leaks.

Missing shingles, significant deterioration, damaged flashing or evidence of ongoing water intrusion may create concerns.

Depending on the circumstances, an insurer might:

  • Request additional information

  • Require repairs or replacement

  • Apply limitations to certain coverage

  • Offer different settlement terms for roof damage

  • Decline coverage until the issue is addressed

It's also worth understanding that insurance is not a maintenance plan.

A roof reaching the end of its useful life doesn't automatically qualify for replacement through an insurance claim.

Coverage generally depends on the cause of damage and the policy's terms.

If the roof is older, ask the seller about its replacement history and discuss the information with your insurance provider.

Don't rely on an estimated roof age alone if the insurer needs more specific documentation.


Previous Water Damage and Plumbing Problems

Water damage can be expensive, and insurers often pay particular attention to a property's water-related risks.

Concerns may include:

  • Previous basement flooding

  • Recurring water intrusion

  • Older or deteriorated plumbing

  • Past water-damage claims

  • Evidence of unresolved leaks

  • Drainage or sewer backup problems

A previous claim doesn't automatically mean the property is uninsurable.

The nature of the incident, whether repairs were completed, and whether the underlying cause was corrected can all matter.

It's also important to distinguish between different types of water coverage.

Damage from a sudden plumbing failure may be treated differently from sewer backup, overland flooding or coastal flooding.

These risks aren't necessarily covered in the same way, and some coverage may be optional, restricted or unavailable for a particular property.

Ask what is actually covered rather than assuming that a policy described as comprehensive includes every kind of water damage.

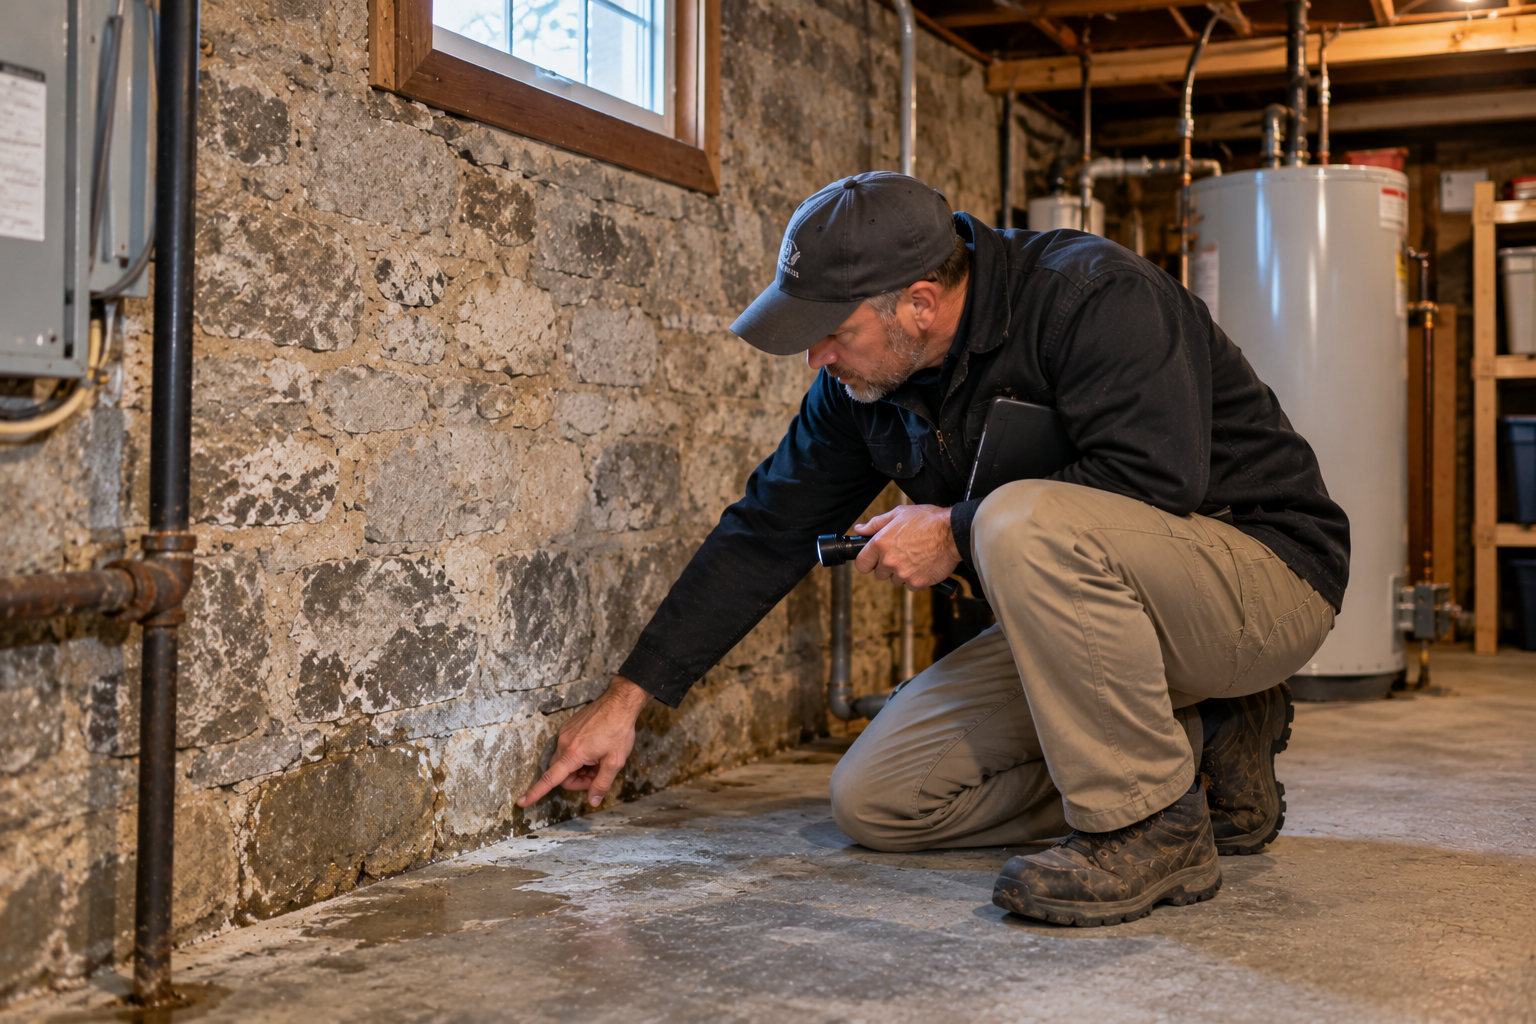
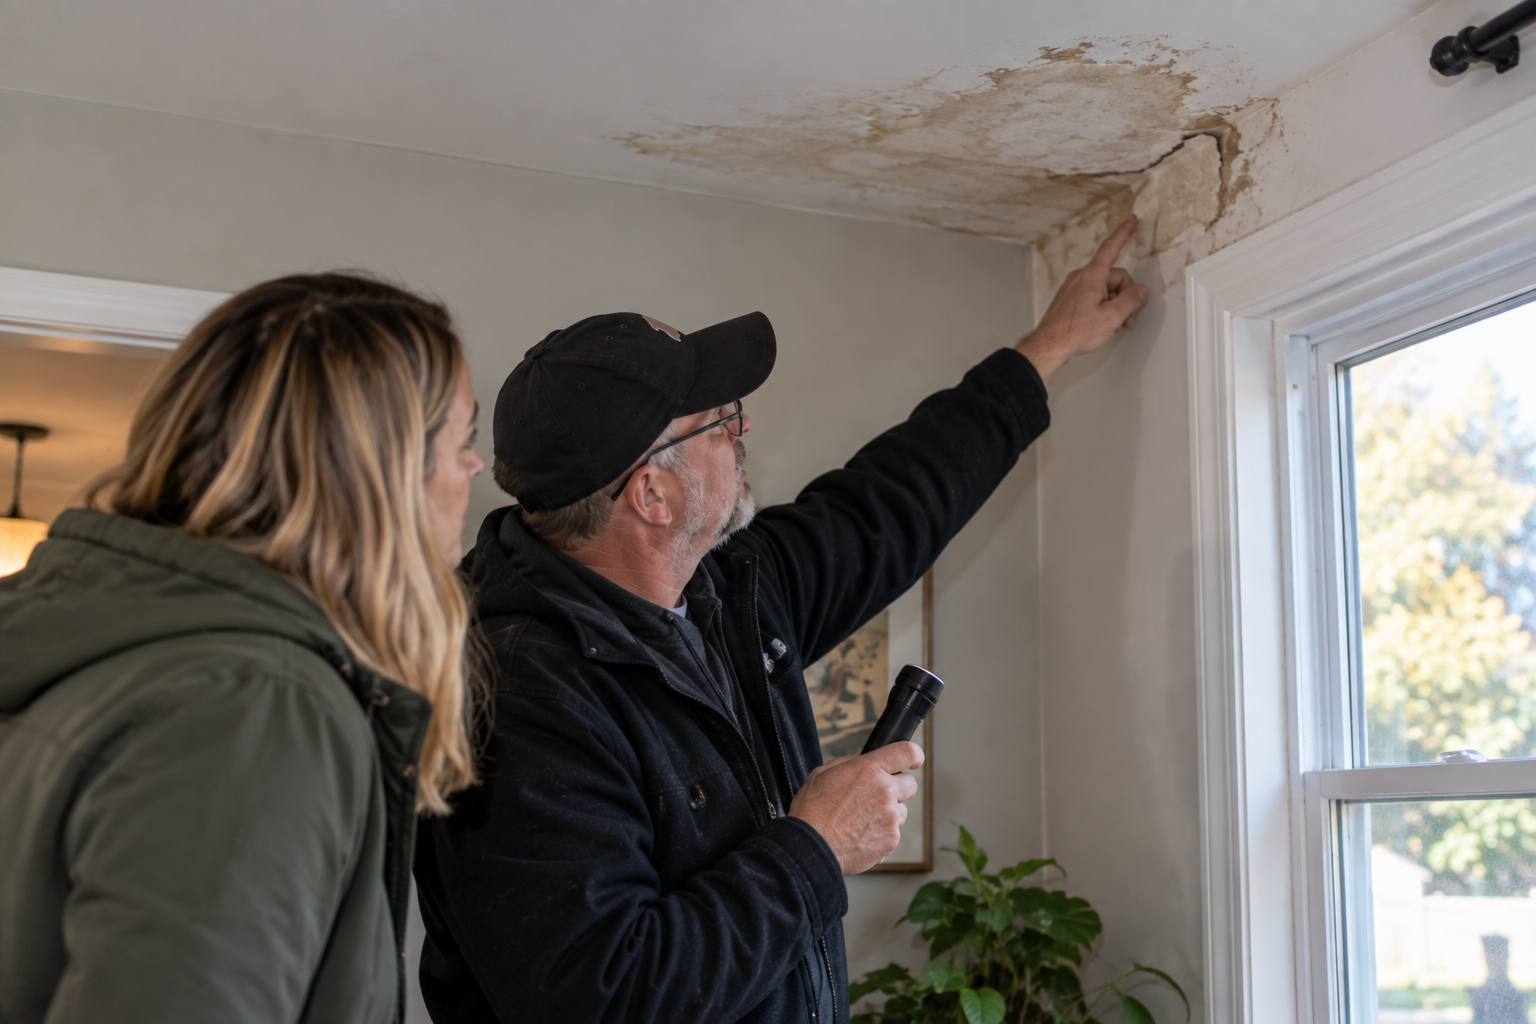
Home inspector evaluating signs of moisture in a residential basement

Rural Homes May Have Different Insurance Considerations

Living in the country is one of the attractions of buying in the Annapolis Valley and other parts of Nova Scotia.

More land, privacy and distance from neighbouring properties can be appealing.

But location can affect insurance.

An insurer may consider:

  • Distance from a responding fire station

  • Availability of fire hydrants or other firefighting water sources

  • Access for emergency vehicles

  • Road conditions and accessibility

  • Construction materials

  • Heating systems and occupancy

A home located outside a community with municipal fire hydrants may be assessed differently from a similar home in town.

That doesn't mean rural homes are necessarily difficult to insure.

It does mean that insurance costs and requirements may differ, even between properties that otherwise appear similar.

Get a quote for the actual property rather than assuming the insurance cost will be comparable to your current home.


Coastal and Waterfront Properties Need Special Attention

Nova Scotia offers beautiful coastal, lakefront and riverfront properties.

But water access and scenic views can come with insurance considerations.

Depending on the location, insurers may assess exposure to:

  • Coastal flooding

  • Storm surge

  • Overland flooding

  • Erosion

  • Wind and storm damage

  • Previous water-related losses

Not every waterfront property faces the same risks.

A home elevated well above the shoreline may present different concerns from one located close to the water at a low elevation.

Waterfront properties can introduce additional insurance considerations, particularly around flooding, shoreline erosion and the property's location. My guide to buying waterfront property in Nova Scotia explains what buyers should investigate before committing to a purchase.Some risks may be excluded, while others may be available through additional coverage.

Before buying, ask the insurer to explain the relevant exclusions and limitations for the specific property.

Being able to obtain home insurance doesn't necessarily mean every risk associated with a waterfront location is covered.

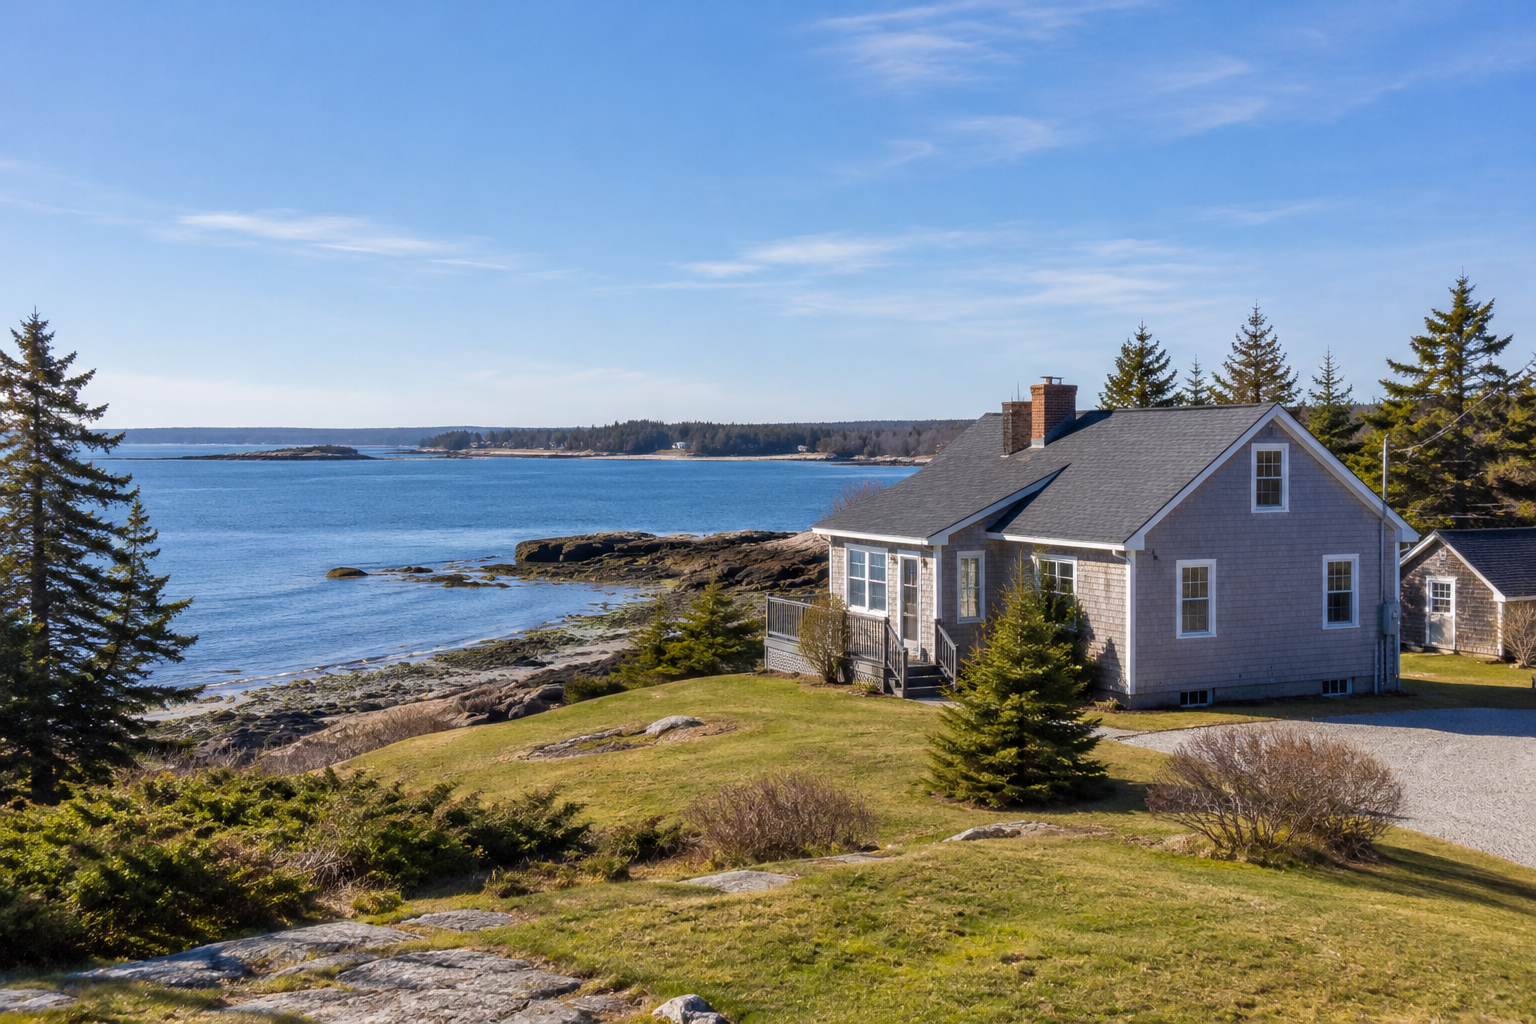
Coastal Nova Scotia home near the shoreline where insurance coverage may require additional review

Vacant Homes, Cottages and Renovation Properties

How you intend to use a property can be just as important as its physical condition.

An insurer may treat a year-round residence differently from:

  • A seasonal cottage

  • A property that will remain vacant

  • A home awaiting major renovations

  • A property undergoing substantial construction work

  • A home occupied only occasionally

Insurance companies commonly distinguish between a home that is temporarily unoccupied and one considered vacant under the policy.

Those distinctions can affect coverage.

This is particularly important for buyers relocating to Nova Scotia.

Perhaps you're purchasing several months before your move.

Maybe you plan to renovate before occupying the home.

Or perhaps you're buying a cottage that will only be used during part of the year.

Tell the insurer exactly how the property will be used, when you expect to occupy it and whether significant work is planned.

Don't assume a standard owner-occupied policy will automatically fit your circumstances.


What Happens If an Insurance Company Refuses the Property?

An insurance refusal can be unsettling, particularly after you've already invested time and money in inspections.

But one insurer declining a property doesn't necessarily mean no insurer will cover it.

Different companies have different underwriting requirements and risk tolerances.

Depending on the issue, possible next steps may include:

  • Providing additional property information

  • Obtaining a specialist inspection

  • Supplying documentation of previous repairs

  • Completing a required improvement

  • Contacting another insurance provider

  • Working with an insurance broker to explore other options

Sometimes the concern can be resolved relatively easily.

For example, the insurer may simply need confirmation of when an oil tank was installed.

Other situations may be more complicated.

An insurer might require a major electrical upgrade, roof replacement or correction of a heating-system concern.

These can involve substantial costs and may not be practical before closing.

Don't assume that agreeing to complete repairs after purchasing the home will satisfy the insurer. Get confirmation of what is required and when.


Can an Insurance Problem Affect Your Mortgage?

Yes.

If you're purchasing with mortgage financing, your lender will generally require acceptable property insurance.

A problem obtaining coverage may prevent the lender from advancing funds.

It's also possible for an insurer to offer a policy that doesn't meet the lender's requirements.

For example, a lender may have requirements concerning the insured amount, coverage type or how its interest in the property is recorded.

This is why buyers should keep their mortgage professional informed if an insurance issue arises.

A mortgage pre-approval doesn't guarantee that every property will meet the lender's requirements.

And a home that satisfies the lender's property assessment may still need to satisfy the insurance company's requirements.

Insurance is just one of several issues that can affect mortgage approval. I explain other potential complications in my article, Your Mortgage Is Pre-Approved — So Why Can Financing Still Fall Through?

Financing and insurance are separate parts of the purchase, but they can affect one another.


What If an Insurance Problem Is Found During Your Purchase Conditions?

Suppose you've had an offer accepted on an older home.

During your insurance inquiries, you discover that the insurer requires the oil tank to be replaced.

What happens next?

First, establish exactly what the insurer requires.

Is replacement mandatory before coverage begins?

Would another insurer accept the existing tank?

Is an inspection or additional documentation sufficient?

If replacement is necessary, what will it cost, and can the work be completed within the available time?

Once you understand the issue, you can consider your options under the Agreement of Purchase and Sale.

Depending on the circumstances, you might decide to proceed, investigate further, propose an amendment to address the concern, or determine that you're not comfortable continuing.

A seller isn't automatically required to complete work simply because an insurance company has requested it.

Any proposed change to the agreement is subject to the seller's acceptance.

The original condition deadline also remains important unless the parties agree to amend it.

Discovering an insurance problem doesn't automatically change the purchase agreement or extend your deadline.

When an insurance issue arises during a purchase, I help my buyers understand their options under the agreement, coordinate communication with the seller's representative, and keep track of important condition deadlines.

I can help navigate the real estate process, while the insurance professional determines coverage requirements and a lawyer provides legal advice when needed.

Homebuyer discussing property insurance concerns with a real estate professional

Don't Wait Until the Last Few Days Before Closing

One of the simplest ways to avoid an insurance surprise is to start the process early.

When I'm working with buyers, I encourage them to contact their insurance provider early in the conditions period, rather than waiting until closing approaches.

Provide accurate information about the property, including its heating systems, roof, electrical system and intended occupancy.

If the insurer needs additional documentation, there may still be time to obtain it.

If a problem arises, you may have time to investigate alternatives before deciding whether to proceed.

Waiting until closing is only a few days away can leave limited options.

This is especially important for buyers moving from another province who may be unfamiliar with some of the heating systems, property types and rural conditions commonly found in Nova Scotia.


Questions Worth Asking Your Insurance Broker

Before finalizing your purchase, consider asking:

  1. Is this particular property acceptable to the insurer?

  2. Are there concerns about the age of the home, heating system, oil tank, wood stove, electrical wiring or roof?

  3. Will additional inspections or documentation be required?

  4. Are any repairs or upgrades required before or after closing?

  5. Are there coverage exclusions or limitations I should understand?

  6. What water, flood, sewer backup and storm-related coverage is available?

  7. Does the policy reflect how I intend to use and occupy the property?

  8. What deductible will apply, including for weather-related losses?

  9. Is the quoted premium subject to further underwriting review?

  10. Can acceptable coverage be confirmed in time for closing?

An insurance broker may be able to compare options from multiple insurers, while a direct insurance provider can explain its own requirements.

The important thing is to understand the coverage being offered and any outstanding conditions.


The Home Inspection and Insurance Review Should Work Together

A home inspection can provide valuable information that helps with your insurance inquiries.

For example, the inspector may identify an older oil tank, a wood stove without available documentation, or electrical components that warrant further evaluation.

Those findings may prompt questions for the insurer.

Likewise, an insurance company may request information that wasn't part of the general home inspection.

Neither process replaces the other.

A home inspector doesn't approve insurance coverage.

And an insurance company doesn't provide a comprehensive home inspection simply because it agrees to issue a policy.

When I'm helping buyers, I encourage them to consider both the inspection findings and any insurance requirements before making their final decision.

Use both processes to understand the property before making your final purchase decision.


Don't Choose Insurance Based on Price Alone

It's natural to compare premiums.

But the least expensive policy isn't necessarily the most suitable one.

Two policies with different premiums may also have important differences in:

  • Coverage limits

  • Deductibles

  • Water damage protection

  • Exclusions

  • Replacement-cost provisions

  • Coverage for detached buildings

  • Requirements concerning occupancy or maintenance

For a rural home, waterfront property, older house or cottage, these differences can be particularly important.

Ask your insurance professional to explain the policy rather than comparing only the annual cost.

A lower premium may be attractive, but understanding what you're purchasing matters more.


Home Insurance Is Part of Understanding the Property

When buying a home, it's easy to focus on whether you like the layout, location and condition.

Those things matter.

But so does understanding what it will take to own and maintain the property.

A century-old home may require additional insurance investigation, even if it has been beautifully maintained.

An older oil tank may represent a future replacement expense.

A wood stove may require additional inspection.

A rural location may affect insurance costs.

A waterfront setting may come with coverage limitations that deserve careful consideration.

None of these automatically means the property is a poor purchase.

They are simply part of understanding what you're buying.

When I'm helping buyers purchase a home in Nova Scotia, I encourage them to investigate insurance early, particularly when a property has older systems, unusual features or a rural location.

An insurance concern doesn't automatically mean a home is a poor choice. What matters is understanding the requirements, potential costs and available options before making a final commitment.

If you're planning to buy a home in Nova Scotia, I'm always happy to help you work through the buying process, ask the right questions and connect with the appropriate professionals when additional information is needed.

The goal is to identify potential problems early, understand the requirements and make your decision with the right information.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.
Read

Nova Scotia’s Property Tax CAP: What Home Buyers Need to Know

The property taxes shown in a listing can look reassuring. But before you use that amount in your ownership budget, there is an important question to answer:

Does the seller’s tax bill reflect a capped assessment that will change after you buy?

Nova Scotia’s Capped Assessment Program, usually called CAP, can make the seller’s current taxes a poor guide to your future costs.

When we review a home, I’ll help you look beyond the advertised tax amount and identify what needs to be confirmed before you rely on it.


CAP Limits Assessment Growth, Not Your Entire Tax Bill

CAP limits annual growth in eligible taxable assessments using a rate tied to Nova Scotia’s Consumer Price Index. For 2026, the CAP rate is 2.6%. That is an assessment adjustment, not a municipal tax rate or a guarantee about the increase in your bill. PVSC’s 2026 assessment information.

Property Valuation Services Corporation, or PVSC, assesses properties and administers CAP. Municipalities set tax rates and issue tax bills. PVSC does not set those rates or collect property taxes. About PVSC.

That distinction matters when you are trying to understand a number in a listing. We need to look at both the assessment and the municipal charges applied to it.


Buyer reviewing property assessment information

Understand the Different Assessment Figures

A Property Assessment Notice may show several values:

  • Assessed value: PVSC’s valuation of the property for the assessment year.

  • Capped assessment: The value calculated under CAP, where applicable.

  • Taxable assessed value: The value used for property-tax purposes.

The notice is separate from the municipal tax bill. PVSC’s guide to your assessment notice.

Where CAP applies, taxable assessment is the lower of assessed value and capped assessment. PVSC’s CAP guide.

For a buyer, the useful question is whether there is a substantial gap between those figures. I’ll help you identify that gap and put it into the context of your purchase.


Buyer discussing home ownership questions before purchasing

What Happens After You Buy?

For an ordinary purchase from an unrelated seller, CAP is removed for the assessment year following the sale. It can apply again the following year if the new owner and property qualify.

For example, under the current rules:

TimingAssessment treatment
Purchase during 2026Sale occurs
2027 assessmentCalculated without the seller’s CAP
2028 assessmentNew owner’s CAP can apply if eligible

This follows the purchase timeline explained by PVSC. The seller’s capped value does not simply become your ongoing assessment. PVSC’s CAP guide.

We’ll consider the years after closing when building your budget, rather than relying only on the tax amount available when you make your offer.


A Simple Example Shows Why It Matters

The following figures are hypothetical. They illustrate the effect of a different taxable assessment; they are not a forecast for a particular property or municipality.

Assume a tax rate of $1.00 per $100 of taxable assessment, with no additional charges included.

ExampleTaxable assessmentTax at the illustrative rate
Seller’s capped assessment$200,000$2,000 annually
Buyer’s later uncapped assessment$350,000$3,500 annually
Difference$150,000$1,500 annually

That is $125 more per month to include in a household budget.

The calculation is:

Taxable assessment ÷ 100 × rate per $100

Municipal taxes can also include area rates and other applicable charges. For example, the Municipality of the County of Kings identifies both its general rate and community-specific area rates as part of the calculation. Kings County property-tax information.

The example holds the rate constant to show the assessment effect. Actual assessments, rates and charges may change.


Different homes along an established residential street

Does the Assessment Become Your Purchase Price?

Do not assume that removing CAP means the next assessment will exactly equal the price you paid.

PVSC uses an annual valuation cycle. Its assessment reflects market value at a specified date and the property’s physical condition at another specified date. For example, 2026 assessments reflect market value as of January 1, 2025, and physical condition as of December 1, 2025. PVSC’s assessment timeline.

That timing is one reason an assessment and a current purchase price can differ.

When we review a property, I’ll keep the offer-price discussion separate from the tax estimate. Comparable sales help us consider an offer; the applicable assessment and municipal rates help us investigate taxes.

Neither the seller’s tax bill nor today’s assessment guarantees your future bill.


Eligibility Needs to Be Confirmed

General CAP requirements include at least 50% ownership by a Nova Scotia resident, qualifying property type and ownership duration. Condominiums must be owner-occupied. Certain family transfers have exceptions to the usual sale treatment.

New construction can also affect the calculation: its assessed value is added to the capped amount. PVSC’s CAP guide.

If you are relocating, buying with someone who lives outside Nova Scotia, purchasing through a company or considering a property with several uses, we’ll identify the questions to put directly to PVSC.

The same applies to a family transfer. Before relying on an exception, have PVSC and your lawyer confirm how the particular ownership arrangement will be treated.


Older home with an adjoining finished living space

Renovation Plans Belong in the Conversation

If you intend to add living space, finish an area or undertake substantial work, include assessment questions in your planning.

PVSC’s annual assessment process accounts for physical changes, including renovations, additions and demolition. PVSC’s assessment timeline.

I’ll help you flag planned work that deserves a conversation with PVSC. Ask how the proposed change could affect the assessment and when it would be reflected.

Avoid building your long-term budget around an assumption that the current assessment will continue unchanged after improvements.


Buyer gathering information about property taxes

How We’ll Check Taxes Before You Make an Offer

When we are considering a property, I’ll help you gather the available information and separate confirmed amounts from estimates.

We’ll work through these questions:

  • What year does the tax amount in the listing cover?

  • What are the current assessed, capped and taxable values?

  • What municipal and area rates apply to this address?

  • Are there separate charges that need to be included?

  • What should PVSC confirm about the purchase and CAP eligibility?

  • What allowance should you make for future changes?

PVSC provides a public assessment search by civic address or assessment account number. Find an assessment through PVSC.

The municipality can explain the rates and charges for the property. I’ll help you bring those pieces together into a working estimate, with any remaining uncertainty clearly identified.


Compare Homes Using Your Expected Costs

A home with lower advertised taxes is not necessarily the less expensive home for you to own.

When comparing properties, we’ll look beyond the seller’s current bill. A difference may reflect assessment history, municipal rates, services or other property-specific circumstances.

For a move within Nova Scotia, we’ll also review the property you are buying on its own merits. Your existing home’s tax amount is not a reliable budget for the next one.

This matters particularly when downsizing. A smaller home may reduce some expenses, but I’ll help you check the numbers before assuming every ownership cost will fall.

The guide How Much Does It Really Cost to Buy a Home in Nova Scotia? covers other expenses to include alongside property taxes.


Read Your Assessment Notice After the Purchase

When your notice arrives, check the property details, assessment figures and CAP treatment.

If something appears incorrect, contact PVSC promptly. An assessment appeal must be received within 31 days of the date on the notice; use the deadline printed on your own notice. PVSC’s assessment-notice guidance.

Keep the assessment notice and municipal tax bill together so you can understand how the figures connect.

Questions about valuation or CAP go to PVSC. Questions about the tax rate, billing or payment arrangements go to the municipality.


Modest home with a small established garden

Build Your Budget Around the Home You Are Buying

Property taxes deserve attention before you commit to a purchase, especially when the seller’s taxable assessment is substantially below the assessed value.

I’ll help you review the available information, identify the questions for PVSC and the municipality, and consider the result alongside your other ownership costs.

The seller’s tax bill is useful background. Your budget needs to reflect what may apply after you buy.

Considering a home in the Annapolis Valley or South Shore? Ask Rob about your next steps. We can review the property and identify the tax questions worth resolving before you make an offer.

Explore the Buyer Resource Centre for more practical guidance on buying and owning a home in Nova Scotia.

Read

Competing Offers: What Happens When More Than One Buyer Wants the Home?

Finding a home that feels right can quickly become more complicated when another buyer wants it too.

You may wonder whether to increase your price, change your conditions or make a decision faster than you expected. You may also have very little information about the other offers.

Understanding how competing offers work in Nova Scotia can help you make a clear decision while keeping your finances, property questions and priorities in view.

For the broader process, start with Making an Offer on a House in Nova Scotia: How the Process Works.


What Is a Competing-Offer Situation?

A competing-offer situation arises when a seller receives more than one written offer on the same property.

A busy showing schedule or someone saying they intend to offer is not the same as another written offer. The Nova Scotia Real Estate Commission specifically distinguishes verbal interest from competing written offers. NSREC guidance on competing offers.

I’ll help you separate what has actually been communicated from expectations about other buyers. A busy showing schedule can create urgency, but your decision should be based on confirmed information.


Buyer and REALTOR® discussing the competing-offer process

What Will You Know About the Other Offers?

In Nova Scotia, the seller directs their brokerage or designated agent on whether to disclose the existence of competing offers and the number received.

The listing representative must not disclose the contents of those offers. Knowing that competition exists does not entitle you to see another buyer’s price, conditions or closing date. NSREC By-law 737.

The Commission also prohibits indirect disclosure, such as telling a competing buyer where their offer ranks or that another offer is higher. NSREC guidance on offer confidentiality.

That leaves uncertainty. Your decision needs to be grounded in the property, your circumstances and the terms you are comfortable offering.


What Can the Seller Do?

The seller may accept an offer, counter one while setting others aside, or reject all of them. A properly structured backup agreement may also be considered.

You should not count on another opportunity to revise your offer. Prepare an offer you would be comfortable having accepted as written. NSREC guidance on the seller’s options.

It helps to think through your response before submitting. If the seller accepts, are you ready to proceed on those terms? If the seller counters, which parts would you reconsider?


Buyers considering how a home fits their needs

The Whole Offer Matters

Price deserves careful attention, but your offer contains several commitments.

Consider the proposed closing date, deposit arrangements, included items, conditions and the time available to complete them. A change that seems small during negotiations may have practical consequences later.

For example, an earlier closing date might require temporary accommodation, a change to your rental arrangements or a different financing plan. A larger deposit requires access to those funds when the agreement says they are due.

Before offering flexibility, check whether it works for you.

A term is only useful if you can carry it out.


Buyer reviewing purchase priorities before making an offer

Set Your Price Limit Before the Pressure Builds

Decide what you are comfortable paying before a competing-offer conversation becomes urgent.

We’ll review comparable sales alongside the home’s condition, location and likely ownership costs. We’ll also consider the work you already know you would want or need to do.

Then consider how the purchase would affect your everyday finances. What would remain available for closing costs, repairs and unexpected expenses?

The asking price is a reference point. Your decision also needs to reflect the property itself and your circumstances.

The guide How Much Does It Really Cost to Buy a Home in Nova Scotia? can help you think beyond the purchase price.

A useful question is: Would I still be comfortable with this purchase if I learned there had been less competition than I expected?


Mortgage Pre-Approval Does Not Approve Every Property

A mortgage pre-approval does not guarantee final financing. The lender still considers the property, and its valuation can affect the amount it will lend.

If you are considering a higher offer, speak with your mortgage professional about that specific price and property. Ask what would happen if the lender’s valuation were lower than your agreed purchase price, and whether additional cash might be required. Financial Consumer Agency of Canada: mortgage pre-approval.

Do not assume that room within a pre-approved maximum resolves every financing question.


Basement framing and foundation in an older home

Conditions Should Reflect What You Still Need to Know

Competition can create pressure to remove an inspection condition or shorten the time available to investigate the home.

The Commission recommends a home inspection and cautions that a seller’s disclosure statement reflects the seller’s knowledge; it does not establish that every defect is known. NSREC guidance on home inspections.

Consider the questions still unanswered about this particular property. Can it be financed and insured on acceptable terms? What investigations remain outstanding? Are there documents your lawyer needs to review?

Our guide Conditions in a Real Estate Offer: What Nova Scotia Buyers Should Know explains how those questions relate to the agreement.

Before changing a condition, ask the relevant professional what the change would mean. If you are considering a shorter deadline, check actual appointment availability and turnaround times.

An unanswered question remains unanswered even when another buyer wants the home.


An Offer Review Date Is Not a Guarantee That the Seller Will Wait

A seller may set a date for reviewing offers. However, the Commission explains that the seller can consider an earlier offer, including one that expires before the announced review date.

This is often called a pre-emptive offer. The seller may accept it, reject it, counter it or leave it unanswered. NSREC guidance on offer review dates.

I’ll clarify the seller’s current instructions, explain your offer’s expiry time and keep you informed of changes communicated to me.


Escalation Clauses Are Not an Available Shortcut

You may encounter advice from other markets suggesting an offer that automatically increases above a competing offer.

The Nova Scotia Real Estate Commission states that licensees cannot use escalation clauses when preparing an Agreement of Purchase and Sale. Adding one in a schedule does not make it compliant. NSREC guidance on escalation clauses.

I’ll help you assess the available sales information and prepare an offer at a specific price you understand and are comfortable paying.


Buyer discussing an offer decision by phone

You Can Decide to Hold Your Position

Learning about competition does not mean you must increase your price or change your terms. We’ll review your options together, including keeping your offer as written. If you are considering withdrawing it, I’ll confirm its status and explain when legal advice is needed before you act.

You may decide the offer already reflects what the property is worth to you. You may also decide that a proposed change would leave too little financial room or too much uncertainty.

Those are reasonable limits to establish before the conversation becomes rushed.


If Your Offer Is Not Accepted

It is disappointing to miss a home you had begun imagining yourself living in.

Before changing your approach for the next property, review the experience. Were you comfortable with your price? Did you understand the terms? Did the home suit your needs well enough to justify the commitments you offered?

Avoid assuming that one unsuccessful offer means you should remove protections or stretch further next time.

If a backup agreement is proposed, I’ll walk you through its terms and help identify anything your lawyer should clarify. Before signing, you should understand when it could take effect, how long you would be committed and what it would mean for your continued search.


Maintained home in an established residential neighbourhood

Make an Offer You Can Live With

A competing-offer situation can move quickly. Preparing your limits in advance gives you more space to think when decisions are time-sensitive.

I’ll help you assess the property, review the available sales information and understand the commitments in your offer. We’ll discuss where you have flexibility and which questions still need answers from your lender, inspector, insurer or lawyer.

The right offer is one you understand and are prepared to carry through if accepted.

Considering an offer on a home in the Annapolis Valley or South Shore? Ask Rob about your next steps. We can work through the property, your priorities and the questions that matter before you decide how to proceed.

Explore the Buyer Resource Centre for more practical guidance on buying a home in Nova Scotia, from evaluating a property to preparing an offer and planning for ownership.

Read

Conditions in a Real Estate Offer: What Nova Scotia Buyers Should Know

You’ve found a home you want to buy.

But there are still things you need to confirm.

Will your lender approve the financing for this particular property? What will the inspection reveal? Can you obtain suitable insurance? If the home has a private well and septic system, what should you investigate?

Those questions are part of deciding whether you’re comfortable completing the purchase.

The conditions in your offer help establish what needs to be investigated or arranged, and when those decisions must be made.

Understanding them before you sign is an important part of buying a home in Nova Scotia.


What Is a Condition in a Real Estate Offer?

A condition makes the purchase subject to a specified requirement under the terms of the agreement.

For example, a buyer may need satisfactory financing, a property inspection or an opportunity to review information about the property.

The standard Nova Scotia Agreement of Purchase and Sale includes a buyer’s conditions section with options covering financing, property inspections, insurance and certain documents. The conditions selected and any additional wording need to reflect the transaction. NSREC’s standard purchase agreement

Before agreeing to a condition, understand:

  • What you need to obtain, investigate or review

  • Who is responsible for doing it

  • What deadline applies

  • What notice the agreement requires

  • What happens if the requirement isn’t satisfied

The wording matters as much as the name of the condition.


Start With the Questions This Property Raises

It is tempting to think of conditions as a standard checklist that gets attached to every offer.

A better starting point is the property itself.

An older rural home may raise questions about water, septic, heating, outbuildings and access.

A condominium may require careful review of documents about the corporation and its finances.

A home in a leased-land community involves a different ownership arrangement from a conventional freehold property.

Your own circumstances matter too.

Do you need mortgage financing?

Does the purchase depend on selling your existing home?

Are you buying because you intend to operate a business, add another dwelling or keep animals?

Explain those plans early.

Something that is essential to your decision should be discussed before the offer is prepared.


Buyer discussing mortgage requirements with a lending professional

A Financing Condition Deserves More Than a Pre-Approval

A mortgage pre-approval helps establish what you may be able to borrow, but it does not guarantee that your mortgage will ultimately be approved.

The Financial Consumer Agency of Canada explains that a lender may still decline the mortgage because of the property, its appraised value or other requirements. FCAC’s mortgage pre-approval guidance

During your financing investigation, ask your mortgage professional:

Has the lender reviewed this specific property and purchase price?

Is an appraisal required?

Are any documents still outstanding?

Are there requirements involving my down payment or existing home?

Is there anything unresolved that affects my ability to complete the purchase?

Try to obtain a clear explanation of what has been approved and what remains to be done.

A reassuring conversation is useful. Understanding the outstanding requirements is more useful when you’re deciding whether to waive a financing condition.


Home inspector examining kitchen plumbing while a buyer observes

An Inspection Condition Gives You Information to Evaluate

A showing helps you decide whether you like a home.

A home inspection gives you an opportunity to investigate its condition more closely.

NSREC strongly recommends a home inspection and notes that a seller’s Property Disclosure Statement reflects the seller’s knowledge, which may not include every defect. NSREC’s home-inspection guidance

Think beyond simply booking an appointment.

You also need time to receive the findings, ask questions and decide whether further investigation is appropriate.

If an inspector recommends an electrician, roofer or structural professional, that recommendation may introduce another step before you’re ready to make a decision.

My guide to home inspections explains what buyers should expect from the inspection itself.

For your offer, the practical question is:

Does the condition and its timeline allow the investigation this property may need?


Water sample being collected for testing during a property investigation

Some Properties Need Additional Testing

A general inspection may be only part of your due diligence.

Depending on the property, you may want to discuss:

  • Well-water testing

  • Water-supply information

  • Septic-system inspection

  • Wood-burning appliance inspection

  • Specialist assessment of a building component

  • Review of permits or renovation records

  • Investigation of access or boundary questions

NSREC provides a Water and Septic Schedule, along with other schedules for particular property types. These can add requirements beyond those in the main agreement. NSREC’s guide to real estate forms

Don’t assume that saying “home inspection” automatically addresses every concern.

Explain what you need to learn so the appropriate investigation and contract wording can be considered.

Beyond the Home Inspection explores the additional tests and investigations a buyer may need.


Older home showing roof, chimney and exterior electrical service

Insurance Should Be Investigated Early

Before committing to a purchase, find out whether you can obtain suitable insurance for the property and your intended use.

An insurer may ask about the home’s electrical system, heating equipment, roof and other features. The Insurance Bureau of Canada specifically identifies these as factors insurers consider. IBC’s explanation of home-insurance factors

When discussing coverage, ask:

Does this quote reflect the actual property information?

Is additional documentation required?

Would any work need to be completed?

Are there exclusions or limitations I should understand?

Does the proposed coverage fit how I plan to use the property?

Give the insurer accurate information about matters such as a wood stove, rental use or an expected period of vacancy.

The purpose is to understand the arrangement you can actually obtain before making your decision.


Reviewing Documents Is Part of the Investigation

Some important questions won’t be answered by walking through the house.

You may need to review a Property Disclosure Statement, equipment information, restrictive covenants or documents associated with the property type.

A PDS records information based on the seller’s knowledge. NSREC describes receiving it as the beginning of a conversation and directs buyer representatives to pursue relevant follow-up questions. NSREC’s disclosure guidance

Read the answers carefully.

A reference to a previous leak may deserve another question.

A description of leased equipment may lead you to ask about the contract.

A restriction affecting the property may matter if you’re planning a particular use.

Receiving a document and understanding its implications are separate steps.


Special Property Types Can Bring Additional Conditions

The documents needed for one purchase may be quite different from those needed for another.

NSREC’s forms include schedules for resale condominiums, vacant land, mini/mobile/manufactured homes and leased-land communities, and multi-unit residential income properties. NSREC’s guide to real estate forms

For a buyer, the practical lesson is to look beyond the main offer form.

Read the attached schedules.

Ask which information must be supplied and which matters require your review.

If you don’t understand something in a schedule, raise it before signing rather than assuming it is routine wording that won’t affect you.


What If You Need to Sell Your Current Home?

If buying depends on selling your existing property, explain that when discussing the offer.

NSREC has a Sale of Buyer’s Property Schedule for transactions where the sale of the buyer’s current property is made a condition of the purchase. NSREC’s explanation of the sale-of-property schedule

Before proceeding, discuss questions such as:

  • Does your home need to be listed, sold or closed?

  • What happens if another buyer becomes interested in the property you want?

  • Could you complete the purchase if your sale were delayed?

  • What financing would be available?

  • How do the two transactions’ dates fit together?

Don’t assume that a general financing discussion has resolved all the risks of coordinating two properties.

Your REALTOR®, mortgage professional and lawyer may each have a part in working through the arrangement.


Buyer discussing a purchase agreement with a lawyer

Lawyer Review Has Its Own Purpose

Legal questions deserve legal advice.

A lawyer can help you understand the agreement and the legal issues associated with the purchase.

Under the standard Nova Scotia APS, lawyer review concerns the wording and content of the agreement, with the lawyers acting reasonably. It has its own deadline and notice provisions. NSREC’s standard purchase agreement

Arrange legal representation early and make sure your lawyer receives the documents promptly.

Also explain anything unusual about your plans for the property.

If your concern is whether you can operate a business, build an addition or use an access route, say so explicitly. Don’t assume another professional knows why that issue is important to you.


Give Yourself Enough Time to Investigate

A short condition period can sound appealing during negotiation.

But the useful question is whether the work can actually be completed.

Before proposing a deadline, consider:

  • Inspector and specialist availability

  • Laboratory processing time

  • Documents your lender still needs

  • Insurer response times

  • Your lawyer’s availability

  • Access to the property

  • Weekends and holidays

  • Time to understand the results

For example, having an inspection on the final afternoon may leave very little opportunity to investigate a concern it uncovers.

Build the schedule around the work, including the possibility of follow-up questions.

A deadline should allow time for a decision, not just an appointment.


Buyer coordinating property investigations by phone

Use the Condition Period Actively

Once the offer is accepted, begin the agreed work promptly.

Send the purchase documents to your lender and lawyer.

Book inspections.

Contact your insurer.

Request outstanding information.

Keep track of what has arrived and what remains unresolved.

A simple working list can help:

Investigation or document

Person responsible

Expected completion

Outstanding questions

Decision required

This is particularly useful when several professionals are involved. One person’s part may be complete while another is still waiting for information.

Stay involved in the results. The professionals provide information and advice, but you need to understand what you’re being asked to accept.


Being Satisfied and Providing Notice Are Separate Steps

For conditions requiring Form 408, you must provide the completed form to the seller or seller’s representative by the agreed deadline, clearly waiving all applicable conditions.

If that does not happen, the agreement is deemed terminated.

Signing the form without delivering it is not enough. NSREC’s Form 408 guidance

Before authorizing the notice, ask your REALTOR® to explain exactly which conditions it covers.

Make sure your decision reflects the information you have received and any outstanding questions.


Not Every Condition Uses Form 408

The standard lawyer-review, title-investigation and condominium estoppel-certificate clauses use notice of dissatisfaction rather than Form 408.

Other schedules can have their own procedures.

Follow the wording and deadlines in your agreement. NSREC’s explanation of different notice procedures

For practical purposes, avoid treating the purchase as though it has one deadline and one form that settles everything.

Ask for a clear explanation of which steps belong to you, your REALTOR® and your lawyer.


What If You Need More Time or Find a Problem?

You can propose an amendment requesting an extension or another solution. The seller may accept, reject or ignore it, or propose different terms.

Until an amendment is accepted, the original terms and deadline remain in effect. A terminated agreement cannot be revived by amendment. NSREC’s guidance on amendments and deadlines

Raise delays and concerns as soon as they appear.

If you’re waiting for a specialist, make that known while there is still time to consider options.

If an inspection finding changes your view of the purchase, my guide The Inspection Found Problems — What Happens Next? explains the decisions that may follow.


What If You Remain Unsatisfied?

Under the standard buyer-condition process, a buyer who is unsatisfied may terminate before the deadline in accordance with the agreement.

Discuss the appropriate steps with your REALTOR® and obtain legal advice where needed. NSREC’s buyer-condition guidance

Explain the actual concern and the information behind your decision.

Don’t rely on assumptions about what a condition allows, particularly if the wording has been changed or the issue is disputed.


A Terminated Agreement Doesn’t Automatically Release the Deposit

Termination and release of money held in trust are separate matters.

NSREC explains that a brokerage must retain the deposit until it receives the required written mutual direction or a court order authorizing disbursement. This applies even where the funds are not being disputed. NSREC’s deposit guidance

If the purchase ends, ask what documentation is required and who is arranging it.

Understanding that process can prevent confusion about when the money will become available.


Be Careful About Removing a Condition Before You Have Answers

A decision to proceed should reflect what you know and the uncertainty you are prepared to accept.

Before waiving a condition, ask yourself:

Have I received the information I was waiting for?

Do I understand the findings?

Have I spoken with the appropriate professional?

Is there an unresolved issue that could affect my decision?

Am I relying on an assumption that still needs to be checked?

If you feel rushed, explain why.

Perhaps a report has arrived but you haven’t discussed it with the inspector. Perhaps the lender has responded but you don’t understand an outstanding requirement.

Identify the gap before making the decision.


Buyer taking another look through a home before deciding to proceed

Conditions Work Best When They Lead to Better Information

The purpose of this stage is to understand the purchase more fully.

Can you arrange the financing?

Does the property’s condition work for you?

Can you obtain suitable insurance?

Do the documents raise questions that need answers?

Are there additional investigations appropriate for this home?

A useful condition addresses a real question, allows time to investigate it and provides a clear process for deciding what happens next.

Before you agree to proceed, understand what you have learned—and what you are accepting.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

Making an Offer on a House in Nova Scotia: How the Process Works

You’ve found a home you can picture yourself living in.

The location works. The rooms make sense. You’ve started thinking about where the furniture would go.

Then comes the question:

What happens if you want to make an offer?

Most buyers immediately think about price. But an offer also needs to address what you’re buying, what you need to investigate, when the purchase would close and the terms you’re prepared to accept.

Understanding those decisions before you sign can make the process feel much more manageable.


Start With What You Know—and What You Still Need to Find Out

Before deciding what to offer, take a moment to separate what you like about the property from what you actually know about it.

You may love the kitchen and the backyard.

But do you understand the heating system?

Have you considered the age of the roof?

Does the property have a private well or septic system?

Are there questions about access, boundaries, renovations or how you intend to use the property?

You won’t necessarily have every answer before making an offer. Some investigations may happen afterward under the conditions included in the agreement.

The important thing is to identify those unanswered questions early enough to address them properly.

The offer should reflect the particular home you’re buying and the information you still need.


Know Your Budget Before the Negotiation Starts

There are two numbers worth understanding before you make an offer:

What you may be able to borrow.

What you’re comfortable spending.

Those numbers aren’t always the same.

Think about the full cost of ownership, including heating, insurance, property taxes, maintenance and any work you expect to undertake.

Leave room for the costs of buying the home as well. Your down payment won’t be your only expense.

A mortgage pre-approval is useful preparation, but it can still be subject to requirements involving the property and its valuation. Discuss the home and your proposed purchase with your mortgage professional. NSREC’s home-buying guide

It is much easier to establish your financial limits before a counteroffer arrives than while you’re deciding whether to increase your price.


Buyer and REALTOR® comparing homes before deciding on an offer price

How Do You Decide What Price to Offer?

The asking price is a starting point for evaluating the property.

It doesn’t tell you, by itself, what you should offer.

Consider:

  • Recent sales of comparable properties

  • Differences in condition, size, land and location

  • The homes currently available to buyers

  • How long the property has been on the market

  • Any price changes

  • Work the property may need

  • Whether there is known competition

  • How well the home fits your needs and budget

Your REALTOR® can help you examine comparable sales and develop an offer strategy. NSREC’s explanation of the buyer representative’s role

A useful question is:

If I buy this home at this price, will I still be comfortable with the decision after the excitement of the negotiation has passed?


Should You Offer Below the Asking Price?

There isn’t a percentage below asking that makes sense for every property.

An offer below asking may be reasonable when the price is ambitious, the property has been available for some time or the evidence supports a lower value.

In another situation, a well-priced home may attract strong interest immediately.

The amount of a discount tells you very little without understanding the starting price.

A house purchased below asking can still be expensive for what it offers. A house purchased at asking can represent a sensible purchase.

Evaluate the property and the price together.


Your Offer Is Put Into Writing

In a typical Nova Scotia residential resale transaction, the offer is prepared using an Agreement of Purchase and Sale, often called the APS.

It identifies the parties, property, price and proposed terms. Additional schedules may be needed for the property or circumstances.

Once accepted, it becomes the purchase contract. NSREC’s guide to real estate forms

Treat the document as something you need to understand before signing.

If wording is unclear, ask what it means and how it applies to your purchase.

A conversation about what everyone intends is useful. The written agreement needs to accurately reflect those intentions.


Buyer reviewing the house, garage and surrounding property before making an offer

Be Clear About What You’re Buying

A showing can leave buyers with assumptions about what belongs to the property and what will remain.

Perhaps there is a second parcel of land beside the house.

Maybe an appliance caught your attention.

There could be a workshop full of equipment or a heating system that is leased rather than owned.

Before signing, clarify anything that matters to your decision.

Which land is included?

Which appliances and other items are included?

Is anything specifically excluded?

Does any equipment come with a rental, lease or other contract?

The current standard APS identifies the property by its civic information and property identification numbers, and provides for fixtures, specified chattels and equipment documentation. NSREC’s May 2026 standard forms

Don’t let an important inclusion depend on someone remembering a conversation several weeks later.


Buyer asking which appliances and fixtures are included in a home purchase

Fixtures and Chattels Deserve Attention

Fixtures are generally items attached to the property. Chattels are generally movable possessions.

That distinction can become less obvious when you start thinking about particular items.

A wall-mounted television and its bracket.

A freestanding cabinet beside built-in cabinetry.

Workshop equipment.

Decorative light fixtures.

An extra refrigerator in the garage.

If you want something included, or know the seller intends to remove it, have that addressed clearly.

The Legal Information Society of Nova Scotia recommends identifying the chattels you want included in your offer. Buying a home in Nova Scotia

Specific wording is easier to work with than assumptions about what normally stays.


The Deposit Is Part of the Purchase Price

The deposit is an amount paid according to the agreement and credited toward the purchase price when the transaction completes.

It is generally held in trust.

The agreement should identify the amount, recipient and deadline. Confirm the receiving brokerage’s accepted payment methods and allow time for the funds to arrive.

Under the standard Nova Scotia wording effective May 1, 2026, the seller may terminate if the deposit is not delivered as specified. An electronic deposit is considered received when it is available for deposit to the payee’s trust account. NSREC’s deposit guidance

A practical point follows from that:

Starting a transfer and meeting the deposit deadline may not be the same thing.

Arrange access to the money before promising a payment date.


Don’t Treat the Deposit as the Price of Changing Your Mind

Buyers sometimes assume that walking away from an accepted purchase simply means losing the deposit.

That is a dangerous assumption.

The current standard APS provides for forfeiture of the deposit on a buyer’s failure to complete, in addition to other claims the seller may have. The consequences depend on the agreement and circumstances. NSREC’s May 2026 standard forms

An accepted purchase deserves careful attention even while conditions remain outstanding.

If you’re considering not proceeding, review your rights and obligations with your REALTOR® and lawyer before acting.


Buyers planning the timing of their move before choosing a closing date

Choose a Closing Date That Works in Practice

The closing date affects more than when you book a moving truck.

Think about:

  • Your current lease or home sale

  • When your purchase funds will be available

  • Your lender’s requirements

  • The time needed for legal work

  • Moving arrangements

  • Any agreed work before closing

  • The seller’s proposed timing

A date that looks convenient on a calendar may create difficulties elsewhere.

For example, buying before your existing home sells may raise financing questions. Closing on the same day as your sale can create its own coordination challenges.

Explain your circumstances before the date is written into the offer.

Also clarify possession arrangements. Don’t assume that you can arrive with a moving truck first thing in the morning simply because it is closing day.


Rural home with a private well and outbuilding to investigate before purchase

Conditions Should Address Your Actual Needs

An offer can include conditions allowing you to investigate matters before committing to proceed without those protections.

Depending on the property and your circumstances, those matters may include financing, insurance, a home inspection, document review or additional testing.

The important question is:

What must I learn or arrange before I’m comfortable completing this purchase?

A private water supply may call for different investigation than municipal water.

A leased-land property may require information that doesn’t arise with a conventional freehold home.

If your purchase depends on selling your existing property, discuss that before preparing the offer.

Conditions and their wording should be selected for the transaction, with professional advice where needed. The appropriate agreement may include property-specific schedules. NSREC’s guide to real estate forms


Allow Enough Time to Do the Work

A condition deadline is only useful if the necessary work can realistically happen before it.

Before proposing a short timeline, consider whether you can:

  • Book the appropriate inspector

  • Arrange any specialist visits

  • Receive laboratory results

  • Supply documents to your lender

  • Obtain insurance information

  • Have your lawyer review the agreement

A routine inspection appointment and a structural engineer’s investigation may involve very different availability.

Weekends, holidays, travel and access to the property can also affect scheduling.

Choose a timeline that allows you to make an informed decision.


The Seller’s Response Deadline Is a Different Deadline

The offer includes a date and time until which it is open for acceptance.

That is separate from the deadline for investigating buyer conditions and from the closing date. The standard Nova Scotia form specifies Atlantic Time for the seller’s response. NSREC’s May 2026 standard forms

When discussing the offer, make sure everyone is clear about which deadline they mean.

This is particularly useful when buyers are travelling or signing from another time zone.

Avoid thinking of every date simply as “the deadline.” Each one has a different purpose.


What Can the Seller Do With Your Offer?

The seller can accept, reject, counter or choose not to respond.

A counteroffer proposes changes. It might involve price, dates, inclusions or other terms.

You then need to evaluate the counteroffer as a whole before deciding whether to accept it. NSREC’s explanation of offers and counteroffers

For example, a seller might move closer to your price while proposing an earlier closing.

The price may work for you, but the new date may not.

Read every change rather than concentrating only on the number.

And don’t assume there will always be another round of negotiation. Prepare each offer with a clear understanding of what you would be agreeing to if it were accepted.


A Strong Offer Is More Than a High Price

Price matters, but buyers and sellers can have different priorities.

One seller may need time to arrange their move.

Another may value an earlier closing.

A buyer may be flexible about possession but need sufficient time for property investigations.

Understanding those priorities can help identify terms that work for both parties.

That doesn’t mean giving up something important just to make an offer look attractive.

Flexibility is useful when it fits your circumstances.

It is less useful if it creates financing problems, rushed investigations or a moving arrangement you cannot manage.


What If There Are Competing Offers?

Competition can make an already significant decision feel more urgent.

Before changing your offer, revisit your own limits:

What is the highest price you’re comfortable paying?

Which investigations remain important?

Can you actually meet the proposed dates?

Would you be comfortable owning the property on these terms?

In Nova Scotia, the seller decides whether the existence of competing offers is disclosed. Don’t assume every competing-offer situation will provide the same information. NSREC’s competing-offer guidance

There is no universal strategy that guarantees success.

The goal is to make a considered purchase you can complete and live with comfortably.


Buyer carefully reviewing an offer before signing

Read the Entire Offer Before Signing

By the time an offer is ready, you may already have discussed its major points several times.

Read it anyway.

Check the names, property information, price, deposit, dates, inclusions, exclusions and attached schedules.

Pay particular attention to anything written specifically for your purchase.

Does it say what you intended?

Does it require something you can actually do?

Is an important concern missing?

If you’re signing electronically, take time to read the document before moving through the signature fields.

Understanding the agreement is part of making the offer.


Your Offer Was Accepted—Now Start the Next Stage

Acceptance means it is time to act on the agreement.

Organize the deposit payment, send the documents to the appropriate professionals and begin the investigations you’ve agreed to complete.

Arrange your home inspection promptly.

If something needs further evaluation, give yourself time to understand it before deciding how to proceed.

Keep a clear record of the dates and who is handling each task.

An accepted offer can feel like the biggest moment in the purchase, but much of the practical work still lies ahead.


Satisfying Conditions Requires the Correct Notice

For buyer conditions requiring Form 408, being satisfied is not enough by itself. The buyer must provide the seller or seller’s representative with the completed form waiving all applicable conditions by the agreed deadline.

Otherwise, the agreement is deemed terminated.

Other clauses—including the standard lawyer-review and title-investigation clauses—use different notice procedures. Follow the wording of your actual agreement. NSREC’s guidance on Form 408 and buyer conditions

This is why a general statement such as “everything is fine” should never replace checking what the contract requires.


What If an Investigation Reveals a Problem?

A finding may lead to further investigation or a proposed amendment.

For example, you might request a repair, price adjustment or additional time. The seller does not have to agree.

Proposing a change does not pause the original condition deadline. Unless an amendment is accepted in time to change it, that deadline remains in effect. NSREC’s guidance on amendments and condition deadlines

The Inspection Found Problems — What Happens Next? explores that stage in more detail.

For the offer itself, the lesson is straightforward: allow appropriate investigation and enough time to decide what the results mean to you.


Maintained detached home in an established residential neighbourhood

Make an Offer You Understand

A well-considered offer brings several decisions together.

The property you want to buy.

The price you’re comfortable paying.

The information you still need.

The items you expect to receive.

The dates you can meet.

The responsibilities you’re prepared to accept.

When those things are clear, negotiation becomes easier to evaluate. You can consider each response against your priorities instead of reacting only to the excitement or pressure of the moment.

The best starting point is an offer that accurately reflects what you want to buy—and the terms on which you’re prepared to buy it.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

The Inspection Found Problems — What Happens Next?

A home inspection rarely ends with the inspector saying, “Everything is perfect.”

Homes have maintenance items, aging components, previous repairs and defects. Even a well-maintained property will usually produce an inspection report containing observations and recommendations.

So the important question isn't whether the inspector found something.

It's:

What was found, how significant is it, and does it change your decision about buying the property?

When an inspection uncovers a concern, the next step is to understand the issue before deciding what—if anything—you want to do about it.


Finding a Problem Doesn't Automatically Mean the House Is a Bad Buy

An inspection report can look intimidating.

Several pages of observations, photographs and recommendations can make a house appear much worse on paper than it did during the showing.

But an inspection report isn't a pass-or-fail test.

A loose railing, aging roof, active plumbing leak and major foundation concern might all appear in the same report, but they don't carry the same significance.

Some findings are ordinary home maintenance.

Some are repairs you may want to budget for.

Some need further investigation.

And occasionally, an issue is significant enough to change whether you're comfortable buying the property at all.

The job after the inspection is to separate those categories rather than react to the length of the report.


Start With the Findings That Matter Most

When reviewing the inspection, it can help to concentrate first on concerns involving:

  • Safety

  • Active water intrusion

  • Structural issues

  • Major building systems

  • Significant deterioration

  • Problems that could affect insurance

  • Issues that could affect financing

  • Repairs that may involve substantial expense

  • Conditions that require specialist investigation

  • Something materially different from what you reasonably expected when making the offer

Cosmetic imperfections and routine maintenance still matter because you'll own them after closing.

But they don't necessarily deserve the same attention as an active roof leak, unsafe electrical condition or failing heating system.

Prioritize before you negotiate.

Home inspector explaining a significant property concern to a buyer

Make Sure You Understand What the Inspector Actually Said

Inspection reports often use cautious language.

An inspector might identify evidence of moisture, movement, deterioration or an installation that appears unusual and recommend further evaluation.

That doesn't necessarily mean the inspector has diagnosed the cause.

Before deciding what to do, make sure you understand:

What did the inspector observe?

Why does it matter?

Is the problem active or historical?

Does the inspector know the likely cause?

How urgent is it?

Is further investigation recommended?

If you're uncertain, talk to the inspector.

The conversation after the inspection can be just as valuable as the written report.


Sometimes the Next Step Is Another Inspection

A general home inspector identifies many conditions, but some questions require specialized expertise.

If the inspection reveals a potentially significant issue, the appropriate next step may be to bring in another professional.

Depending on the concern, that could mean:

  • A licensed electrician

  • A plumber

  • A heating or HVAC technician

  • A roofer

  • A structural engineer

  • A foundation specialist

  • A septic professional

  • A well professional

  • A WETT-certified professional

  • Another appropriately qualified specialist

The purpose is to turn an uncertain observation into better information.

For example, “possible structural movement” is difficult for a buyer to evaluate.

A qualified professional may be able to determine whether the condition is minor, historical, actively moving or something requiring substantial corrective work.

Better information usually leads to a better decision.

Specialist investigating a concern identified during a home inspection

Don't Guess at Repair Costs

Once buyers see a problem, one of the first questions is usually:

How much will that cost to fix?

Sometimes there is an obvious answer.

Often there isn't.

A home inspector may be able to explain the nature of a problem, but that doesn't necessarily mean they should be expected to provide an exact repair estimate.

If the cost could materially affect your decision, consider obtaining information from the professional who would actually perform or specify the work.

A contractor may see a different scope once finishes are removed.

A roofer may discover that decking needs replacement.

An electrician may find that what appeared to be a small repair involves a larger part of the system.

A foundation specialist may recommend monitoring rather than major work—or the opposite.

When the number matters, try to base your decision on something more reliable than a guess.

Contractor evaluating a repair identified during a home inspection

A Repair Estimate Isn't Always a Final Price

Even a contractor's estimate has limitations.

Some problems can't be fully understood until work begins.

Water damage may extend farther than the visible stain.

Rot may be concealed behind siding.

A leaking shower may have damaged framing below.

An older electrical system may contain alterations that aren't visible until work starts.

That doesn't make estimates useless.

It means buyers should understand the difference between:

“This appears to be the likely cost based on what we can currently see”

and

“This is guaranteed to be the total cost.”

That distinction becomes especially important when you're deciding how much financial risk you're comfortable accepting.


You Don't Have to Ask the Seller to Fix Everything

An inspection isn't automatically a list of repairs for the seller.

A used home isn't expected to become a new home simply because it was inspected.

You may decide that many findings are ordinary ownership items you're comfortable taking on yourself.

A better question is:

Which findings materially change what I believed I was buying?

That helps keep the focus on significant concerns rather than every loose handle, worn finish or maintenance item in the report.


What Options Does a Buyer Have After an Inspection?

If your purchase is subject to a property-inspection condition and the inspection identifies problems, what happens next depends on the wording of your Agreement of Purchase and Sale, the findings, your condition deadline and what you're comfortable accepting.

In Nova Scotia, NSREC explains that when a buyer isn't satisfied with a condition but still wants to proceed, the buyer can propose an amendment to try to resolve the issue. A seller isn't required to accept that proposal.

Broadly, a buyer might decide to:

  • Accept the property as it is and proceed

  • Seek additional information before deciding

  • Propose that the seller complete a specific repair

  • Propose a change to the purchase price

  • Propose another solution appropriate to the issue

  • Propose additional time for further investigation

  • Decide not to proceed if the buyer remains unsatisfied with the applicable condition

The right approach depends on the property, the contract and the buyer's priorities.

There isn't one response that makes sense for every inspection finding. Nova Scotia Real Estate Commission


Asking for a Repair Is a Negotiation

Finding a defect doesn't automatically obligate the seller to repair it.

If a buyer proposes an amendment because of an inspection concern, the seller can accept it, reject it, ignore it or propose a different amendment.

If an amendment is accepted, its terms become part of the agreement.

If it isn't accepted, the original terms and deadlines remain in effect. Nova Scotia Real Estate Commission

That's important because buyers sometimes assume that once a problem is discovered, the next step is simply deciding how the seller will fix it.

It isn't.

The inspection provides information. What happens with that information may become a negotiation.


Repair, Price Reduction or Another Solution?

Different problems can lend themselves to different approaches.

Suppose the inspection reveals an active plumbing leak.

A buyer may prefer to have the leak professionally repaired before closing because allowing it to continue could cause additional damage.

Now suppose the roof is nearing the end of its useful life.

A buyer might prefer to take responsibility for replacing it after closing rather than having the seller choose the contractor and scope of work.

In another situation, the buyer and seller may agree to a change in price.

There is no universal rule that says a repair is better than a price adjustment—or the other way around.

Consider:

  • How urgent is the problem?

  • Could it worsen before closing?

  • Who should perform the work?

  • Does the buyer want control over the repair?

  • Does the issue affect insurance or financing?

  • Can the work reasonably be completed before closing?

  • Is the proposed solution clearly documented?

The nature of the problem should help shape the solution.

Home buyers discussing options after receiving an inspection report

A Price Reduction Doesn't Put the Same Amount of Cash in Your Pocket

This is an important distinction.

If the purchase price is reduced by $10,000, that doesn't necessarily mean the buyer has an extra $10,000 available after closing to complete repairs.

Depending on the financing arrangement, much of that reduction may simply reduce the amount being borrowed.

If you're considering a price reduction because you expect to complete substantial work after closing, discuss the financing implications with your mortgage professional.

Purchase price and available renovation cash aren't the same thing.


Be Specific About Agreed Repairs

If the buyer and seller agree that work will be completed before closing, vague wording can create problems.

“Repair roof.”

“Fix electrical.”

“Repair leak.”

Those phrases can leave plenty of room for disagreement about what was actually promised.

The agreement should make the required outcome as clear as reasonably possible.

Depending on the situation, that could include matters such as:

  • The specific problem being addressed

  • Who is qualified to perform the work

  • Whether invoices or receipts are to be provided

  • When the work must be completed

  • Whether further documentation is required

Your REALTOR® can prepare the appropriate real-estate documentation, while technical specifications should come from the qualified professional where necessary.

The goal is for everyone to understand what has actually been agreed to.


Think Carefully Before Asking a Seller to Complete a Major Renovation

Sometimes a buyer would rather receive an appropriate negotiated adjustment and control the work after closing.

Why?

Because the buyer will be living with the repair.

If a roof needs replacing, the buyer may care about the contractor, materials, warranty and timing.

If a basement requires significant work, the buyer may want to coordinate it with future renovations.

If an older heating system needs replacement, the buyer may want to choose a completely different type of system.

Seller-completed work can make sense, particularly when a problem must be corrected before closing.

But “seller to repair” isn't automatically the best solution simply because it sounds convenient.


Some Problems Affect More Than the Repair Budget

An inspection finding may have consequences beyond the cost of fixing it.

Consider a problem involving:

  • An oil tank

  • A wood-burning system

  • Electrical wiring

  • A roof in poor condition

  • Significant water damage

  • A failed septic system

  • Structural concerns

The issue may affect whether an insurance company will insure the property.

It may affect financing.

It may require another professional.

It may affect whether the property is suitable for the buyer's intended use.

So before reducing every problem to a repair estimate, ask whether it creates another condition that also needs to be satisfied.

Roof condition being evaluated after a home inspection

Insurance Should Be Considered Before You Waive Conditions

If an inspection reveals something that could affect insurability, contact your insurance provider before deciding how to proceed. For a closer look at the property features that can complicate coverage, read my guide to home insurance when buying in Nova Scotia.

Don't assume you'll sort it out after closing.

Your insurer may want more information.

It may require a repair.

It may have conditions for coverage.

Or the issue may not create a problem at all.

The important thing is to find out while you still have the opportunity to make an informed decision under the terms of your agreement.


Financing Can Also Be Affected

Some inspection findings can intersect with mortgage financing.

A lender may have concerns about the condition or marketability of a property, particularly if another part of the financing process—such as an appraisal—identifies the issue as well.

If a substantial defect is discovered, keep your mortgage professional informed when appropriate.

And remember that a mortgage pre-approval isn't final approval of every property you might decide to buy.

The buyer must qualify.

The property also has to work for the financing.


What If the Seller Says No?

A buyer proposes a $15,000 price reduction.

The seller says no.

What happens?

The original agreement doesn't automatically change.

Under NSREC's current process, the seller may accept, reject or ignore the proposed amendment, or propose a different amendment. If the amendment isn't accepted, the original Agreement of Purchase and Sale remains in effect, including the original buyer-condition deadline. Nova Scotia Real Estate Commission

The buyer then has to decide what to do within the rights and timelines provided by the agreement.

That could mean proceeding under the original terms if satisfied.

It could mean considering a different negotiated solution.

Or, if the buyer remains unsatisfied with an applicable buyer's condition, it could mean not proceeding.

Making a request and having that request accepted are two different things.

Buyer reviewing inspection options with a real estate professional

The Clock Doesn't Stop Because You're Negotiating

This is one of the most important practical points.

If you're negotiating an inspection issue, your original condition deadline still matters unless an amendment changing that deadline has been accepted.

NSREC specifically advises that an amendment related to buyer conditions should be submitted early enough that the seller's response deadline occurs before the original buyer-condition deadline. That gives the buyer time to decide what to do if the seller doesn't accept the proposal. Nova Scotia Real Estate Commission

Waiting until the final moments can unnecessarily limit your options.

If further investigation is needed, start arranging it as soon as possible.

If you're considering an amendment, don't treat the condition deadline as though it has been paused.


What If You Need More Time?

Sometimes the inspection raises a question that can't reasonably be answered before the original deadline.

Perhaps a structural engineer isn't available for several days.

Maybe you're waiting for a contractor.

Perhaps a laboratory result hasn't arrived.

A buyer can propose an amendment requesting an extension of the buyer-condition deadline.

But again, it is a proposal.

The seller has to agree to the extension for the deadline to change.

Until an extension is accepted, the original deadline remains the deadline. Nova Scotia Real Estate Commission


Satisfied With the Inspection? Form 408 Still Matters

In Nova Scotia, being satisfied with your inspection isn't the end of the process.

For the buyer's conditions in the standard Agreement of Purchase and Sale that use the current satisfaction process, the buyer must provide Form 408: Buyer Waiver of Conditions confirming satisfaction and waiving the applicable conditions on or before the agreed deadline.

If all applicable conditions aren't properly waived by the deadline, the agreement is deemed terminated. Nova Scotia Real Estate Commission

That's why condition deadlines aren't administrative details.

They're part of the contract.


What If You're Not Comfortable Proceeding?

Sometimes additional investigation answers the question.

Sometimes a negotiated solution makes the buyer comfortable.

And sometimes the information changes the buyer's view of the property.

Under the standard Nova Scotia buyer-condition process, if a buyer determines before the condition deadline that they aren't satisfied with an applicable condition, the buyer may terminate in accordance with the agreement. If the buyer doesn't provide the required Form 408 waiving the applicable buyer conditions by the deadline, the agreement is deemed terminated. Nova Scotia Real Estate Commission

The exact rights and obligations depend on the agreement you've signed, so this isn't an area for assumptions.

Review the situation and the contract with your REALTOR®, and obtain legal advice when appropriate.


Don't Let the Deposit Become an Afterthought

If an agreement terminates, that doesn't necessarily mean a deposit sitting in a brokerage trust account is simply handed back immediately.

NSREC's current guidance explains that where trust funds are being held, their release is subject to its by-laws. The brokerage must continue holding the funds until the parties provide the required written direction or a court orders their disbursement. Form 440 can be used for a termination and release of deposit. Nova Scotia Real Estate Commission

For most buyers, the important takeaway is simple:

Follow the proper process rather than assuming the money automatically moves when the transaction terminates.


The Property Disclosure Statement Is Part of the Picture—Not a Replacement for Inspection

If the seller provided a Property Disclosure Statement (PDS), compare relevant inspection findings with what was disclosed.

The PDS records information based on the seller's knowledge of the property. NSREC describes it as a starting point for conversation and further investigation—not a substitute for independent inspection. Nova Scotia Real Estate Commission

Sometimes an inspection finding may lead to another question for the seller.

Perhaps there is evidence of a previous leak.

Maybe the inspector sees a repaired foundation crack.

Perhaps there are signs that a system was replaced or modified.

Your REALTOR® can ask appropriate follow-up questions through the seller's representative.


A Defect Discovered During Inspection Isn't Automatically a Disclosure Problem

This distinction matters.

A home inspection may discover something the seller genuinely didn't know about.

NSREC distinguishes between visible—or patent—defects and material latent defects that can't be identified through reasonable inspection. Sellers are required to disclose known material latent defects, but discovering a problem during an inspection doesn't by itself prove that the seller knew about it or failed to disclose it. Nova Scotia Real Estate Commission

If a significant issue raises legal questions about disclosure or representation, that's something to discuss with your lawyer.

Don't jump from:

“The inspector found a problem”

to

“The seller hid a problem.”

Those are very different conclusions.


Don't Lose Sight of the Whole House

Inspection negotiations can sometimes become so focused on one finding that buyers forget why they wanted the property in the first place.

Suppose a house needs a $7,000 repair.

That's significant.

But whether it changes the purchase decision depends on the property, the purchase price, your budget, your plans and what else you've learned.

Conversely, a problem doesn't have to carry a huge repair estimate to matter.

A recurring water issue may concern you because of how you intend to use the basement.

A wood-burning system may matter because your insurer won't accept it in its present condition.

A private road issue may affect your intended year-round use.

The decision isn't simply:

“How much does the repair cost?”

It's:

“Knowing what I know now, am I still comfortable buying this property on the terms available to me?”


Avoid Negotiating Just Because You Can

An inspection condition is there to help a buyer investigate the property and make an informed decision.

It shouldn't turn into an automatic second round of bargaining over every maintenance item.

A focused response is often much more useful.

Identify the issues that genuinely matter.

Understand them.

Get additional information where necessary.

Then decide whether you are comfortable proceeding, whether a reasonable amendment would address your concern or whether the information changes your decision about the property.

That keeps the inspection process centred on risk and informed decision-making, rather than treating the report as a shopping list.


Keep Your Long-Term Plans in Mind

Sometimes an inspection finding overlaps with work you were already planning.

If you intended to renovate the kitchen, some older plumbing may be less concerning because you already expected to change it.

If you planned to replace an older heating system, its remaining lifespan may simply become part of that budget.

If you wanted to finish the basement, moisture management may suddenly become much more important.

The same physical condition can matter differently to different buyers.

That's why inspection decisions should reflect your plans for the property, not just the existence of a defect.


What Should You Do After the Inspection Finds Problems?

A practical sequence is:

  1. Understand the finding. Talk to the inspector if anything is unclear.

  2. Prioritize it. Separate significant concerns from routine maintenance.

  3. Investigate further if necessary. Bring in the appropriate specialist.

  4. Understand the likely cost and implications. Consider repairs, insurance, financing and future plans.

  5. Review your condition deadline. Know exactly how much time you have.

  6. Decide what outcome would make you comfortable.

  7. Discuss your options with your REALTOR®.

  8. Document any agreed change properly.

  9. Complete the required condition process before the deadline.

The order matters.

Understand first. Negotiate second.

Buyer taking a closer look at a home after the inspection

The Inspection Isn't About Winning or Losing

It's easy for an inspection negotiation to become emotional.

The buyer may feel the seller should fix something.

The seller may feel the home was priced with its age and condition in mind.

Neither perspective changes the physical condition of the property.

The most productive question is usually:

What information do we now have, and what does the buyer need in order to make a comfortable decision?

Sometimes that results in a repair.

Sometimes a price change.

Sometimes no change at all.

And sometimes the buyer decides the property isn't the right one.

A successful inspection process isn't one where the buyer gets the largest concession.

It's one where the buyer reaches the condition deadline with enough information to make an informed decision about the home they're buying.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.
Read

Beyond the Home Inspection: Tests and Investigations a Buyer May Need

A home inspection can tell you a great deal about a property.

But it doesn't answer every question.

Some parts of a home require specialized knowledge, equipment, laboratory testing or access that falls outside the scope of a standard home inspection. Other concerns may only become apparent after the inspector identifies something that deserves a closer look.

This is particularly relevant in Nova Scotia, where a property may have a private well, septic system, wood heat, an oil tank or other features requiring their own investigation.

The goal isn't to order every test available.

It's to figure out which investigations make sense for the particular property you're considering buying.


Start With the Home Inspection—Then Follow the Evidence

For many buyers, the general home inspection is the starting point.

A home inspector looks at the visible and accessible components of the property and may identify areas that deserve additional investigation.

That could mean an electrician examining a concern at the electrical panel.

It could mean a heating technician evaluating a boiler.

It could mean a structural engineer looking at unusual foundation movement.

Or the property itself may have features—such as a private well or septic system—that you planned to investigate separately from the beginning.

Think of due diligence as a process.

The first investigation may answer some questions while showing you which questions still need answers.


Not Every Property Needs the Same Due Diligence

A newer subdivision home on municipal water and sewer presents a different set of questions from a 150-year-old rural property with a drilled well, septic system, wood stove and several outbuildings.

A waterfront cottage presents different questions again.

So does vacant land.

So does a house that has undergone extensive renovations.

This is why a checklist can only take you so far.

Your due diligence should respond to the property, its systems, its history and what you intend to do with it.


Private Well Water Should Be Tested

If the property has a private well, don't assume clear, odourless water means the water is safe.

Nova Scotia says more than 40% of households obtain their drinking water from private wells and recommends regular testing for both bacteria and chemical contaminants. The province specifically notes that you can't determine whether well water is safe based on its appearance, smell or taste. Government of Nova Scotia

For ongoing ownership, Nova Scotia recommends testing well water at least annually for bacteria and every five years for chemical contaminants. Government of Nova Scotia

During a real estate purchase, water testing can help you understand the water supply before you take ownership.

Depending on the circumstances, testing may include:

  • Total coliform and E. coli

  • General chemistry

  • Metals

  • Arsenic

  • Uranium

  • Manganese

  • Other parameters appropriate to the property

Specific additional testing may make sense when there is a reason to suspect another source of contamination.

Nova Scotia identifies potential sources including petroleum products, septic systems, agricultural activity, road salt and other environmental influences. Government of Nova Scotia

Well water sample being collected for testing in a Nova Scotia home

Water Quality and Water Quantity Are Different Questions

A laboratory test tells you about water quality.

It doesn't necessarily tell you whether the well can consistently provide enough water for the household.

That's a different question.

If there are concerns about the well's capacity, history or performance, a buyer may want additional information about the well itself.

That could include looking for the well construction record, asking about previous shortages or having an appropriate professional evaluate the well or its yield.

A property can have perfectly acceptable water chemistry and still have a quantity issue.

Likewise, a productive well can still require water treatment.

Don't confuse the two.


A Water-Treatment System Doesn't Eliminate the Need to Understand the Water

Some homes have equipment to address particular characteristics or contaminants in the water.

You might see:

  • Sediment filters

  • Water softeners

  • UV treatment

  • Iron or manganese treatment

  • Reverse-osmosis equipment

  • Other filtration or treatment systems

Find out what the equipment is intended to treat.

Ask how it has been maintained.

And consider whether the water should be sampled in a way that helps you understand both the untreated source water and how effectively the treatment system is working.

The presence of treatment equipment isn't automatically a concern.

It's information about the property that you should understand.


A Septic System Deserves Its Own Inspection

A general home inspection shouldn't automatically be treated as a substitute for a dedicated septic-system inspection.

The Nova Scotia Real Estate Commission recommends that buyers have a septic system inspected before finalizing the purchase of a property with an on-site system. NSREC notes that an inspection may involve pumping the tank and examining the disposal field and that septic inspections may be conducted by appropriately qualified professionals such as licensed septic installers, licensed sewage haulers or professional engineers. Nova Scotia Real Estate Commission

A septic investigation may help answer questions such as:

  • Where is the tank?

  • Where is the disposal field?

  • What type of system is installed?

  • Is the system functioning as expected?

  • Are there visible signs of a problem?

  • When was the tank last pumped?

  • Is there available information about the system's installation or maintenance?

The appropriate scope depends on the property and the professional conducting the inspection.

Septic system being inspected at a Nova Scotia property

Don't Assume a Working Toilet Means the Septic System Is Fine

A septic problem isn't always obvious during a showing.

The sinks may drain.

The toilets may flush.

There may be no noticeable odour.

That doesn't provide the same information as an appropriate investigation of the septic system.

This is especially important because the system is largely underground.

A buyer should understand that what happens inside the house is only one part of the wastewater system.


Radon Requires Testing

Radon is another issue you can't evaluate simply by looking at the house.

Nova Scotia advises that testing is the only way to know the radon level in an individual home. Long-term testing is the preferred approach, with Health Canada recommending a testing period of at least three months. Nova Scotia Real Estate Commission

That creates an obvious challenge during many real estate transactions: the condition period may be much shorter than the recommended long-term testing period.

That doesn't mean radon should be ignored.

It means buyers should understand what can realistically be determined before closing and what may need to become part of their ownership plan.

Radon isn't simply an “old house” issue, either.

Testing is what determines the level in a particular home.


Wood Stoves and Fireplaces May Need a Specialized Inspection

Wood heat is common enough in Nova Scotia that buyers will regularly encounter wood stoves, fireplaces and other solid-fuel-burning systems.

A general home inspector may observe the system, but an inspection by a WETT-certified professional may be requested or appropriate—particularly for insurance or when evaluating the installation itself.

WETT says solid-fuel systems are inspected for reasons including real estate transactions, insurance requirements and concerns about system performance. It also uses different SITE inspection levels depending on accessibility and the depth of investigation required. Wettinc

There's an important terminology distinction here:

The stove itself isn't “WETT certified.”

WETT certifies individuals. A WETT-certified professional can inspect the wood-burning system and issue an inspection report. Wett Inc.

If you're buying a property with wood heat, it's also worth discussing the system with your insurance provider early in the process.

Wood-burning system being inspected in a Nova Scotia home

An Oil Tank May Need More Than a Quick Look

A home inspector may note the location, apparent condition and visible characteristics of a heating-oil tank.

But sometimes further investigation is appropriate.

An oil-heating system includes more than the tank itself. Tank condition, installation, fuel lines, corrosion, evidence of leakage and other factors can all matter.

Nova Scotia's guidance on domestic heating-oil tanks recommends having a heating-service professional conduct a more detailed examination when an evaluation raises concerns about the system. Government of Nova Scotia

Insurance can matter here as well.

If you're buying a property heated by oil, provide the relevant information to your insurer rather than assuming the system will automatically meet its underwriting requirements.

Heating oil tank being evaluated in a residential basement

Electrical Concerns May Need an Electrician

A home inspector may identify electrical concerns during the general inspection.

Sometimes the observation is straightforward.

Other times, it raises a question that should be answered by a licensed electrician.

That might happen when there are concerns about:

  • An electrical panel

  • Older wiring

  • Improper alterations

  • Unusual connections

  • Renovated areas

  • Insufficient electrical capacity for planned improvements

  • Other visible conditions identified during the inspection

The distinction is important.

The home inspector helps identify a potential concern.

The electrician can investigate the electrical issue in greater depth and advise on what work, if any, is appropriate.


Heating Equipment May Need a Heating Professional

The same principle applies to heating and cooling equipment.

A general inspection may identify the approximate age, visible condition or operation of a furnace, boiler, heat pump or other equipment.

But if the equipment isn't operating properly—or if its condition is important to your purchasing decision—you may want an HVAC or heating professional to evaluate it.

This can be particularly useful when the system is older, appears poorly maintained or shows signs of leakage, unusual operation or previous repair.

It can also help when you're trying to understand whether an existing system can reasonably support renovations or changes you intend to make.


Structural Concerns May Require an Engineer

Cracks aren't all the same.

Neither are sloping floors.

Neither are sagging roofs, altered framing or foundation movement.

A home inspector may identify something that appears unusual without being able to determine the underlying cause or its structural significance.

That's where further investigation can become valuable.

Depending on the concern, a structural engineer or other appropriately qualified professional may be able to evaluate the condition and help determine whether it represents ordinary movement, a previous repair, an active problem or something requiring corrective work.

The objective isn't to panic every time a crack appears.

It's to get the right expertise when the answer matters.

Foundation concern being evaluated by a building professional

Moisture Problems Sometimes Need More Investigation

Water staining tells you that water has been there.

It doesn't always tell you:

  • Where the water came from

  • Whether the source has been repaired

  • Whether the problem is still active

  • What may be concealed behind the finished surface

  • How extensive any resulting damage may be

An inspector may use visible evidence and moisture readings to help evaluate the situation within the scope of the inspection.

But significant or unexplained moisture can justify additional investigation.

That might involve a roofer, plumber, foundation contractor, building professional or another specialist depending on the suspected source.

The right specialist depends on the problem.


A Sewer Line Can Be a Separate Question

On a property connected to municipal sewer, the plumbing inside the house isn't necessarily the end of the investigation.

The lateral connecting the home to the municipal system can be another consideration.

A sewer camera inspection may sometimes be worth considering—particularly where there are signs of drainage problems, a history of backups, older buried piping, mature trees near the route or another reason to question the condition of the line.

This isn't something every buyer needs to order.

It's another example of property-specific due diligence: investigate further when the property gives you a reason to ask the question.


Renovations Can Raise Questions Beyond Physical Condition

A beautifully renovated kitchen can look excellent during an inspection.

But a home inspection doesn't necessarily establish the permit or approval history of the work.

If a property has undergone significant alterations, buyers may want to understand what was changed and what documentation is available.

This can be particularly relevant for work involving:

  • Additions

  • Structural changes

  • Finished basements

  • New bedrooms or living spaces

  • Electrical work

  • Plumbing changes

  • Decks

  • Secondary suites

  • Major renovations

The appropriate municipal requirements depend on the property, location and work involved.

If the status of renovations matters to your purchase, investigate it rather than assuming that attractive finished work tells you everything about how it was completed.


Property Boundaries Aren't Determined by the Lawn

A fence isn't necessarily on the boundary.

A driveway isn't necessarily entirely within the property.

A shed that appears to belong to the house isn't proof of where the legal property line runs.

And a row of trees isn't a survey.

If boundaries matter to your purchase, additional investigation may be appropriate.

This becomes especially important when you're buying because of a particular feature:

  • A large yard

  • Waterfront access

  • A driveway

  • Space for a future garage

  • A detached building

  • Room for an addition

  • Access to another part of the property

Your lawyer and REALTOR® can help identify what information is available and when a surveyor or other professional may be appropriate.

Property boundary being investigated before a home purchase

Access Can Matter Just as Much as Boundaries

Some Nova Scotia properties aren't accessed from a straightforward municipal road frontage.

You may encounter:

  • Shared driveways

  • Rights-of-way

  • Private roads

  • Easements

  • Shared maintenance arrangements

  • Access crossing another parcel

Being able to physically drive to a property doesn't, by itself, explain the legal rights and obligations associated with that access.

Questions about title, easements and legal access belong with your lawyer.

Questions about road condition, maintenance and practical use may require additional investigation as well.

This can be particularly important if year-round access, snow clearing or future financing depends on the arrangement.


Waterfront Property Creates Additional Questions

A waterfront home can require due diligence beyond the building itself.

Where exactly is the boundary?

Is the shoreline changing?

Are there erosion concerns?

How is the property accessed?

Where are the well and septic system in relation to the water?

What restrictions could affect future work near the shoreline?

Are docks, retaining structures or other waterfront improvements relevant to the purchase?

The view may be what first attracts you to the property.

Your investigation should focus on what owning that particular waterfront property actually involves. I cover these considerations in Buying Waterfront Property in Nova Scotia: What Should You Investigate?


Outbuildings Shouldn't Automatically Be Ignored

Garages, barns, workshops and other outbuildings can be a major part of a property's value to a buyer.

But the scope of a standard home inspection may not necessarily include every structure on the property in the same way as the house.

If an outbuilding matters to your decision, establish whether it is included in the inspection and what the inspector will evaluate.

A large barn you're counting on for animals, a workshop you plan to use every day or a detached garage supporting your purchase decision deserves appropriate attention.

Don't discover afterward that the structure you cared about wasn't part of the inspection you ordered.


Environmental Concerns Are Property-Specific

Most residential purchases don't require an exhaustive environmental investigation.

But certain properties or observations can create reasons to ask additional questions.

Examples might include:

  • Evidence of a previous fuel leak

  • Unusual tanks or containers

  • Former commercial or industrial use

  • Suspected contaminated soil

  • Nearby activities that create a specific concern

  • Other information discovered during due diligence

The appropriate investigation depends heavily on the circumstances.

This is an area where specialist environmental advice may be necessary rather than relying on assumptions.


Your Insurance Company Is Part of the Due-Diligence Process Too

A property can be physically acceptable to you and still raise questions for an insurer.

Depending on the home, an insurance company may want information about things such as:

  • Electrical systems

  • Heating equipment

  • Oil tanks

  • Wood-burning systems

  • Roof condition

  • Plumbing

  • Property occupancy

  • Other characteristics of the home

Don't wait until the day before closing to discover that your insurer needs information you don't have.

Starting the insurance conversation early gives you more time to determine whether additional inspections, reports or upgrades are required.


Your Lender May Also Require Information

Financing and property due diligence sometimes overlap.

NSREC notes, for example, that a financial institution may request a septic-system inspection. Nova Scotia Real Estate Commission

A lender may also have questions about a property's condition, appraisal, intended use or characteristics before final mortgage approval.

That's another reason not to assume that mortgage pre-approval means every property will automatically qualify.

The borrower matters to the lender.

So does the property being financed.


Specialists Answer Different Questions

One of the easiest mistakes during due diligence is asking the wrong professional to answer a question outside their area of expertise.

A REALTOR® isn't a structural engineer.

A home inspector isn't necessarily an electrician.

An electrician isn't a surveyor.

A surveyor isn't a septic installer.

Your lawyer isn't conducting the physical home inspection.

Each professional has a different role.

Part of good due diligence is recognizing which question you're trying to answer and who is qualified to answer it.


More Testing Isn't Automatically Better

It's possible to turn due diligence into an endless search for absolute certainty.

No investigation can guarantee that a house will never develop a problem.

The objective is to make reasonable, informed decisions based on the property and the information available.

Ask yourself:

What do I already know?

What don't I know?

Does the unanswered question materially affect my decision?

Who can give me the best information about it?

That approach is much more useful than ordering every conceivable test simply because it exists.


Leave Enough Time for Follow-Up

This is one of the practical reasons to think about due diligence early.

If your home inspection identifies a concern near the end of your condition period, you may need time to arrange another professional.

A specialist may not be available the same day.

Laboratory results may take time.

A contractor may need access to the property.

Additional information may need to be obtained.

In a Nova Scotia transaction, the Agreement of Purchase and Sale establishes deadlines for the buyer's conditions. NSREC confirms that buyers must complete their due diligence and provide the required written waiver of applicable conditions by the agreed deadline if they're satisfied; otherwise the agreement is deemed terminated. Nova Scotia Real Estate Commission

Know your deadlines and plan accordingly.

Buyers reviewing property inspection and testing information

What Tests or Investigations Might a Buyer Consider?

There isn't one list that applies to every home.

Depending on the property, your investigation could involve some combination of:

  • General home inspection

  • Well-water testing

  • Well-yield or water-supply investigation

  • Septic-system inspection

  • Radon testing

  • WETT inspection of a wood-burning system

  • Heating or HVAC evaluation

  • Oil-tank or oil-heating-system evaluation

  • Electrical evaluation

  • Plumbing investigation

  • Structural evaluation

  • Roofing evaluation

  • Sewer camera inspection

  • Moisture investigation

  • Survey or boundary investigation

  • Permit or renovation-history research

  • Environmental investigation

  • Specialist evaluation of an outbuilding

  • Other property-specific investigation

That looks like a long list.

It isn't a recommendation to order all of them.

It's a reminder that “I had a home inspection” and “I completed my due diligence” aren't always exactly the same thing.


Let the Property Tell You What to Investigate

Good due diligence isn't about trying to eliminate every possible risk from home ownership.

That's impossible.

It's about identifying the questions that matter before you become responsible for the property.

A private well creates questions about water.

A septic system creates questions about wastewater.

A wood stove creates questions about the solid-fuel system.

A foundation crack may create a structural question.

A major renovation may create questions about permits or workmanship.

A shared driveway may create questions about legal access.

Follow those questions.

Use the general home inspection as an important starting point, bring in specialists where appropriate and make sure you understand the information you receive before your condition deadlines arrive.

The objective isn't to prove that the house is perfect.

It's to understand the property you're actually buying.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.
Read

Home Inspections in Nova Scotia: What Buyers Should Know

A home inspection is one of the most useful opportunities a buyer has to learn about a property before completing a purchase.

It can help you understand the condition of the home's major systems, identify visible problems, learn about maintenance that may be coming and determine whether anything deserves further investigation.

But a home inspection isn't a guarantee that nothing will ever go wrong.

It also isn't a pass-or-fail test.

The real value is information.

When you're buying a home in Nova Scotia, understanding what an inspection can tell you—and what it can't—can help you use that information much more effectively.


What Is a Home Inspection?

A home inspection is a professional examination of the visible and accessible components of a property.

The Nova Scotia Real Estate Commission strongly recommends that buyers have a home inspection and identifies property inspection as one of the common conditions included in an Agreement of Purchase and Sale. Nova Scotia Real Estate Commission

Depending on the property and the inspector's scope of work, the inspection may include major components such as:

  • Roof

  • Exterior

  • Structure and foundation

  • Plumbing

  • Electrical system

  • Heating and cooling

  • Interior

  • Attic

  • Insulation and ventilation

The purpose isn't to prove that everything is perfect.

It's to give you a better understanding of the property you're considering buying.


A Home Inspection Is Primarily a Visual Inspection

This is one of the most important things for buyers to understand.

A standard home inspection generally evaluates visible and accessible components of the home.

The Canadian Association of Home & Property Inspectors (CAHPI) describes its standard as a visual building inspection covering major systems and components. Its standards also make clear that this type of inspection isn't a verification that a property complies with every building code, regulation or insurance requirement. Cahpi

An inspector generally isn't opening finished walls to see the wiring behind them, excavating around the foundation or dismantling equipment to inspect every internal component.

That means there are limits to what any inspection can reveal.

A finished basement wall can conceal what is happening behind it.

Snow can prevent parts of a roof from being fully evaluated.

Stored belongings can block access.

An attic hatch may be inaccessible.

Understanding these limitations doesn't make the inspection less valuable. It helps you understand what the inspection actually represents.

Home inspector examining visible components of a house

A Home Inspection Isn't the Same as a Building-Code Inspection

Buyers sometimes expect a home inspector to determine whether every part of a house meets current building code.

That's not generally the purpose of a standard home inspection.

Building codes also change over time.

A house built decades ago wasn't necessarily constructed to today's requirements, and the presence of an older building component doesn't automatically mean that it must be upgraded simply because newer construction would be done differently.

An inspector may identify conditions that appear unsafe, unusual or worthy of further investigation.

But don't assume a standard home inspection provides formal certification that the entire property complies with current codes.

If a specific code, permit or compliance issue matters to your purchase, it may require investigation through the appropriate municipality, authority or qualified professional.


The Inspector Isn't There to Decide Whether You Should Buy the House

A home inspector provides information.

The buying decision remains yours.

An inspection report may contain dozens of observations, ranging from small maintenance items to significant concerns.

A long report doesn't automatically mean the house is bad.

Likewise, a short report doesn't guarantee that the property will never need repairs.

CAHPI describes the inspector's role similarly: the inspector provides information to help the buyer make a decision rather than making the purchasing decision for them. Cahpi

Your job is to understand which findings matter to you.


Choose the Inspector, Not Just the Inspection Company

Not every inspector has the same experience, qualifications or approach.

In Nova Scotia, the Real Estate Commission specifically notes that home inspectors are not regulated by the Commission and recommends confirming that the inspector carries Errors and Omissions insurance. Nova Scotia Real Estate Commission

When choosing an inspector, consider asking about:

  • Training and qualifications

  • Experience

  • Professional affiliations

  • Standards of practice followed

  • Errors and Omissions insurance

  • What is included in the inspection

  • What isn't included

  • Whether you'll receive photographs

  • How the findings will be reported

  • Whether you can attend

Price can certainly be part of the decision.

But when you're using an inspection to help evaluate a purchase worth hundreds of thousands of dollars, experience, scope and communication matter too.


Attend the Inspection If You Can

An inspection report is useful.

Walking through the property with the inspector can be even more useful.

Both the Nova Scotia Real Estate Commission and CAHPI encourage buyers to consider attending so they can ask questions and become more familiar with the property. Nova Scotia Real Estate Commission

During an inspection, you may be able to see:

  • Where the main water shutoff is

  • Where the electrical panel is

  • How the heating system operates

  • Where the attic access is

  • Which maintenance items should be monitored

  • What an inspector means when describing a particular concern

Something that sounds alarming in a written report may be easier to understand when the inspector shows it to you.

Conversely, seeing a problem in person can help you appreciate why the inspector considers it significant.

Home buyer attending a professional home inspection

Don't Turn the Inspection Into a Second Showing

Attending the inspection doesn't mean you need to follow the inspector every second.

Inspectors need room to work and concentrate.

Use the opportunity to learn about the house, but allow the inspector to follow their process.

There may also be areas you shouldn't enter because of safety, access or the inspector's own procedures.

A good approach is to ask the inspector how they prefer to communicate during the inspection.

Some explain findings as they go.

Others prefer to complete portions of the inspection before reviewing observations with the buyer.


What Does the Inspector Look at Outside?

The inspection begins before anyone enters the house.

Exterior conditions can provide important clues about what's happening inside.

Depending on accessibility, an inspector may look at areas such as:

  • Roof covering

  • Flashing

  • Chimneys

  • Gutters and downspouts

  • Exterior cladding

  • Windows and doors

  • Decks and porches

  • Foundation

  • Grading

  • Drainage

  • Visible structural components

Water management deserves particular attention.

Where does roof water go?

Does the ground slope toward or away from the foundation?

Are downspouts discharging beside the house?

Are there signs of deterioration where exterior materials meet?

Many interior moisture problems begin outside.

Inspector evaluating the exterior and drainage around a home

What Happens in the Basement or Crawlspace?

Basements can reveal a great deal about a house.

An inspector may be able to evaluate visible portions of:

  • Foundation

  • Framing

  • Support posts and beams

  • Plumbing

  • Electrical wiring

  • Heating equipment

  • Moisture conditions

  • Insulation

  • Drainage systems

In an older home, the basement may also show changes made over several generations.

New plumbing may run beside older plumbing. Structural repairs may be visible. Heating systems may have been replaced. An addition may have a different foundation from the original house.

Again, the goal isn't to expect everything to look new.

It's to understand what is there and whether anything warrants further investigation.


The Attic Can Be One of the Most Informative Areas

If the attic is accessible, it can provide information that isn't visible from the finished rooms below.

An inspector may look for things such as:

  • Roof structure

  • Evidence of previous leakage

  • Insulation

  • Ventilation

  • Visible electrical wiring

  • Chimney condition

  • Moisture or staining

  • Signs of pests

  • Alterations to framing

Access matters.

CAHPI notes that when components aren't accessible, the inspector may be unable to inspect them and should identify that limitation in the report. Cahpi

If an important area can't be inspected, ask what that means and whether any follow-up investigation makes sense.

Home inspector examining insulation and roof framing in an attic

Electrical Systems Deserve More Than a Quick Look at the Panel

The electrical panel is important, but it's only one part of the electrical system.

An inspector may look at visible wiring, receptacles, grounding, panels and other accessible components.

In older or renovated homes, electrical work may have been completed at several different times.

The inspection may identify something that should be evaluated by a licensed electrician.

That's an important distinction.

A home inspector is generally evaluating the overall property as a generalist. When a specific technical concern is identified, a specialist may be better positioned to determine exactly what is happening and what, if anything, needs to be done.

Electrical panel being examined during a home inspection

Plumbing Is More Than Checking Whether the Taps Work

Running the taps can provide useful information, but an inspection can go further.

Visible plumbing may be evaluated for:

  • Leaks

  • Corrosion

  • Drainage

  • Water pressure or flow concerns

  • Fixture operation

  • Water-heating equipment

  • Visible supply and waste piping

However, the inspector can't see every pipe hidden behind walls, ceilings or floors.

And if the property uses a private well or septic system, those systems may require their own testing or specialized inspections rather than relying on the general home inspection alone.


Heating and Cooling Systems Are Part of the Picture

Nova Scotia homes can use a wide variety of heating systems.

During an inspection, visible heating and cooling equipment may be evaluated for operation and apparent condition within the inspector's scope.

That might include:

  • Furnaces

  • Boilers

  • Heat pumps

  • Electric heating

  • Distribution systems

  • Visible fuel-related components

  • Thermostats

But a home inspector isn't necessarily an HVAC technician.

If the equipment has a problem, is unusually old or raises a specific concern, further evaluation by a qualified heating professional may make sense.

The same principle applies to many components of the house:

the inspection can identify the question; a specialist may be needed to provide the detailed answer.


A Home Inspection Doesn't Replace Well and Septic Investigation

This is particularly important in Nova Scotia.

A property may look entirely conventional but still rely on a private well and on-site septic system.

The Nova Scotia Real Estate Commission recommends septic inspection before finalizing the purchase of a property with an on-site system and notes that the inspection may involve pumping the tank and examining the disposal field. It also identifies licensed septic installers, licensed sewage haulers and professional engineers as professionals who may conduct this type of inspection. Nova Scotia Real Estate Commission

Water testing, well investigation and septic inspection should therefore be considered separately from the general home inspection.

Don't assume that ordering a home inspection automatically covers all three.


A Home Inspection Doesn't Test for Everything

Another common misconception is that a home inspection is a comprehensive test for every possible problem.

It isn't.

Depending on the property, separate investigation may be appropriate for things such as:

  • Well water

  • Septic system

  • Radon

  • Wood-burning appliances

  • Sewer lines

  • Environmental concerns

  • Structural issues

  • Electrical concerns

  • Plumbing concerns

  • Oil tanks

  • Property boundaries

  • Permits or renovation history

Some inspectors may offer additional services.

Others may refer you to specialists.

What's appropriate depends on the particular property.

That's why due diligence should be designed around the house you're actually buying, rather than treating every property exactly the same way.


Radon Is a Good Example of the Inspection's Limits

You can't determine a home's radon level simply by looking at it.

Testing is required.

Nova Scotia says testing is the only way to determine whether a home has elevated radon, and Health Canada recommends a long-term test of at least three months. Government of Nova Scotia

That timeline also illustrates why not every question about a property can necessarily be answered during a typical purchase-condition period.

The important thing is to understand the limitation and decide what information you need before proceeding and what may need to be addressed after ownership.


The Property Disclosure Statement Doesn't Replace an Inspection

If the seller provides a Property Disclosure Statement, it can be a useful source of information about the property's history.

But it isn't the same thing as an inspection.

The Nova Scotia Real Estate Commission points out that the seller may not know about every defect and that the information in a Property Disclosure Statement is based on the seller's personal knowledge. Nova Scotia Real Estate Commission

A seller may genuinely be unaware of a condition hidden behind a finished wall or beneath a roof covering.

Similarly, your REALTOR® may notice visible concerns during a showing, but that isn't a substitute for a professional property inspection.

These sources of information complement one another.

They don't replace one another.


What If the Inspector Finds a Problem?

This is where buyers sometimes become overwhelmed.

Finding problems is part of the inspection process.

Homes require maintenance.

Components wear out.

Older properties may have repairs or systems approaching replacement.

The important questions are:

What was found?

How significant is it?

Does it need immediate attention?

Should a specialist investigate it?

What could it reasonably cost to address?

Does it change how you feel about purchasing the property?

A loose handrail and a significant structural concern shouldn't receive the same weight simply because both appear in the report.

Prioritize.

Buyer reviewing a concern identified during a home inspection

Don't Expect the Inspector to Price Every Repair

An inspection report may help you identify repairs, but a home inspector isn't necessarily the right person to provide a firm repair quote.

If the cost matters to your decision, obtaining information from the appropriate contractor or specialist can be much more useful.

For example, if an inspector identifies a roofing concern, a roofing contractor may be able to determine whether a localized repair is appropriate or whether more substantial work is required.

The same principle applies to electrical, plumbing, structural and heating concerns.

Get the right person answering the right question.


An Inspection Report Isn't Automatically a Renovation List for the Seller

A home inspection may identify numerous maintenance items and improvements.

That doesn't automatically mean the seller is required to repair all of them.

What happens after an inspection depends on the Agreement of Purchase and Sale, the inspection condition, the findings, the buyer's priorities and what the parties agree to do.

Possible outcomes can vary.

A buyer may decide they're satisfied and proceed.

A concern may require additional investigation.

The parties may agree to an amendment addressing an issue.

Or a buyer may determine that they're not satisfied with their condition.

The important point is that the inspection gives you information to make a decision; it doesn't automatically dictate what the seller must do.


Inspection Conditions Have Deadlines

This is particularly important in a Nova Scotia real estate transaction.

The Agreement of Purchase and Sale can make the purchase conditional on the buyer being satisfied with specified conditions, including property inspection.

Those conditions have a deadline.

Under the current Nova Scotia process, when a buyer is satisfied with the applicable buyer conditions, written notice is provided using Form 408: Buyer Waiver of Conditions on or before the agreed deadline. If the required waiver isn't provided by the deadline, the agreement is deemed terminated. Nova Scotia Real Estate Commission

That means inspection day isn't the deadline for simply receiving a report.

You need enough time to understand the findings, complete any necessary follow-up and make your decision within the timeline established in your agreement.


Sometimes the Inspection Creates More Questions

That's normal.

A general inspection may identify a concern without being able to determine its full extent.

For example:

An inspector notices unusual foundation movement.

An electrician may need to evaluate older wiring.

A roofing contractor may need to assess a leak.

A heating technician may need to examine a boiler.

A septic professional may need to investigate the on-site system.

In those situations, the inspection has done something valuable.

It has told you where to look more closely before making your decision.


What About Newer Homes?

New doesn't mean inspection-proof.

Newer houses can still have installation issues, drainage problems, incomplete work, equipment concerns or other defects.

A home doesn't need to be old before an inspection can provide useful information.

The questions may simply be different.

With an older property, you may be trying to understand decades of changes and repairs.

With a newer property, you may be looking more closely at installation, workmanship, operation and whether components are performing as expected.


What About a House Being Sold “As Is”?

“As is” doesn't necessarily make information less valuable.

In fact, understanding the property's condition may become even more important.

The seller's willingness or obligation to make repairs is a separate issue from your need to understand what you're purchasing.

An inspection can still help you estimate future work, identify concerns that require specialist investigation and decide whether the property fits your expectations and budget.

The exact effect of “as is” wording depends on the agreement, so discuss the particular terms with your REALTOR® and obtain legal advice where appropriate.


What Should You Do Before the Inspection?

Once an inspection is scheduled, think about what you already know about the property.

Review available information such as:

  • Property Disclosure Statement

  • Age of the home

  • Known renovations

  • Heating systems

  • Well and septic information

  • Previous concerns noticed during showings

  • Features you don't understand

  • Areas you specifically want the inspector to look at

Make a list of questions.

You don't need to become a home inspector before the appointment.

You simply want to make sure the inspection helps answer the questions that matter to you.


What Should You Do After the Inspection?

Don't look only at the summary page.

Review the report.

Ask questions about anything you don't understand.

Separate routine maintenance from larger concerns.

Determine whether any findings require a specialist.

If estimates or additional inspections are important to your decision, remember your condition deadline.

Then consider the property as a whole.

Every house will eventually require maintenance and repairs.

The goal of the inspection isn't to find a home that will never need work.

It's to help you understand what you're buying today and what may be ahead.

Home buyers reviewing a property inspection report

Use the Inspection to Learn About the Home

A home inspection is sometimes treated as an obstacle between an accepted offer and closing.

It can be much more useful than that.

It's an opportunity to spend time learning how the property works.

Where does the water shut off?

How old is the heating equipment?

What maintenance should you plan for?

What does the inspector think you should monitor?

Which concerns deserve immediate attention and which are longer-term ownership items?

Those are useful questions even when the inspection doesn't uncover a major problem.


Information Is the Real Value of the Inspection

A home inspection can't reveal everything.

It can't see through walls.

It can't predict exactly when an appliance will fail.

It doesn't replace every specialist, test or investigation that might be appropriate for a particular property.

And it doesn't make the buying decision for you.

What it can do is give you a much better understanding of the home before you take ownership.

Use the inspection to identify visible concerns, understand the home's systems, ask better questions and determine whether anything needs a closer look.

Then use that information—along with the rest of your due diligence—to decide whether you're comfortable moving forward.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.

Read

Older Homes in Nova Scotia: What Buyers Should Look For

Older homes are part of the character of many Nova Scotia communities.

In places such as Wolfville, Annapolis Royal, Bridgetown, Digby, Chester and communities throughout the Annapolis Valley and South Shore, it's common to find houses that have been standing for many decades—and sometimes well over a century.

They can offer craftsmanship, mature neighbourhoods, established properties and architectural details that can be difficult to reproduce in a newer home.

They can also tell a complicated story.

An older house may have been renovated several times, had additions built in different decades, received new electrical or plumbing systems, had insulation added and changed heating systems more than once.

That doesn't make an older home a bad choice.

It means that when you're buying one, understanding what has changed—and what hasn't—is often more important than simply knowing when the house was built.


Age Alone Doesn't Tell You the Condition of a Home

A 120-year-old house isn't automatically in worse condition than a 30-year-old house.

Maintenance matters.

So do renovations, materials, workmanship and the way the property has been used over time.

An older home that has been consistently maintained and thoughtfully updated may have fewer immediate concerns than a much newer property where maintenance has been deferred.

That's why the age listed for the property should be the beginning of your investigation rather than the conclusion.

Instead of asking:

“Is this house too old?”

A better question is:

“What parts of this house are original, what has been updated and what may need attention next?”


An Older Home Is Usually a Collection of Different Ages

The house may have been built in 1900.

That doesn't mean everything in it is 126 years old.

The roof may be 8 years old. The electrical panel might be 15 years old. The windows may have been replaced in stages. The kitchen could have been renovated five years ago while some plumbing remains much older.

An addition may have been built decades after the original house.

Thinking about an older home this way makes it easier to evaluate.

You're not really buying a single 100-year-old system.

You're buying a collection of components, renovations and systems from different periods.

The goal is to understand as much of that history as reasonably possible.


Start With the Structure

Older houses can use construction methods and materials that are different from those found in newer homes.

When walking through one, pay attention to how the house feels.

Are floors noticeably uneven?

Do doors close properly?

Are there significant cracks?

Does part of the house appear to slope?

Has an addition been connected to the original structure?

Some movement and unevenness can occur over a home's long life and doesn't automatically indicate a serious structural problem.

What matters is determining whether what you're seeing appears to be old and stable or evidence of an active problem.

That's where a home inspector—and sometimes a structural engineer or other specialist—can become important.


Look Carefully at the Foundation and Basement

Basements in older Nova Scotia homes can look very different from modern poured-concrete basements.

Depending on the age and location of the property, you may encounter stone foundations, masonry, concrete block, poured concrete or combinations of materials from different renovations.

You may also find a basement that was originally intended more as a utility or storage space than finished living space.

Look for signs of:

  • Water entry

  • Dampness

  • Efflorescence or staining

  • Cracking

  • Deteriorating mortar

  • Previous repairs

  • Rot near sill areas

  • Improvised structural supports

  • Changes where additions meet the original house

A basement doesn't have to look new to be functional.

The important question is whether the foundation is performing properly and whether moisture is being managed.

Stone foundation in the basement of an older Nova Scotia home

Water Management Matters at Any Age

Many expensive problems in houses begin with water.

Older homes are no exception.

Look beyond the basement itself and examine how water moves around the property.

Consider:

  • Roof drainage

  • Gutters and downspouts

  • Grading around the foundation

  • Low areas beside the house

  • Drainage from neighbouring land

  • Signs of previous basement water

  • Rot or deterioration around exterior wood

  • Condition around decks, porches and additions

A wet basement doesn't necessarily mean the foundation has failed.

Sometimes the cause is surprisingly simple.

But visible moisture or a history of water entry deserves investigation rather than assumption.

Drainage and foundation area around an older home

Electrical Systems Can Tell You a Lot About an Older Home

Electrical systems often change significantly during the life of an older house.

A home may have a modern electrical panel while some older wiring remains elsewhere.

That's why looking only at the panel isn't enough.

Depending on the age and renovation history, an inspector or electrician may identify older wiring methods, additions to circuits, outdated equipment or work completed at different times.

Buyers should also think about capacity, not just age.

Modern households can place very different demands on an electrical system than the house was originally designed to support.

Heat pumps, electric water heaters, appliances, workshops, hot tubs and electric-vehicle chargers can all increase electrical demand.

If you're planning significant changes after purchasing the home, understanding the electrical system beforehand can help you determine whether upgrades may eventually be required.

Electrical system being evaluated in an older home

Don't Assume Renovated Means Everything Was Updated

A beautifully renovated kitchen can make an older home feel new.

But new cabinets, flooring and countertops don't tell you what happened behind the walls.

The electrical system may have been updated during the renovation—or it may not have been.

The plumbing may be new in that room while older supply or drain lines remain elsewhere.

Insulation may have been improved in one addition but not in the original house.

When a property has undergone substantial renovations, useful questions include:

What work was completed?

When was it completed?

Who completed it?

Were permits required?

Are permits, invoices, warranties or other records available?

Documentation isn't always available, particularly for work completed many years ago.

Its absence doesn't automatically mean something is wrong.

It simply means you may need to rely more heavily on the physical condition of the property and appropriate professional evaluations.


Additions Deserve Their Own Look

Older houses often grow over time.

A rear kitchen, mudroom, sunroom, garage or additional living space may have been added decades after the original house was constructed.

Treat an addition almost like a small building attached to the main one.

Look at:

  • How it connects to the original structure

  • Foundation type

  • Roof connection

  • Drainage

  • Insulation

  • Heating

  • Electrical service

  • Floor levels

  • Signs of movement or water entry

Problems sometimes occur not in the original house or the addition itself, but where the two structures meet.

Older Nova Scotia home with a later addition

Plumbing May Have Been Updated in Stages

Like electrical systems, plumbing in an older home may represent several generations of materials.

A renovated bathroom may have modern supply and drain lines while older plumbing remains in the basement or elsewhere in the house.

Look for visible leaks, corrosion, staining and evidence of previous repairs.

Water pressure and drainage performance are also worth paying attention to during an inspection.

And remember that plumbing inside the house is only part of the picture.

Depending on the property, the home may also rely on a private well and septic system, which should be investigated separately.


Heating Systems Often Change During the Life of the House

An older Nova Scotia home may have been heated several different ways over its lifetime.

You might find an oil-fired boiler that replaced an earlier system, electric baseboards added to an addition, heat pumps installed more recently and a wood stove providing supplemental heat.

That's not necessarily a problem.

In fact, multiple heating systems are common enough that the important question is how they work together.

Find out:

  • What provides most of the heat?

  • Which areas does each system serve?

  • How old is the equipment?

  • What maintenance has been completed?

  • Are any older components still present but no longer used?

  • How is domestic hot water produced?

Understanding the heating configuration can also help when estimating future operating and replacement costs.


Older Doesn't Automatically Mean Energy Inefficient

It's easy to assume that an older home will automatically be expensive to heat.

That's too simple.

Some older homes have received substantial insulation, air-sealing, window and heating upgrades. Others may still perform much closer to their original construction.

Even two houses built in the same year can perform very differently.

Instead of using age as a shortcut, look at the actual home.

Consider its insulation, air leakage, windows, heating equipment, size and previous improvements.

This gives you a much better picture of how the house is likely to perform than the construction date alone.


Windows Don't Have to Be New to Be Worth Keeping

Older homes sometimes retain original wood windows.

Buyers occasionally assume these automatically need to be replaced.

Condition matters more than age alone.

Older wood windows may require maintenance, weatherstripping, storm windows or repairs. In other situations, replacement may make sense.

If windows have already been replaced, look at the quality of the installation as well as the window itself.

Water intrusion and air leakage can occur around a poorly installed newer window just as they can around an older one.


The Roof Is More Than the Shingles

When evaluating the roof of an older house, don't focus only on the age of the shingles.

The roof structure may have been altered over time.

Dormers may have been added.

Chimneys may have been removed or abandoned.

Additions can create valleys and complicated roof intersections.

Inside the attic, an inspector may be able to identify evidence of previous leaks, ventilation issues, structural changes or older repairs.

A newer roof covering is certainly useful information, but it doesn't replace looking at the roof as a complete system.

Roof structure being inspected in the attic of an older home

Chimneys Can Outlive the Systems They Once Served

Older homes may have one or more chimneys even if the original heating equipment is long gone.

A chimney might currently serve a wood stove or heating appliance.

Another may be unused.

Some have been partially removed during renovations while portions remain elsewhere in the house.

If a chimney is still in use, its condition and suitability for the connected appliance matter.

If it isn't being used, you may still want to understand its condition and whether it has been properly capped or altered.


Attics Can Reveal a Lot About a House

If accessible, the attic can be one of the most informative places in an older home.

It may reveal:

  • Roof structure

  • Insulation levels

  • Ventilation

  • Evidence of previous leaks

  • Electrical wiring

  • Chimney condition

  • Signs of animals or pests

  • Changes made during renovations

It can also help explain why certain rooms feel colder or warmer than others.

A finished house can hide much of its construction history.

The attic often doesn't.


Watch for Signs of Past Repairs—But Don't Assume Repairs Are Bad

Repairs are normal in an older house.

In fact, a century-old home with no evidence of repair would be unusual.

The presence of new framing, patched foundations, replaced plumbing or repaired roofing isn't automatically a warning sign.

The question is why the repair was needed and whether it was completed properly.

Sometimes evidence of a repair tells you that a previous owner addressed a problem.

Other times it identifies an area that deserves a closer look.

Context matters.


Older Homes and Radon

Radon isn't specifically an “old house problem.”

Newer homes can have elevated radon too.

Radon is a naturally occurring radioactive gas that can enter buildings from the soil and rock beneath them. Nova Scotia currently recommends testing homes because elevated levels can occur throughout the province. The only way to know the radon level in an individual home is to test it. Government of Nova Scotia

That distinction is important when buying an older property.

The age of the house doesn't tell you whether it has a radon problem.

Testing does.

For long-term assessment, Health Canada recommends testing for at least three months. Government of Nova Scotia


Insurance Is Worth Investigating Early

Older homes can sometimes require additional information before an insurer is comfortable providing coverage.

The insurer may ask questions about systems such as:

  • Electrical wiring

  • Plumbing

  • Heating

  • Oil tanks

  • Wood-burning appliances

  • Roof age and condition

Requirements vary between insurance companies and between properties.

Don't assume that because the seller currently has insurance, your insurer will automatically insure the home under the same terms.

If the property has older systems or unusual features, starting the insurance conversation early can prevent surprises later in the buying process.


Heritage Registration Is Different From Simply Being an Old House

An old home isn't automatically a registered heritage property.

Nova Scotia has both provincial and municipal heritage registries, and a property can potentially appear on one or both. Registered properties receive protection under heritage legislation, while municipalities administer their own municipal registries. Cultural Heritage Hub

If you're considering a registered heritage property, find out exactly what designation applies and investigate what that means before planning renovations or exterior changes.

This is different from buying an older home that simply has historic character.

The distinction matters.


A Home Inspection Becomes Particularly Valuable

A home inspection is useful with any property, but an older house gives the inspector a longer history to interpret.

The inspector isn't there simply to produce a list of everything that isn't new.

A useful inspection helps you understand the home's major systems, identify visible concerns and determine where additional investigation may be appropriate.

Depending on what is found, that could mean consulting:

  • An electrician

  • A plumber

  • A structural engineer

  • A roofing contractor

  • A heating technician

  • A chimney or WETT-trained professional

  • A foundation or drainage specialist

  • Another qualified professional

The home inspector doesn't replace these specialists.

The inspection can help identify when bringing one in makes sense.

Home inspector evaluating an older Nova Scotia house

Don't Expect an Old House to Behave Like a New One

This is an important mindset when viewing older properties.

Original floors may not be perfectly level.

Walls may not be perfectly straight.

Doors may have been adjusted over the years.

Trim may show generations of paint.

Rooms may have dimensions that wouldn't be used in a modern floor plan.

Those characteristics aren't necessarily defects.

At the same time, “it's an old house” shouldn't be used to dismiss genuine structural, moisture, electrical or safety concerns.

The goal is to distinguish age and character from problems that require attention.


Think About the Renovations You Want to Make

Before buying an older house, consider what you hope to change.

Opening walls, moving kitchens, adding bathrooms, finishing basements or significantly changing the heating system can uncover conditions that weren't visible during the purchase.

You may also discover that a seemingly simple renovation affects electrical, plumbing, insulation or structural components.

If your plans are important to whether the property works for you, investigate their feasibility before assuming they can easily be completed.

This becomes particularly important with registered heritage properties, unusual construction and major structural alterations.

Maintained interior of an older Nova Scotia home

Budget for Ownership, Not Just the Purchase

Older homes don't necessarily require constant expensive repairs.

But they do reward owners who plan ahead.

Rather than asking whether the home will ever need work, identify the major components and consider what may need attention over the next several years.

Perhaps the roof is relatively new but the heating equipment is older.

Maybe the electrical system has been updated but some windows need maintenance.

Perhaps the house is structurally sound but would benefit from insulation and air-sealing improvements.

Understanding those priorities can help you build a more realistic ownership budget.


What Should a Buyer Investigate?

Every older home is different, but depending on the property, a buyer may want to understand:

  • Foundation and structural condition

  • Water entry and drainage

  • Roof and attic

  • Electrical system

  • Plumbing

  • Heating equipment

  • Oil tanks or wood-burning appliances

  • Insulation and air sealing

  • Windows and exterior condition

  • Chimneys

  • Additions and major renovations

  • Available permits or renovation records

  • Private well and septic systems, if applicable

  • Radon

  • Insurance requirements

  • Heritage registration, if applicable

That doesn't mean every older house needs every possible specialist.

It means the investigation should respond to what is actually present in that particular home.


Buy the House That's Actually in Front of You

An older home shouldn't be judged simply because it's old.

And it shouldn't be given a free pass because its age gives it character.

Look at the actual house.

Understand its systems.

Find out what has been updated.

Investigate what hasn't.

Pay attention to water, structure, electrical, plumbing, heating and the changes made over the home's lifetime.

Then consider how those things fit your budget, your plans and the way you want to live.

A home that's been standing for generations can still have many years ahead of it.

The important part is knowing as much as reasonably possible about the house you're taking ownership of today.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.
Read

Heating a Home in Nova Scotia: Oil, Heat Pumps, Wood, Electric & More

When you're buying a home in Nova Scotia, the heating system deserves more attention than simply checking the box marked “heat.”

Two houses that look similar can feel very different through a Nova Scotia winter—and cost very different amounts to keep comfortable.

You may encounter oil furnaces, hot-water boilers, ducted and ductless heat pumps, electric baseboards, wood stoves, pellet stoves, propane systems and homes that combine several of them. In many cases, understanding the combination is more useful than identifying one “primary” heating source.

The goal isn't to find the one heating system that's automatically best.

It's to understand how the particular home is heated, how well that system suits the house, what it may cost to operate and what responsibilities you're taking on when you buy it.


Start With How the Whole House Is Heated

A listing might say a home has a heat pump.

That doesn't necessarily mean the heat pump heats every room.

It might serve the main living area while bedrooms have electric baseboards. An oil-fired boiler may provide the home's central heat while a heat pump handles much of the day-to-day heating and cooling. A wood stove might supplement another system during colder weather.

When viewing a property, start with a few basic questions:

What produces the heat?

How is that heat distributed through the house?

Does the system serve the entire home?

Is there another heating system as well?

Which system does the current owner actually use?

That gives you a much better picture than the heating label in the listing alone.


The Heating System Is Only Part of the Equation

Heating costs aren't determined by the heating equipment alone.

The same furnace or heat pump can perform very differently in two different houses.

Insulation, air leakage, windows, ceiling height, house size, layout, exposure to wind and even how warm the occupants like to keep the house can all affect energy use.

That's why a high heating bill doesn't automatically mean the heating system is inefficient—and a low bill doesn't necessarily mean another family will have the same result.

When comparing homes, think about the house and heating system together.


Oil Heat Is Still Something Nova Scotia Buyers Will Encounter

Oil heating remains common enough in Nova Scotia that buyers should understand the basics even if they've never lived with it before.

An oil-fired system may use a furnace, which heats and distributes air through ductwork, or a boiler, which heats water that circulates through radiators or baseboards.

Both can provide comfortable whole-home heat.

For a buyer, however, the heating appliance is only part of what needs attention.

There is also the oil tank.


If There's Oil Heat, Look at the Tank Too

A domestic oil tank is more than a container sitting beside the house or in the basement.

Nova Scotia requires domestic fuel-oil tank installations to comply with applicable fuel-safety standards, and the province recommends installation by a trained and licensed Oil Burner Technician. Homeowners are responsible for maintaining their tanks. Government of Nova Scotia

When you're considering an oil-heated property, useful questions include:

  • How old is the tank?

  • Is it indoors or outdoors?

  • What type of tank is it?

  • Is there an identification or certification label?

  • Who installed it?

  • Are installation records available?

  • Is there any evidence of corrosion, leakage or previous problems?

  • Has the furnace or boiler been regularly serviced?

The answers can matter for maintenance, future replacement and insurance.

An older tank doesn't automatically mean you shouldn't buy the house. It means the tank deserves the same kind of investigation you'd give other significant components of the property.

Domestic heating oil tank in a Nova Scotia home

An Oil Leak Can Be Much More Than a Heating Repair

One reason oil tanks deserve particular attention is the potential consequence of a leak.

Heating oil can contaminate soil and groundwater, and cleanup can become significantly more complicated than simply replacing the tank. Nova Scotia specifically warns of the potential environmental damage and high cleanup costs associated with oil spills. Government of Nova Scotia

For buyers, this is one of the reasons to look beyond whether the furnace turns on.

The tank, fuel lines, equipment and surrounding area are all part of understanding an oil-heated property.


Heat Pumps Have Become an Important Part of Home Heating

Heat pumps are increasingly familiar to Nova Scotia home buyers.

Unlike electric baseboards, which create heat using electrical resistance, a heat pump moves heat between indoors and outdoors. During the heating season, it extracts heat from outside air and transfers it into the home.

Most residential heat pumps can also reverse that process and provide air conditioning during warmer weather.

That combination of heating and cooling is one reason buyers often view a heat pump as an attractive feature.

But seeing a heat pump on the wall doesn't tell you everything you need to know.


A Heat Pump May Not Heat Every Part of the House Equally

A common ductless heat pump has one or more indoor heads connected to an outdoor unit.

Where those heads are located matters.

An indoor unit in an open kitchen, dining and living area may do an excellent job heating that space. That doesn't mean the heat will travel equally well through closed bedroom doors, around corners or between floors.

A ducted heat-pump system works differently because conditioned air can be distributed through ductwork.

When viewing a home with heat pumps, look at:

  • How many indoor units there are

  • Where they're located

  • Which rooms they serve

  • Whether there is another heating system

  • What happens in rooms without a heat-pump head

  • The age and apparent condition of the equipment

The important question isn't simply “Does the house have a heat pump?”

It's “How does this house actually use its heat pumps?”

Ductless heat pump heating the main living area of a home

Don't Assume a Heat Pump Means the Other Heating System Is Obsolete

Many Nova Scotia homes have more than one way to produce heat.

A house might have heat pumps along with:

  • Electric baseboards

  • An oil furnace or boiler

  • A wood stove

  • A pellet stove

  • Another central heating system

That isn't necessarily duplication without purpose.

The systems may serve different parts of the home or give the owner flexibility in how the house is heated.

If you're buying a home with multiple heating systems, understand whether each is operational and why it's there before deciding that one can simply be removed.


Electric Baseboard Heat Is Simple—but the House Still Matters

Electric baseboard heating is straightforward.

Each heater uses electrical resistance to create heat, and individual thermostats often allow rooms to be controlled separately. There is no furnace, boiler, oil tank or central ductwork required.

That simplicity can mean fewer moving parts.

But operating cost depends heavily on how much heat the home requires.

A smaller, well-insulated and reasonably airtight house may be a very different proposition from a large, drafty home using electric resistance heat throughout.

So if you see electric baseboards, don't evaluate them in isolation.

Consider the home's size, insulation, air sealing and other energy characteristics too.


Wood Heat Brings a Different Set of Considerations

Wood stoves can provide substantial heat and are familiar features in many Nova Scotia homes.

Some owners use wood as supplemental heat. Others rely on it much more heavily.

For a buyer, there are several things to understand:

  • What appliance is installed?

  • How old is it?

  • What type of chimney or venting system does it use?

  • Is the installation appropriate?

  • When was the chimney last cleaned?

  • Is there documentation for the installation?

  • Is there a recent inspection?

  • Will your insurer accept the system?

This is one area where a specialized inspection can be particularly important.

Wood stove installed in a Nova Scotia home

What Does “WETT Certified” Actually Mean?

Buyers often hear that a wood stove needs a “WETT inspection.” One common misconception is that a wood stove itself can be “WETT certified.” It can't—WETT certifies qualified individuals, who can inspect the system and provide an inspection report.

WETT stands for Wood Energy Technology Transfer. WETT is a Canadian non-profit training and education organization that maintains a registry of professionals trained in the inspection, installation and maintenance of wood-burning systems. Wettinc

WETT itself notes that many insurance companies require inspection, installation or maintenance work involving wood-burning equipment to be completed by someone with appropriate WETT certification. Wett Inc.

For a home purchase, a WETT-trained professional can evaluate the visible components of the appliance and venting system and identify deficiencies or concerns that may require further investigation. Wett Inc.

So if a home has a wood stove, fireplace insert or another solid-fuel appliance, don't assume that its presence—or the fact that the seller uses it—means your insurer will automatically accept it.

Investigate it before you need to rely on it.

Professional inspecting a residential wood-burning system

Pellet Stoves Are Similar—but Not the Same as Wood Stoves

A pellet stove burns manufactured wood pellets rather than split firewood.

Pellets are generally fed automatically from a hopper into the combustion area, which can make operation quite different from a traditional wood stove.

But a pellet appliance still needs to be considered as a heating system.

Look at its age, condition, installation, venting, maintenance history and availability of fuel.

Also remember that many pellet stoves depend on electricity to operate their feed system and fans. That's an important distinction if you're thinking of the appliance as emergency heat during a power outage.


Propane May Heat More Than You Expect

Some Nova Scotia homes use propane for central heating, fireplaces, water heating, cooking—or a combination of those uses.

If propane is part of the property, determine exactly what it serves.

You may also want to understand the tank arrangement. Depending on the property, a propane tank may be owned by the homeowner or supplied under an arrangement with a fuel company.

That distinction can affect what transfers with the property and what arrangements you'll need after closing.

As with any fuel-burning appliance, condition, installation and servicing are more important than simply knowing that the fuel source is propane.


Don't Forget About Domestic Hot Water

Space heating gets most of the attention during a home search, but buyers should also ask:

How is the water heated?

The answer may be completely separate from the home's main heating system.

A home might have:

  • An electric water heater

  • An oil-fired water heater

  • A boiler that also provides domestic hot water

  • A propane water heater

  • A heat-pump water heater

  • Another configuration

This matters because hot water contributes to the home's overall energy use and because replacing one heating system can sometimes affect another.

For example, if a boiler heats both the house and domestic water, replacing the space-heating system may require a separate plan for hot water.


A Heating System Can Affect Home Insurance

Heating systems aren't only an energy-cost question.

They can also affect whether an insurer is willing to insure a property and under what conditions.

Oil tanks, wood-burning appliances and older or unusual heating equipment may receive additional scrutiny from an insurer.

Requirements vary between insurers, so don't assume that because the seller currently has insurance, your insurer will treat the property exactly the same way.

This is one reason insurance should be investigated during the buying process rather than left until the final days before closing.


Ask for Heating Costs—but Put Them in Context

Previous heating bills can be useful.

They can help you understand how much fuel or electricity the current occupants have been using.

But they're not a guarantee of what you'll spend.

One household may keep the house at 22°C all winter while another prefers 18°C. Someone may heat every room continuously, while another closes off unused spaces. A seller may burn several cords of wood in addition to the electricity shown on a power bill.

Occupancy can also change the numbers dramatically.

So when reviewing historical costs, ask what those numbers actually include.

For example:

Does the electricity bill include most of the home's heating?

Was oil also used?

How much wood was burned?

Was the house occupied year-round?

What temperature was normally maintained?

Historical bills are evidence of how that household used that home, not a quote for your future heating costs.

Home buyers reviewing household heating and energy costs

Think Carefully Before Comparing One Home's Heating Bill With Another

A $2,000 annual heating cost for one house and a $3,000 cost for another doesn't automatically tell you which home is more efficient.

Perhaps one house is twice the size.

Perhaps one includes domestic hot water in that number and the other doesn't.

Maybe one owner heated primarily with purchased energy while the other cut their own firewood.

Even the orientation and exposure of a house can matter.

Heating costs are most useful when considered alongside the building itself.


What About Backup Heat During a Power Outage?

Nova Scotia buyers sometimes ask whether a home's heating system will continue operating if the electricity goes out.

The answer isn't as simple as identifying the fuel.

An oil furnace, for example, still generally requires electricity to operate its burner, controls and blower. A hot-water boiler may require electricity for controls and circulation pumps. Pellet stoves generally use electricity for their feed and fan systems.

Some wood stoves can continue providing heat without household electricity.

A heat pump, of course, requires electricity.

If maintaining heat during an outage is important to you, investigate how the actual system in the home operates rather than assuming that a non-electric fuel automatically means the house can be heated without power.

Wood stove providing heat during colder Nova Scotia weather

Older Heating Equipment Isn't Automatically a Problem

Age matters, but it isn't the only thing that matters.

A well-maintained older boiler may have years of useful service remaining. A newer system that hasn't been maintained properly can have problems much sooner.

When you're evaluating heating equipment, useful information can include:

  • Approximate age

  • Service history

  • Maintenance records

  • Visible condition

  • Availability of parts

  • Any known problems

  • Whether a qualified technician recommends further evaluation

The goal isn't to reject every older component.

It's to understand what you're buying and whether you should plan for maintenance or replacement.


Replacing the Heating System Isn't Always the First Upgrade to Make

It's easy to look at an older furnace or boiler and immediately start calculating the cost of replacing it.

Sometimes that's appropriate.

But heating equipment is only one part of home performance.

If a house loses large amounts of heat through air leakage or insufficient insulation, reducing that heat loss may improve comfort and reduce energy use regardless of what produces the heat.

That doesn't mean an inefficient or failing heating system should be ignored.

It means the best improvement plan usually starts by understanding where the house needs energy and why.


A Home With Several Heating Systems Isn't Necessarily Complicated

A listing that says:

Heat pump / oil / wood

can sound confusing to someone accustomed to a single furnace.

In practice, it may simply mean the homeowner has options.

Perhaps the heat pump handles most spring and fall heating. The oil boiler serves the whole house when needed. The wood stove provides additional heat in the main living area.

The important part is determining how those systems interact.

A buyer should be able to leave the property understanding:

What heats the house most of the time?

What heats areas the primary system doesn't reach?

What is the backup?

What equipment will require maintenance?

What fuels will I need to purchase?

Once you can answer those questions, a multi-system home becomes much easier to understand.


Don't Judge the Heating System by the Thermostat

During a showing, a warm house tells you that something is producing heat.

It doesn't tell you:

  • How efficiently the house retains that heat

  • Whether every room is comfortable

  • What the system costs to operate

  • Whether equipment is approaching replacement

  • Whether an oil tank has concerns

  • Whether a wood appliance is acceptable to your insurer

  • Whether supplemental systems are needed

  • Whether the home's electrical service can support future upgrades

Those questions require a little more investigation.


What Should a Buyer Investigate?

When I'm helping a buyer look at a Nova Scotia home's heating, I'm less interested in finding a particular “best” system than in understanding how the property works.

Depending on the home, that may mean looking into:

  • The primary heating system

  • Supplemental heating systems

  • Equipment age and maintenance

  • How heat is distributed throughout the house

  • Oil-tank age and condition

  • Wood or pellet appliances and their venting

  • Heat-pump locations and coverage

  • Historical fuel and electricity use

  • Domestic hot-water heating

  • Insurance requirements

  • Potential upcoming replacement costs

  • How the home's insulation and air sealing affect heating demand

Not every property requires every investigation.

The heating system should be evaluated in the context of the particular home.

Heating system being evaluated before a home purchase

Understand How the House Keeps You Comfortable

When buying a home in Nova Scotia, heating deserves more attention than identifying whether the house uses oil, electricity, wood or a heat pump.

Look at the whole system.

Understand where the heat comes from, how it moves through the house, which equipment supports it and what responsibilities you'll inherit as the owner.

Then look one step further.

A heating system supplies the energy, but the house itself determines how much of that energy it needs to stay comfortable.

Understanding both sides of that equation can help you make a much more informed decision about the home you're buying.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.
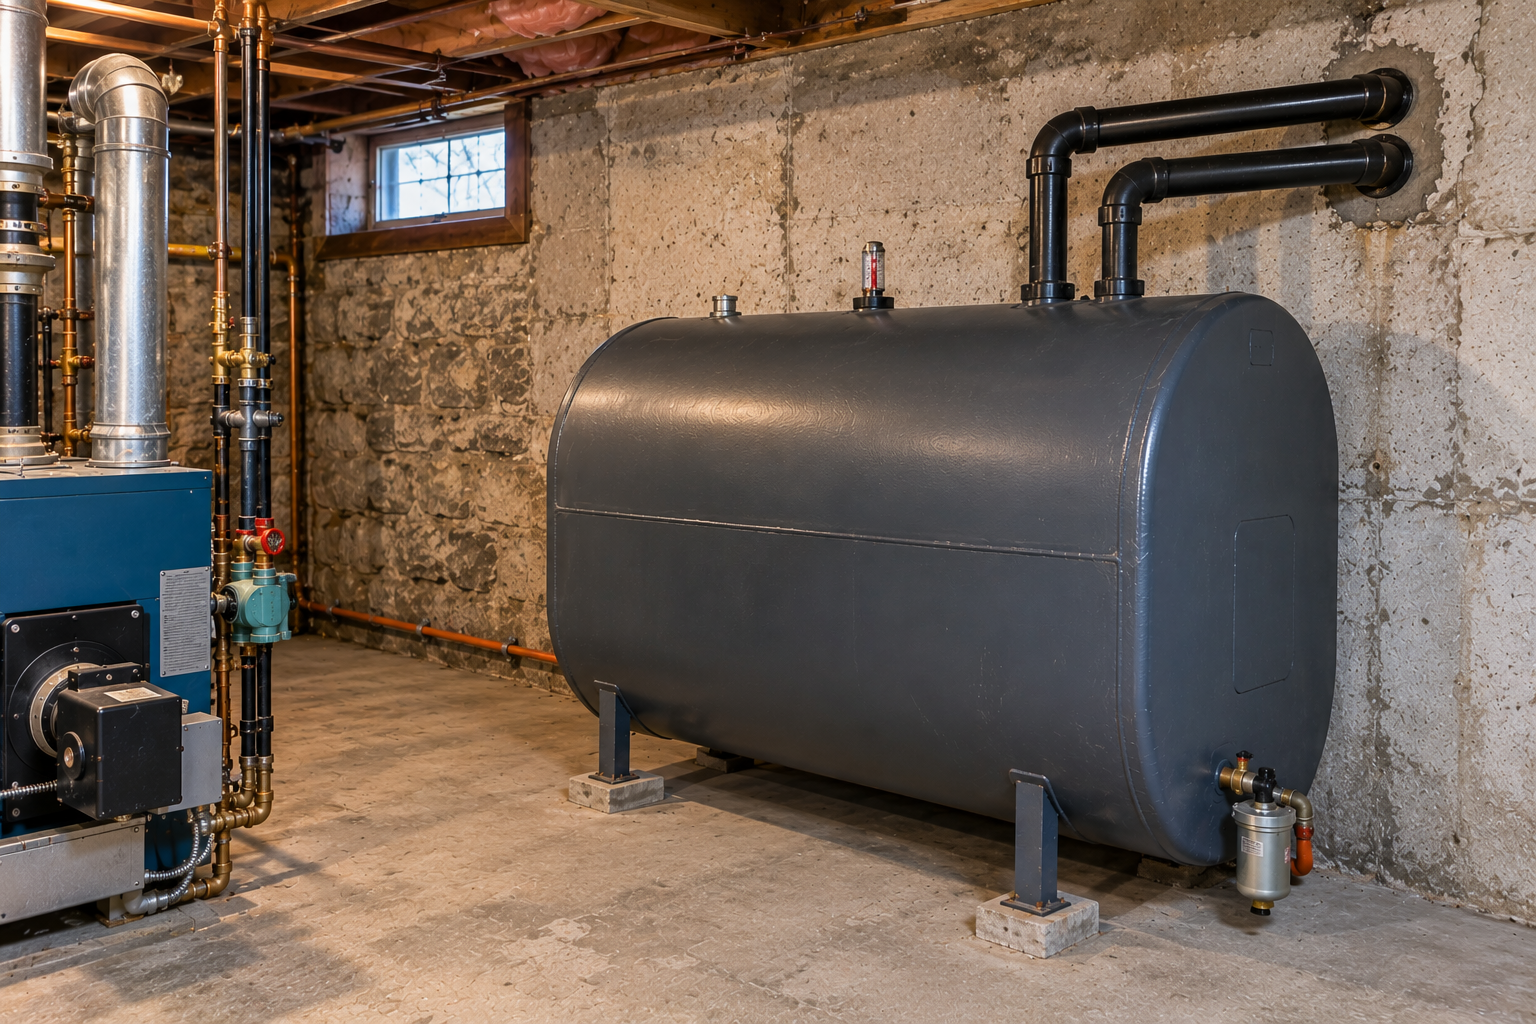
Read
×

Do you have questions?

Call or text today.
I am always here to help!

902-300-8674