RSS

Well & Septic Systems: What Nova Scotia Home Buyers Need to Know

A house can look completely ordinary from the road while two of its most important systems are almost entirely out of sight.

For many Nova Scotia properties, drinking water comes from a private well and wastewater is handled by an on-site sewage disposal system—usually called a septic system. These aren't unusual features reserved for remote country properties. Nova Scotia says about 46% of Nova Scotians rely primarily on groundwater from private wells, while approximately 45% of homes use on-site sewage disposal systems. Government of Nova Scotia

If you've always lived in a home connected to municipal water and sewer, buying a property with a well and septic system can feel like a major change.

It doesn't necessarily need to be.

The important thing is understanding what you're buying, investigating the systems appropriately and knowing what responsibilities become yours after closing.


Start by Finding Out How the Property Is Serviced

Don't assume a property has municipal water and sewer simply because it's located in a town or developed neighbourhood.

Depending on the property, you could encounter:

  • Municipal water and municipal sewer

  • A private well and septic system

  • Municipal water with a septic system

  • A private well with municipal sewer

  • A shared water supply

  • Another water source, such as a cistern

The first step is simply identifying what serves the particular property.

Once you know that, you can determine what additional questions or investigations make sense.


A Private Well Is Your Water Supply

With municipal water, you generally turn on the tap and the municipality is responsible for supplying the water.

A private well changes that relationship.

As the property owner, you become responsible for the well and for monitoring the quality of your drinking water. Nova Scotia specifically places responsibility on private well owners for maintaining their water supply and having the water tested. Government of Nova Scotia

That makes two questions especially important when you're considering a property:

Is the water safe to drink?

and

Can the well provide enough water for the household?

Those sound similar, but they're actually two different issues.
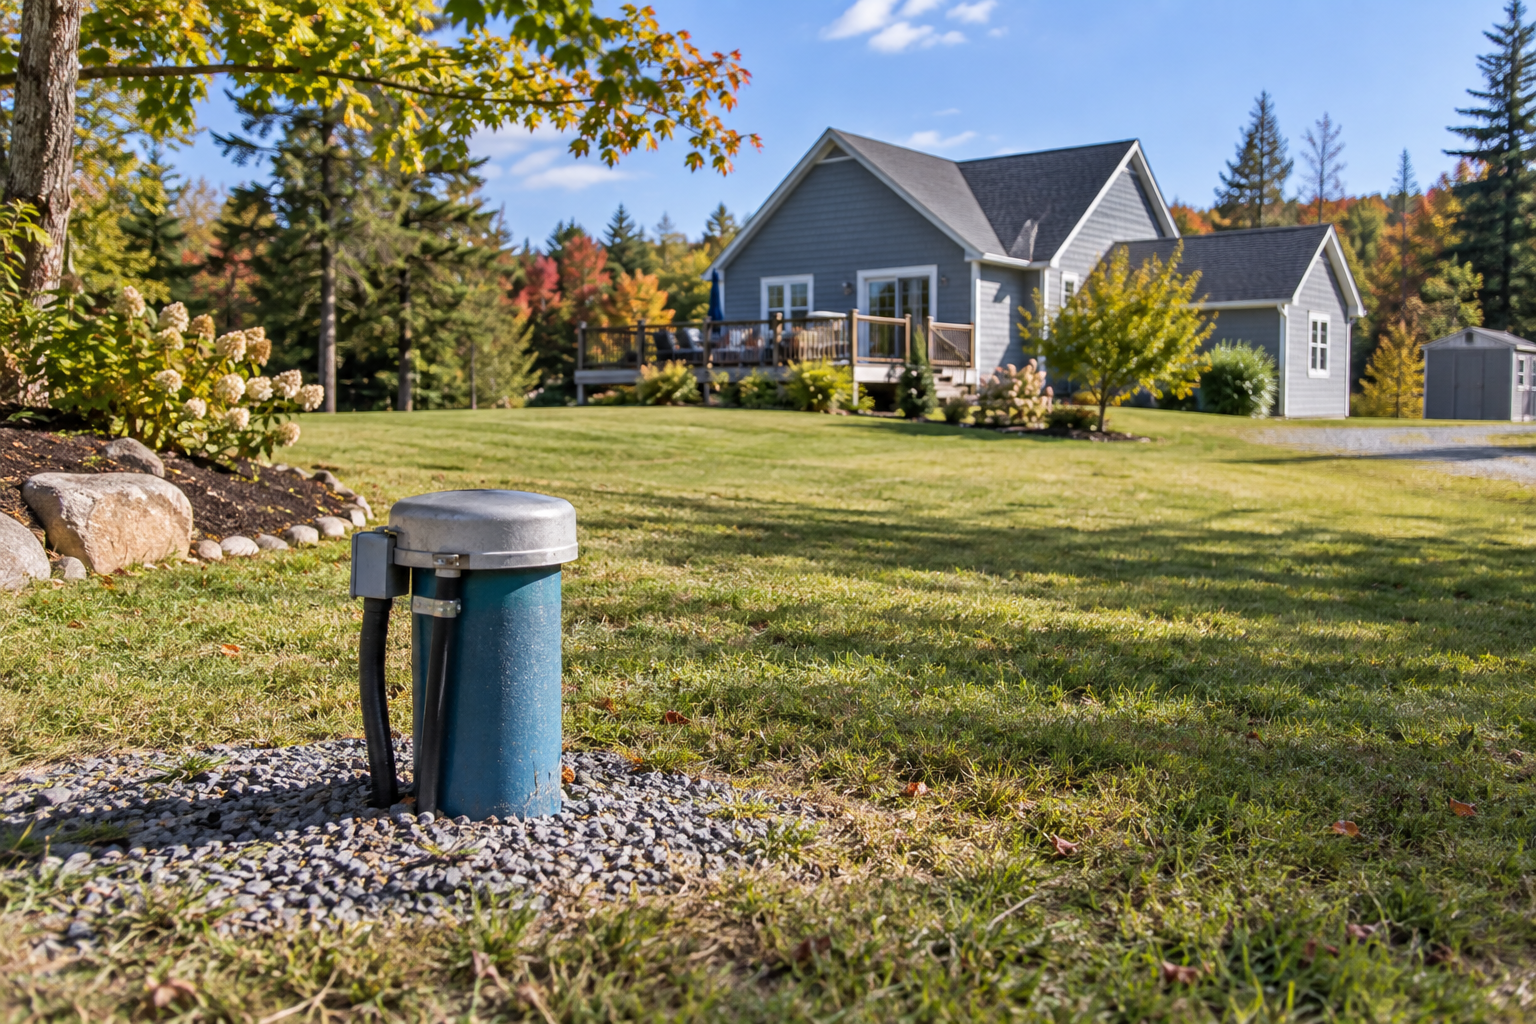
Private drilled well serving a Nova Scotia home

Water Quality and Water Quantity Aren't the Same Thing

A well can produce plenty of water and still have a water-quality problem.

It can also produce excellent-quality water but struggle to supply enough water for the way a household uses it.

That's why evaluating a private well shouldn't stop at turning on a faucet and seeing whether water comes out.

Nova Scotia's guidance for private wells in real estate transactions specifically recommends looking at both water quality and the well's ability to provide enough water for the household. Government of Nova Scotia


What Should Well Water Be Tested For?

Clear water isn't necessarily safe water.

Some contaminants have no obvious taste, smell or colour, so looking at a glass of water—or tasting it—isn't a substitute for laboratory testing. Government of Nova Scotia

Nova Scotia's current real-estate guidance calls for two bacteria tests taken at least five days apart, plus a full chemistry and metals test, with samples properly collected and analyzed by an accredited laboratory. Government of Nova Scotia

Chemical testing can identify naturally occurring substances and other characteristics of the water. Nova Scotia identifies potential well-water concerns including arsenic, uranium, manganese, fluoride, lead, nitrate/nitrite, sodium, chloride and hardness, among others. Government of Nova Scotia

The appropriate testing can depend on the property and surrounding land uses, so this is an area where qualified laboratories and water professionals can provide important guidance.
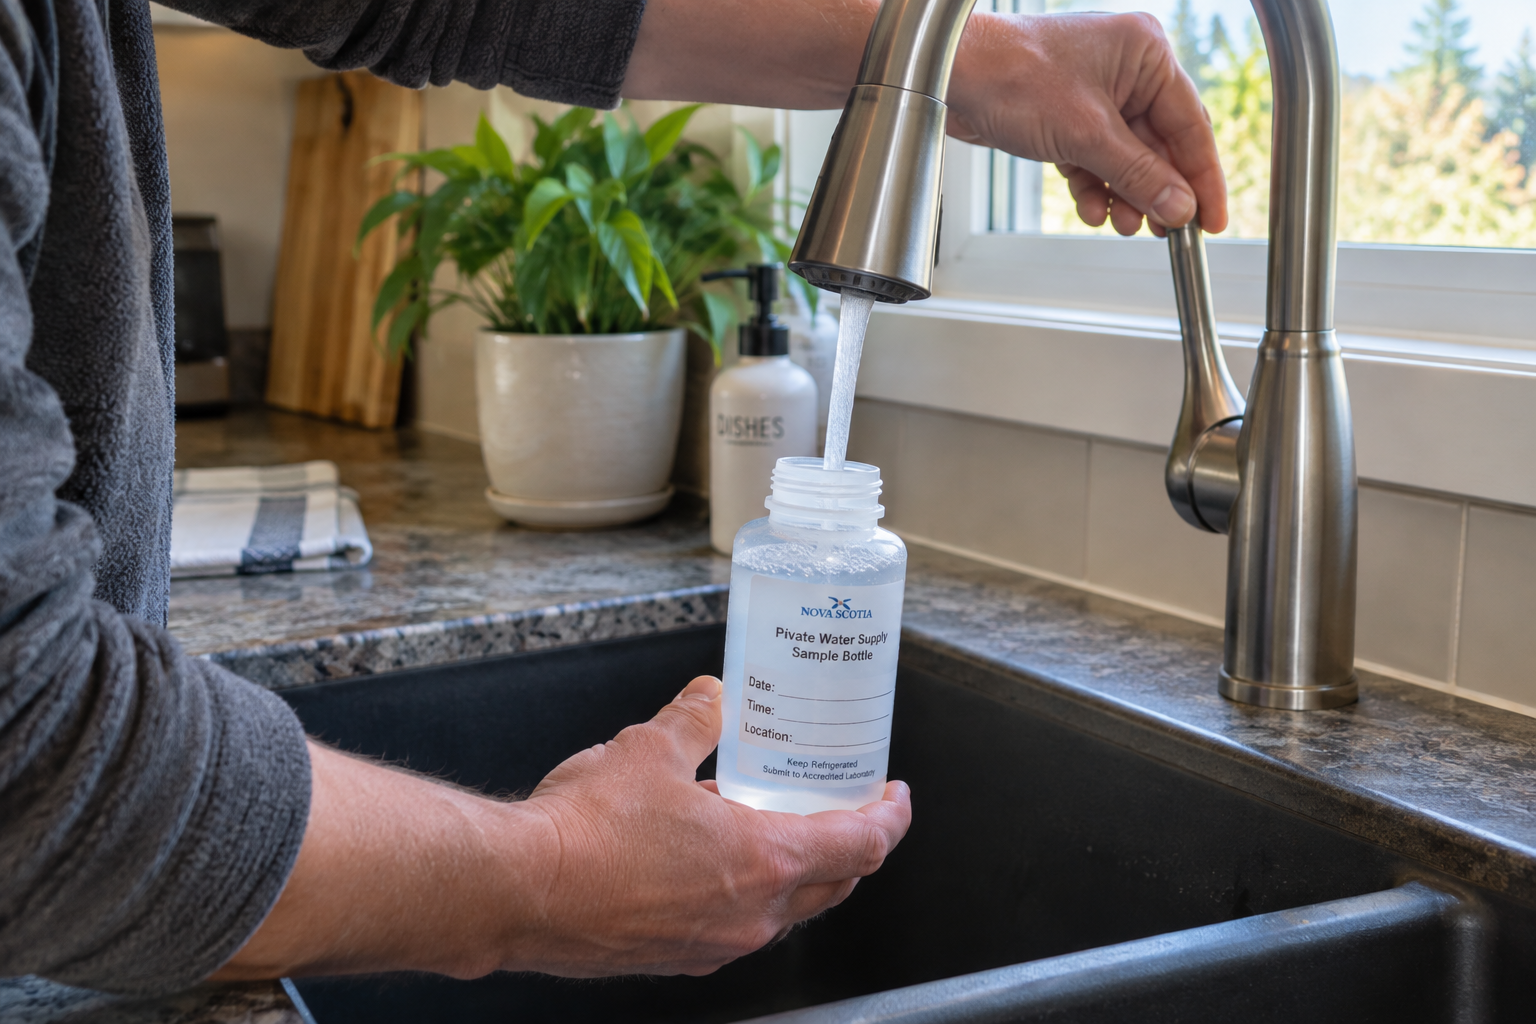
Collecting a private well water sample for testing

What If the House Has a Water-Treatment System?

Seeing a UV light, filter, softener or other treatment equipment doesn't automatically tell you whether there's a problem.

The more useful questions are:

What is the equipment treating?

Is the source water safe without treatment?

Is the treatment system actually working?

Nova Scotia's real-estate guidance recommends sampling both before and after a treatment system where one is present. That can help distinguish the quality of the untreated source water from the water being delivered after treatment. Government of Nova Scotia

It's also worth asking about the equipment's age, maintenance requirements and ongoing operating costs.

A treatment system isn't necessarily a reason to reject a property. It is simply another home system you need to understand.


Ask About the Well Itself

Water testing tells you about the water at the time it was sampled.

There is also useful information to learn about the physical well.

Nova Scotia recommends buyers ask for the well construction record, commonly called the well log, and identify whether the water source is a drilled well, dug well, surface-water source or cistern. A well log may provide information such as well depth, casing length, static water level and reported yield. Government of Nova Scotia

Not every older property will have complete records readily available.

That doesn't automatically mean there's something wrong with the well. It may simply mean additional investigation is appropriate.
Private well being evaluated at a Nova Scotia property

What Is Well Yield?

Well yield is essentially a measure of how quickly water can enter or be produced by the well.

That's different from how much water happens to be stored in the well at a particular moment.

For a buyer, the practical question is whether the combination of yield and available storage can reliably support the household's water use.

A property that has been occupied successfully for years may have an established history of adequate water supply, but if the yield is unknown, records are unclear or there are concerns about water quantity, Nova Scotia recommends considering a professional yield test by a qualified contractor. Government of Nova Scotia

This can be particularly important when you're planning a household with heavier water demands.


Wells Can Behave Differently Over Time

A single test tells you something about the well at a particular point in time.

It doesn't guarantee that conditions will never change.

Nova Scotia notes that floods, droughts, construction, seasonal weather and other events can affect private wells and recommends ongoing testing rather than treating water testing as something that happens only when a property changes hands. Government of Nova Scotia

Current provincial guidance recommends testing private well water for bacteria at least annually and chemical quality at least every five years, with additional testing when conditions warrant it. Government of Nova Scotia

So the testing you do while buying a home is really the beginning of an ongoing homeowner responsibility.


A Septic System Handles What Leaves the House

If a well deals with what comes into the house, the septic system deals with what goes out.

A typical Nova Scotia on-site sewage disposal system includes a septic tank and a subsurface disposal field, sometimes called a leach field or soil absorption area. Wastewater enters the tank, where solids settle, and the system then uses the disposal field and surrounding soil as part of the treatment process. Government of Nova Scotia

Much of that system is underground.

That means a neatly mowed lawn doesn't tell you much about what's happening beneath it.
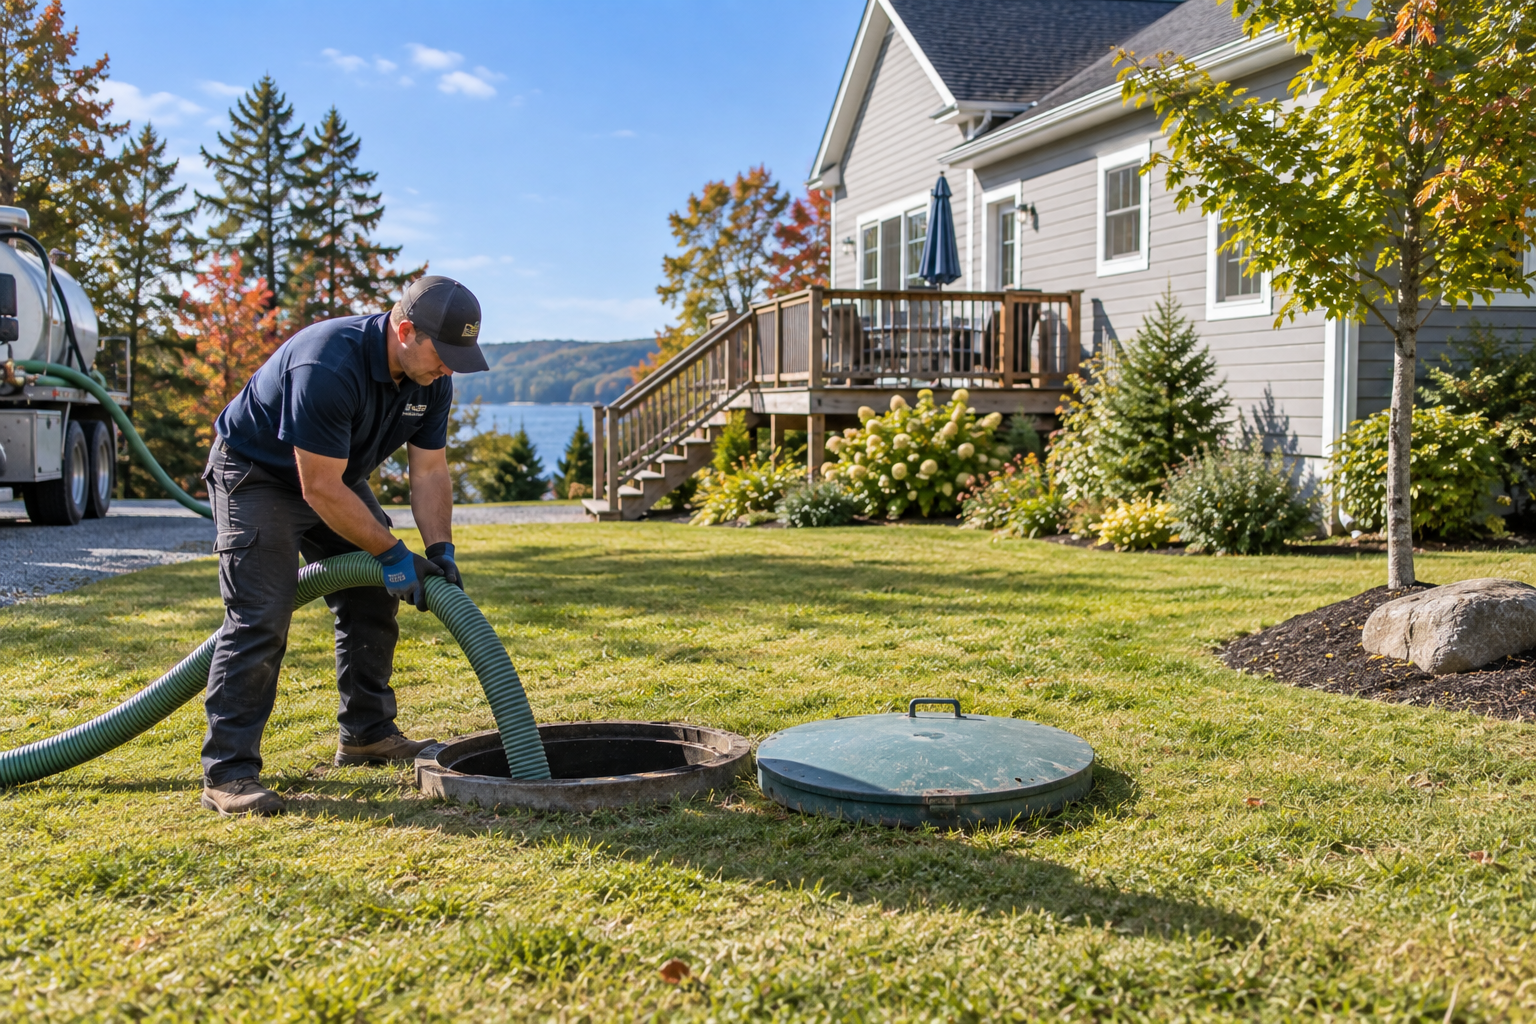
Septic system inspection at a Nova Scotia home

Find Out Where the Septic System Is

One surprisingly basic question is:

Where are the tank and disposal field?

Knowing their location matters for more than an inspection.

You need to understand how the system relates to the house, well, driveway, property boundaries, landscaping and anything you may want to build later.

The disposal field is a functioning part of the property—not simply unused lawn.

Before imagining a garage, pool, large addition or major landscaping project in a particular area, it's worth understanding what's already beneath the ground.
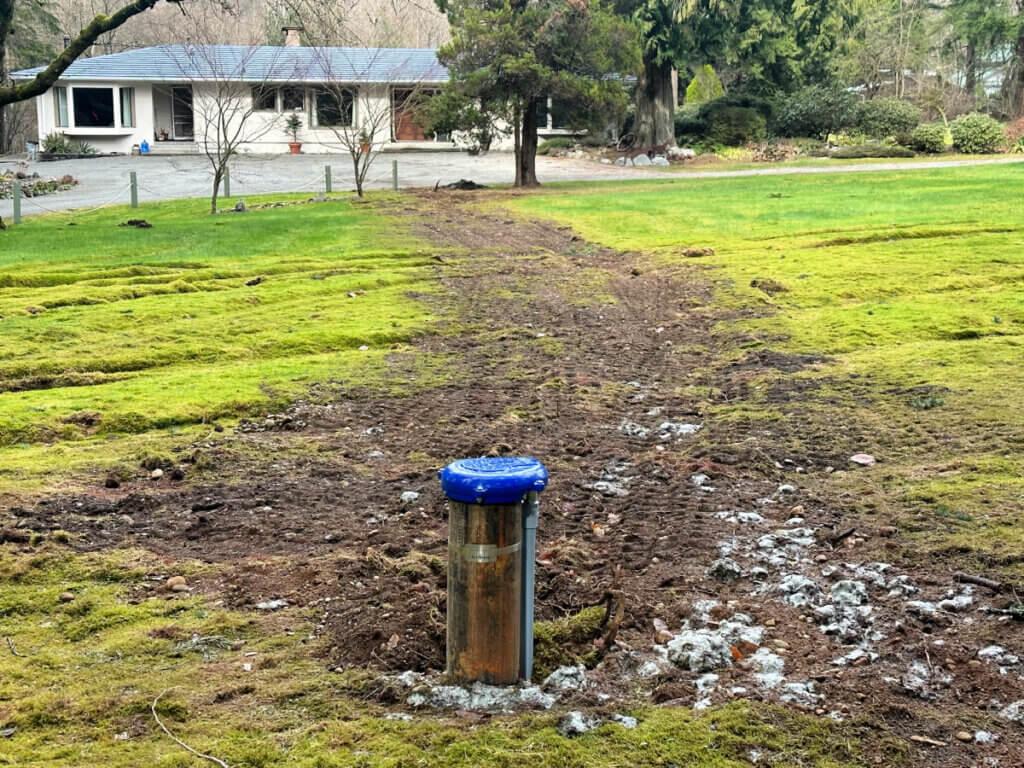
Residential yard containing an on-site septic disposal field

Ask What Is Known About the Septic System

Useful information can include:

  • Approximate age of the system

  • Type of system

  • Location of the tank and disposal field

  • Available installation or design records

  • Pumping and maintenance history

  • Repairs or alterations

  • Previous problems or malfunctions

  • Number of bedrooms or intended design capacity

As with wells, records may be incomplete on an older property.

Missing paperwork isn't the same thing as a failed system, but it can affect how much you know—and therefore what additional investigation you may want before buying.


A Septic Inspection Is Different From a General Home Inspection

A general home inspection can provide valuable information about a house, but specialized systems may require specialized expertise.

A septic investigation may involve locating components, reviewing available records and examining the condition and operation of the system using methods appropriate to the property.

Nova Scotia regulates who may perform various types of on-site sewage work. Professional engineers, qualified persons, installers and septic tank cleaners have different recognized roles within the provincial system. Government of Nova Scotia

The appropriate professional and scope of investigation will depend on what you're trying to determine.

This is why “the home was inspected” shouldn't automatically be interpreted as “the septic system was fully evaluated.”


What Are Possible Signs of a Septic Problem?

Sometimes a problem is obvious.

Other times it isn't.

Things that may warrant further investigation can include:

  • Sewage odours

  • Slow drains or backups

  • Wet or unusually soft areas around the disposal field

  • Unexplained lush growth over part of the field

  • Evidence of previous repairs

  • A system that hasn't been pumped or maintained for a long time

  • Questions about whether the existing system is appropriate for the house

None of these observations alone necessarily tells you exactly what is wrong.

They tell you that it may be time to involve someone qualified to assess the system.


Septic Systems Require Ongoing Maintenance

A septic system isn't something you can simply forget about after closing.

Nova Scotia recommends that septic tanks generally be pumped every two to three years, depending on use, to prevent accumulated solids from reaching and potentially plugging the disposal field. Government of Nova Scotia

How you use the system matters too.

The volume of wastewater entering the system, what gets flushed or poured down drains and how the disposal-field area is treated can all affect its operation.

A properly designed, installed and maintained system can operate reliably for many years. A poorly designed, installed or maintained system can contaminate water supplies or nearby water bodies and can be expensive to repair. Government of Nova Scotia


The Well and Septic System Need to Be Considered Together

It's tempting to investigate the well and septic system as two completely separate items.

On a property, however, they're part of the same environment.

The location and condition of a sewage disposal system can matter to groundwater. Surface drainage can matter to a well. Nearby land uses can also affect water quality.

Nova Scotia identifies sewage disposal systems, petroleum products, road salt, animal waste, landfills, pesticides and seawater intrusion among potential sources of groundwater contamination. Government of Nova Scotia

That's why looking at the whole property matters—not just individual pieces of equipment.


Don't Forget the Neighbouring Properties

Your own property isn't the only thing that can matter.

Depending on lot size, development pattern and local conditions, neighbouring wells, septic systems, agricultural uses, fuel storage and other activities may also be relevant.

That doesn't mean a buyer should become an environmental engineer before purchasing a house.

It means that if something about the property raises a legitimate question, it's worth investigating rather than assuming.

For waterfront properties, the location of wells and septic systems deserves particular attention because of their relationship to nearby lakes, rivers and coastal waters. My guide to buying waterfront property in Nova Scotia explores these and other waterfront-specific considerations.


What If a Well or Septic Test Finds a Problem?

A problem discovered during due diligence doesn't automatically mean the transaction is over.

The next step is usually to understand:

What exactly was found?

How significant is it?

Can it be corrected?

What would correction involve and cost?

For well water, Nova Scotia recommends confirming unsafe results because temporary conditions or sampling errors can sometimes affect a test. Depending on the issue, possible responses can include disinfection, well work or water-treatment equipment. Government of Nova Scotia

For a septic concern, the appropriate response depends on the nature and extent of the problem. It could range from maintenance or repair to more substantial system work.

The important thing is to get reliable information before deciding how to proceed.
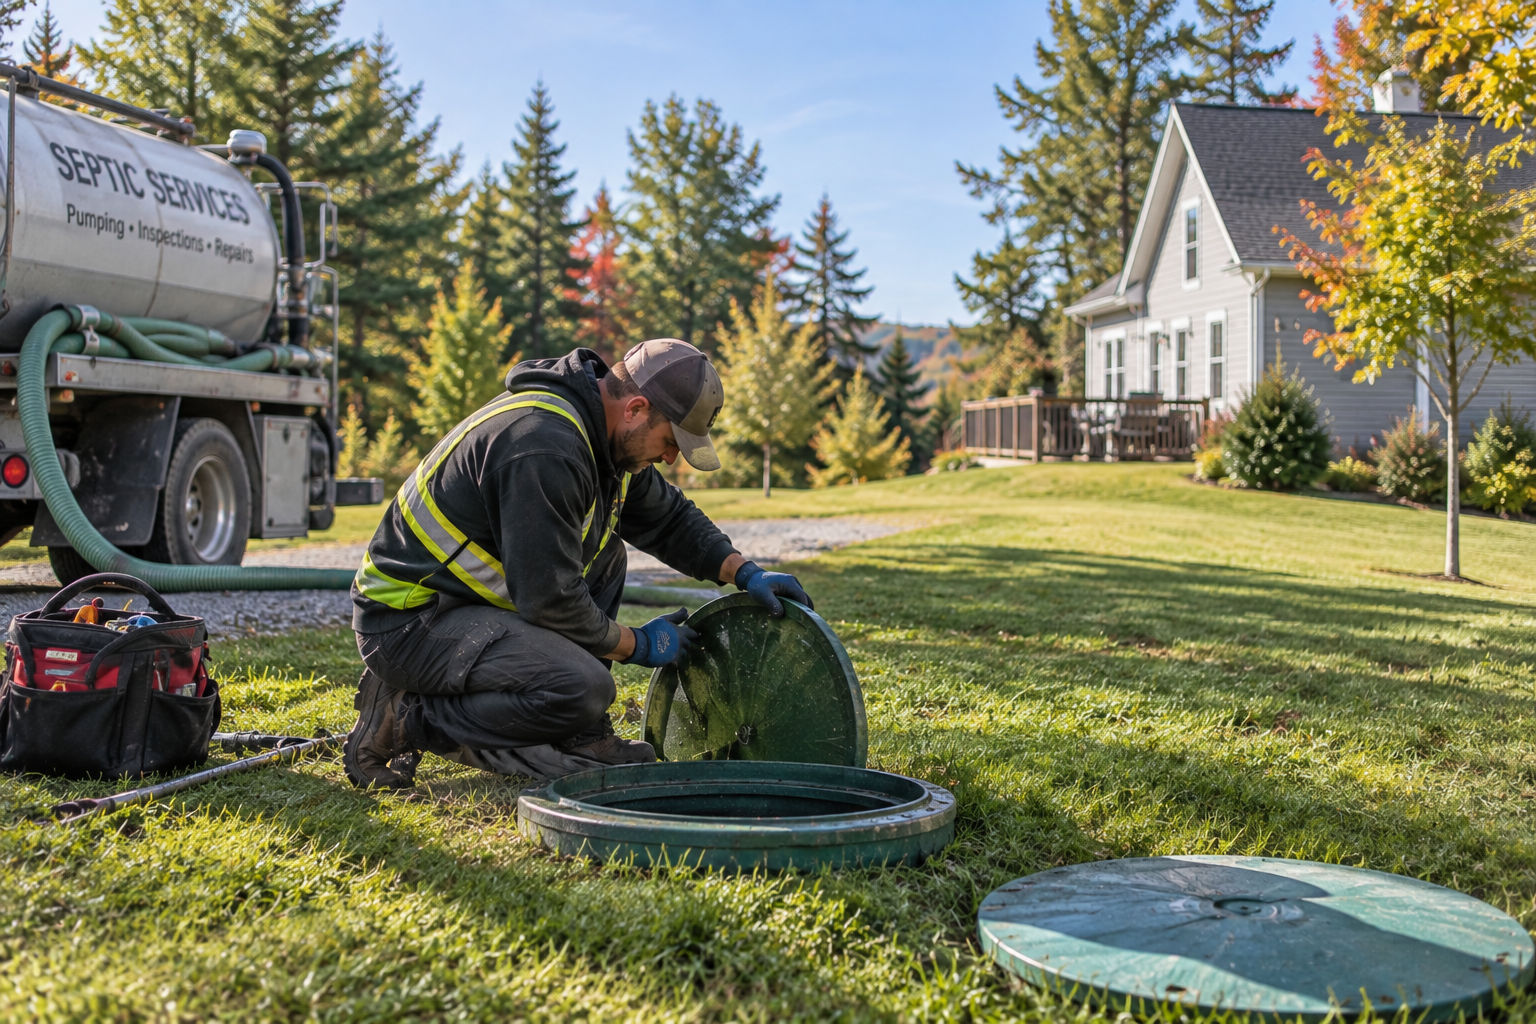
Professional evaluating a septic system at a Nova Scotia home

Can You Replace or Alter a Septic System Anywhere on the Property?

Not necessarily.

Site conditions matter.

Soil, slopes, available area, setbacks and other characteristics can affect the type of on-site sewage system that can be used. Nova Scotia has technical standards governing system selection, design and installation. Systems that meet the provincial standard generally use the notification process; systems that don't meet the standard require an application for approval. Government of Nova Scotia

This can become particularly important if you're considering a property where the existing system may eventually need replacement—or if you're planning an addition that could change the property's requirements.

The fact that a septic system exists today doesn't necessarily tell you what could be installed in the future.


Think About Your Future Plans Before You Buy

Suppose you love a two-bedroom house but already know you'd like to add two more bedrooms.

Or perhaps there's a perfect spot for a future garage, secondary suite or major addition.

Those plans may interact with the property's well, septic system or both.

Before assuming an improvement is possible, investigate what would be required.

A property's current configuration and its future potential are not always the same thing.


Wells and Septic Systems Aren't Automatically a Negative

For buyers accustomed to municipal services, private systems can initially sound like extra risk.

A better way to think about them is as systems you own and are responsible for.

Municipal services usually come with municipal charges and infrastructure you don't control. A private well and septic system shift more responsibility directly to the homeowner.

Neither arrangement automatically makes one property better than another.

What matters is understanding the systems, their condition and the responsibilities that come with them.


What Should a Buyer Investigate?

When I'm helping a buyer consider a Nova Scotia property with a private well and septic system, the goal isn't simply to check two boxes on a list.

It's to build a clearer picture of the property.

That may mean understanding:

  • What type of water supply serves the home

  • What is known about the well and its construction

  • Recent accredited-laboratory water results

  • Whether water quantity is a concern

  • Any water-treatment equipment

  • Where the septic tank and disposal field are located

  • What records exist for the septic system

  • Its age and maintenance history

  • Whether a specialized septic investigation is appropriate

  • How both systems affect future plans for the property

Not every property will require exactly the same investigation.

The right questions depend on the home.


Understand the Systems You Are Taking Ownership Of

A well and septic system shouldn't be mysterious parts of a Nova Scotia property.

They should be understood in much the same way as the roof, heating system, electrical service or foundation: What is there? What condition is it in? What maintenance does it need? And is it suitable for the way you plan to use the home?

Those questions are much more useful than simply asking whether a property “has well and septic.”

Buying a home is ultimately about understanding what you're taking ownership of—not just what you can see during a showing.


Part of the Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process in Nova Scotia.

Read

What Type of Home Is Right for You?

When buyers start looking for a home, it's easy to begin with a familiar checklist.

Three bedrooms. Two bathrooms. A garage. A certain price range.

Those things matter, but they don't necessarily tell you what type of property will work best for the way you actually want to live.

In Nova Scotia, buyers can encounter everything from newer subdivisions and century homes to condominiums, mini homes, rural acreages, waterfront properties and seasonal cottages—sometimes within a relatively small geographic area.

Each can offer a very different ownership experience.

Before narrowing your search too much, it can be helpful to think beyond the house itself and ask a bigger question:

What do you want owning your home to be like?


Start With the Lifestyle, Not the House Style

It's tempting to decide that you want a bungalow, two-storey home or particular architectural style.

But some of the more important differences between properties aren't architectural at all.

Think about what you want from the property.

Do you want enough land for a large garden?

Would you rather have very little exterior maintenance?

Do you need a workshop?

Do you travel frequently and want something easier to leave unattended?

Would you enjoy maintaining several acres?

Do you want to walk to cafés and shops?

Is waterfront part of the dream?

Would you rather renovate an older home or move into something newer?

The answers can lead to very different types of properties.

Finding the right home isn't only about what you can buy. It's about what you actually want to own.


A Conventional Detached Home

For many buyers, a detached house is the starting point.

You own the home and, in most cases, the land beneath and around it. That gives you a degree of independence that appeals to many homeowners.

But detached homes themselves vary enormously.

A house in town might have municipal water and sewer, a small yard and sidewalks nearby.

Drive ten minutes away and another detached house might have a well, septic system, two acres of land, a long driveway and several outbuildings.

The buildings might look similar while the ownership responsibilities are completely different.

That's why I encourage buyers to look beyond bedrooms and square footage.

The property around the house is part of what you're buying too.

Detached home in an established Nova Scotia neighbourhood

A Condominium Changes What You Own—and What You Share

A condominium can appeal to buyers who want home ownership without taking responsibility for every part of the property themselves.

But buying a condo isn't simply buying an apartment.

You own your individual unit and have an interest in the condominium's common elements. The condominium corporation is responsible for managing and maintaining those common elements, while owners contribute through common-element fees. Government of Nova Scotia

Depending on the development, those shared responsibilities could involve things such as building exteriors, roofs, roads, landscaping, hallways, elevators or other facilities.

That can make ownership more convenient.

It also means you need to evaluate more than the unit you're standing in.

Before purchasing, Nova Scotia recommends reviewing documents including the declaration, bylaws, common-element rules, reserve fund information, estoppel certificate and financial statements. Buyers should also understand the monthly fees, what those fees cover, whether major repairs are anticipated and the financial condition of the condominium corporation. Government of Nova Scotia

Rules can matter too. Depending on the condominium, there may be restrictions involving pets, business use or other aspects of how a unit can be used. Government of Nova Scotia

So don't compare a condo and detached house on purchase price alone.

Compare the ownership experience and total responsibilities as well.

Condominium homes with shared common areas in Nova Scotia

Mini Homes and Manufactured Homes

Mini homes can provide another path to home ownership in Nova Scotia.
Some are located on land that is individually owned. Others are situated in communities where the homeowner owns the home but leases the site beneath it.

That distinction matters.

If the land is leased, you'll want to understand the site arrangement and associated costs in addition to evaluating the home itself.

Financing can also depend on how a manufactured home and the land are structured. For example, Nova Scotia's current Down Payment Assistance Program requires a manufactured home to be permanently attached to property the buyer owns in order to qualify under that program. Government of Nova Scotia

Manufactured homes can also involve legal considerations different from conventional real estate. Nova Scotia's Personal Property Registry, for example, specifically includes mobile/manufactured homes among the types of property against which security interests can be registered. Government of Nova Scotia

That doesn't make a mini home inherently more difficult to buy.

It means you need to understand exactly what is included in the purchase and how ownership is structured.


Modular Doesn't Mean the Same Thing as a Mini Home

These terms are sometimes used interchangeably, but they shouldn't be.

A modular home is generally constructed in sections in a controlled environment and then assembled on a permanent foundation at the property.

Once completed, it may function much like another conventionally constructed house.

The construction method itself doesn't tell you whether a home will suit you.

Instead, evaluate the finished property as you would another home: its foundation, construction, heating, insulation, services, condition, location and land.

If you're uncertain about what type of construction you're looking at, find out rather than relying on the terminology used casually in conversation.


Older Homes Can Offer Something Newer Homes Can't

Nova Scotia has a large inventory of older homes, particularly in established communities.

For some buyers, that's part of the appeal.

Older homes can offer mature neighbourhoods, established trees, distinctive layouts, original woodwork and architectural details that would be difficult or expensive to reproduce today.

They can also require a different kind of due diligence.

Electrical systems, plumbing, foundations, insulation, heating equipment, roofing, additions and previous renovations may represent several generations of work.

Age alone doesn't tell you whether a house is good or bad.

A well-maintained 120-year-old house may be in better condition than a much newer home that hasn't been cared for.

The better question is:

What has happened to this particular house during its lifetime?

We'll explore that in much greater detail in Older Homes in Nova Scotia: What Buyers Should Look For.

Older homes in an established Nova Scotia community

Old Doesn't Automatically Mean Heritage

An older house and a registered heritage property aren't necessarily the same thing.

Nova Scotia has both provincial and municipal heritage registries, and a property can appear on one or both. Registered properties are subject to the Heritage Property Act and applicable heritage protections. CCTH

If you're considering a registered heritage property, understand its status and what that means before assuming you can make particular exterior changes or alterations.

But don't assume every century home has heritage restrictions simply because it's old.

Verify the actual property.


New Construction Offers a Different Set of Decisions

For some buyers, the appeal of new construction is straightforward.

New finishes.

Modern layouts.

Current building systems.

Less history to investigate.

Potentially fewer immediate repairs.

But buying new doesn't eliminate due diligence—it changes it.

You may need to understand exactly what the purchase price includes, which finishes and appliances are part of the agreement, whether landscaping and driveways are complete, how deficiencies will be handled and when the home will actually be ready for occupancy.

If you're buying before construction is complete, you're also making decisions based partly on plans, specifications and representations rather than solely on a finished building.

There may also be programs that apply specifically to new homes. For example, Nova Scotia currently offers an eligible first-time buyer rebate of up to $3,000 on a newly built home. Government of Nova Scotia

Programs and eligibility requirements can change, so verify what's available when you're actually preparing to buy.


A Home With Acreage Is More Than a Bigger Yard

A few acres can dramatically change what a property allows you to do.

Maybe you want privacy.

A large garden.

A workshop.

Space for animals.

Woodland.

Or simply some distance between you and your neighbours.

But don't evaluate acreage based only on the number in the listing.

Five acres of open, level land is very different from five acres that are mostly wooded, wet or steep.

Consider how much of the property is actually usable for what you want?

Then consider what you'll have to maintain.

More land can mean more mowing, tree maintenance, fencing, drainage, snow clearing, driveway maintenance and outbuildings.

If you're specifically looking for substantial acreage, barns or agricultural potential, we'll go much deeper in Buying a Hobby Farm or Acreage in Nova Scotia.
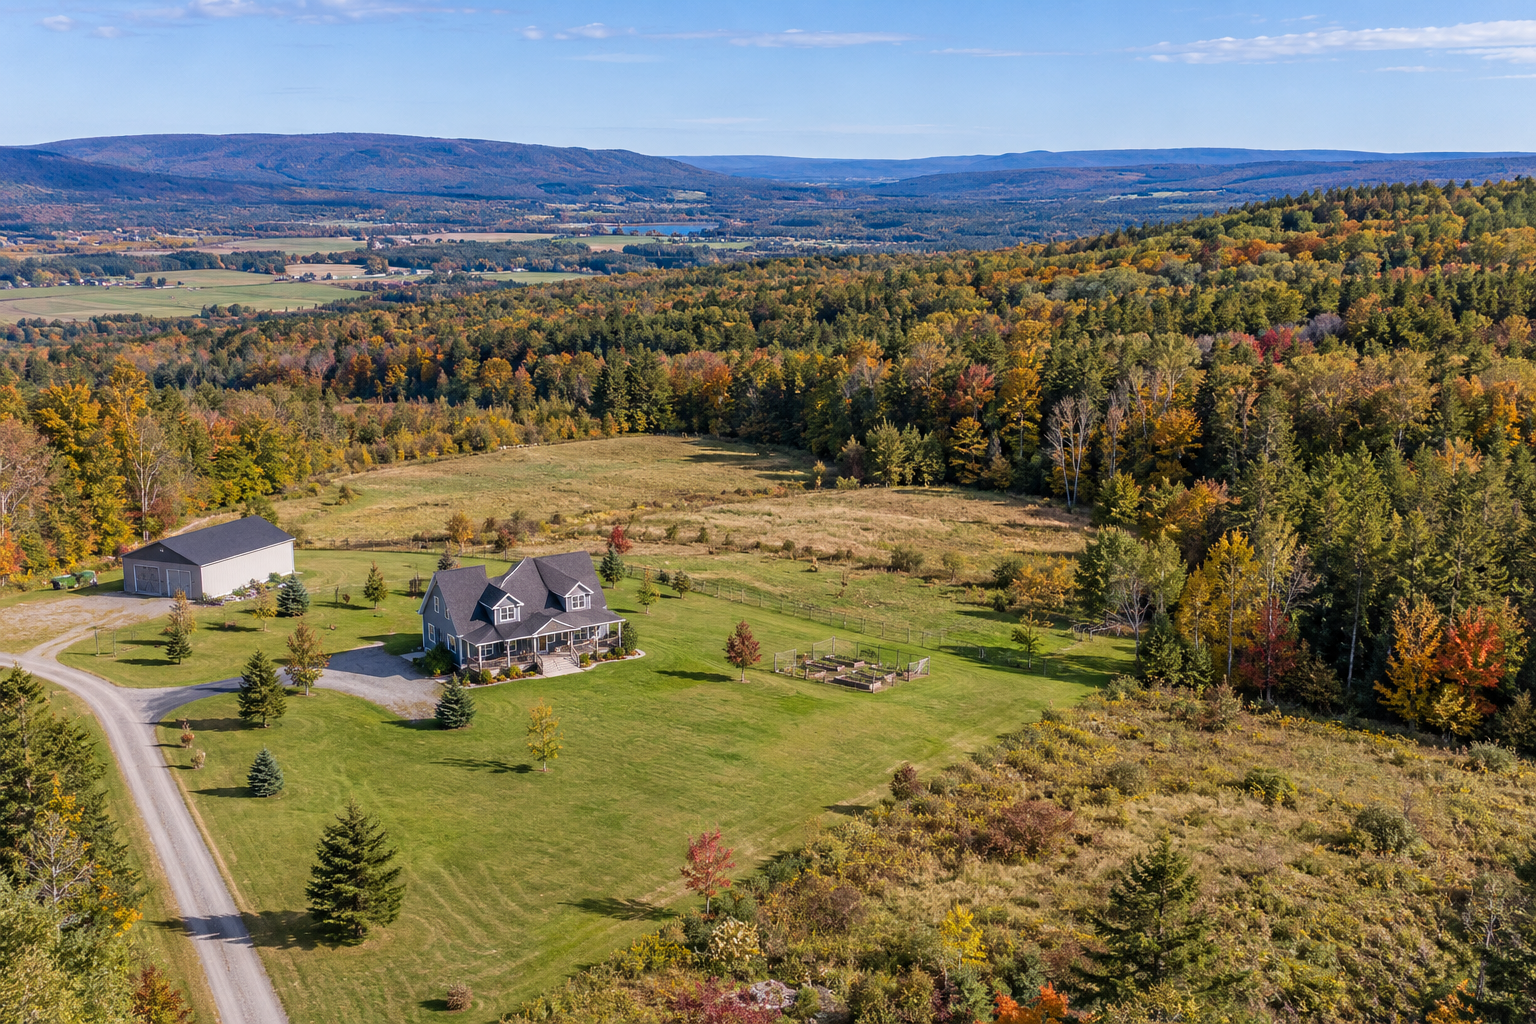
Nova Scotia country home with open acreage and woodland

Waterfront Changes the Property, Not Just the View

For many buyers moving to Nova Scotia, waterfront is high on the wish list.

And it's easy to understand why.

But waterfront should be evaluated as a property characteristic—not simply as scenery.

Different properties can have very different shorelines and access.

Consider what you're actually hoping to do.

Do you want to swim?

Launch a kayak?

Keep a boat?

Walk along the shore?

Have an unobstructed view?

Or is simply being beside the water enough?

A beautiful waterfront property may not necessarily provide the type of water access you imagined.

You'll also want to investigate boundaries, access, erosion or flooding considerations, insurance and any restrictions that could affect what you intend to do with the property.

We'll treat this as its own subject in Buying Waterfront Property in Nova Scotia: What Should You Investigate?

Nova Scotia waterfront home with direct shoreline frontage

A Cottage or Seasonal Property May Not Be a Year-Round Home

A cottage can look very much like a small house in listing photographs.

That doesn't necessarily mean it was designed or equipped for year-round living.

Some seasonal properties may have different water systems, limited insulation, seasonal road access or other services that aren't intended for twelve-month occupancy.

If you're buying a cottage to use as a cottage, those limitations may be perfectly acceptable.

If you're planning to turn it into your permanent home, they're much more important.

Don't assume that because you could stay somewhere in January, the property was designed to function as a conventional year-round residence.


A Property With Outbuildings Can Change What's Possible

A garage, barn or workshop can completely change whether a property works for you.

For someone who wants woodworking space, vehicle storage, equipment storage or room for a small business, the outbuilding might be nearly as important as the house.

But treat it that way during your evaluation.

Look at its structure.

Roof.

Foundation.

Electrical service.

Access.

Condition.

And whether your intended use is permitted.

A large old barn can be an extraordinary asset to the right buyer.

It can also be a very large building that needs a new roof.


Multi-Unit Properties Require a Different Mindset

Some buyers consider a duplex or another property with an additional unit because they want rental income, space for extended family or greater flexibility.

That changes the evaluation again.

Instead of looking only at whether the home suits you, you'll need to understand the additional unit, how it's currently used, whether it's legally established where relevant, the utilities, tenancy situation if occupied and the financial implications.

If rental income is necessary for your financing plan, discuss that with your lender early rather than assuming all potential rent will automatically be treated the way you expect.

A multi-unit property can be an excellent fit for some buyers, but it isn't simply a detached home with an extra kitchen.


The Cheapest Home Isn't Necessarily the Cheapest to Own

This is where comparing different property types gets interesting.

Imagine several properties with similar purchase prices.

One might be a condo with monthly common-element fees.

Another might have no condo fees but require you to maintain the roof, driveway and exterior yourself.

A rural home might have a well, septic system and several acres.

An older home might have inexpensive taxes but upcoming improvements.

A newer home might cost more initially but require fewer immediate projects.

A waterfront property may bring different insurance considerations.

A mini home on leased land may include ongoing site costs.

The purchase price tells you what it costs to acquire the property.

It doesn't necessarily tell you what it costs—or requires—to own it.


Think About the Home You'll Want Five Years From Now

You can't predict everything.

But it's worth looking beyond what works today.

If you're planning a family, will the property still work?

If you're approaching retirement, do you really want several acres to maintain?

If you expect to work from home, is there suitable space and connectivity?

If you love travelling, will you be comfortable leaving a rural property unattended?

If you've always wanted a workshop, will buying a property without one leave you searching again in two years?

You don't need to buy your "forever home."

But understanding where your life may be heading can prevent you from choosing a property that already conflicts with those plans.


Don't Eliminate a Property Type Too Quickly

Sometimes buyers begin with strong assumptions.

"I don't want a condo."

"I'd never buy an old house."

"I need at least five acres."

"I don't want a mini home."

"I only want waterfront."

Those preferences may ultimately be completely right for you.

But it's useful to understand why.

If you dislike condo rules and shared decision-making, that's meaningful.

If you simply assumed condos were all high-rise apartments, that's different.

If you need acreage for horses, acreage is a genuine requirement.

If you want acreage because you want privacy, there may be properties on much smaller lots that accomplish the same thing.

The goal isn't to talk yourself into a property type you don't want.

It's to make sure you're solving the right problem.


Home buyers evaluating a property in Nova Scotia

Compare Responsibilities, Not Just Features

When you're deciding what type of home is right for you, try making two lists.

The first is probably familiar:

Bedrooms.
Bathrooms.
Garage.
Location.
Price.
Lot size.

For the second, think about ownership:

How much maintenance do I want?

How much land do I genuinely want to look after?

Which responsibilities am I comfortable taking on myself?

Do I want shared amenities enough to accept shared rules and costs?

Do I want a finished home or a project?

How important are privacy, walkability, waterfront or outbuildings?

What will this property require from me after I get the keys?

That second list often tells you much more about the type of home you should be looking for.


There Isn't One "Best" Type of Home

A condo isn't inherently better or worse than a detached house.

A century home isn't automatically a money pit.

A new home isn't automatically problem-free.

A rural acreage isn't automatically more work than you want.

And a smaller property isn't automatically easier to own.

They're simply different.

The right property is the one where the home, location, responsibilities and costs fit the way you want to live.

Once you understand that, searching for a home becomes much more focused—and you're in a better position to recognize the right property when you find it.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

Town or Country? What Changes When You Buy Outside a Nova Scotia Town

For many home buyers, one of the attractions of Nova Scotia is the ability to have more space without necessarily being hours away from a community.

Drive a few minutes outside many towns in the Annapolis Valley or along the South Shore and the landscape can change quickly. Neighbourhood streets give way to larger lots, fields, woodland, long driveways and homes with considerably more privacy.

That can be exactly what you're looking for.

But buying outside a town can also mean taking responsibility for things that might otherwise be provided as municipal services.

The difference isn't simply town versus country. Two properties only a few kilometres apart can have very different water systems, wastewater systems, road access, internet options and maintenance requirements.

Understanding those differences before you buy can help you decide whether country living actually suits the way you want to live.


Rural Doesn't Necessarily Mean Remote

When buyers hear "rural property," they sometimes picture a farmhouse on 50 acres at the end of a dirt road.

That's only one version of rural Nova Scotia.

You might find a conventional three-bedroom home on an acre just outside Middleton, a waterfront property outside Chester, a house on several acres near Annapolis Royal or a home surrounded by farmland only minutes from Wolfville.

You can therefore have a rural property without being particularly remote.

That's an important distinction.

The question isn't simply how far the house is from town. It's which services stop at the property line—and which responsibilities become yours.


Private drilled well serving a rural home in Nova Scotia

Your Water May Come From a Well

One of the most common differences outside serviced areas is the water supply.

Instead of receiving treated municipal water, a property may have its own drilled or dug well.

That means the homeowner is responsible for the water supply and its maintenance. Nova Scotia Environment also recommends testing private well water because water that looks, smells and tastes normal can still contain bacteria or other contaminants. The Province even provides a specific private-well checklist for real estate transactions. Government of Nova Scotia

As a buyer, you'll want to understand things such as:

  • What type of well serves the property?

  • Where is it located?

  • How much water can it provide?

  • What is the water quality?

  • Is there treatment equipment?

  • Are there previous water test or well records?

A private well shouldn't automatically make a property less desirable. They're common throughout Nova Scotia.

It simply means there's another important system to understand.

We'll cover this much more thoroughly in the dedicated Well & Septic Systems: What Nova Scotia Home Buyers Need to Know guide.


Wastewater May Be Your Responsibility Too

Where there's no municipal sewer, you'll commonly find an on-site septic system.

The homeowner—not a municipality—is responsible for maintaining that system and making sure it operates properly. Nova Scotia guidance specifically places responsibility for an adequate and properly functioning on-site sewage system on the landowner. Government of Nova Scotia

For a buyer, the important questions include:

Where is the septic tank?

Where is the disposal field?

What type of system is installed?

How old is it?

Has it been maintained?

Are there records?

Should it be inspected before you buy?

The location can matter too. A septic field occupies part of the property, and what you can build, plant or drive over in that area may be limited.

Again, septic systems are a normal part of owning many Nova Scotia homes. The key is understanding the system you're taking responsibility for.


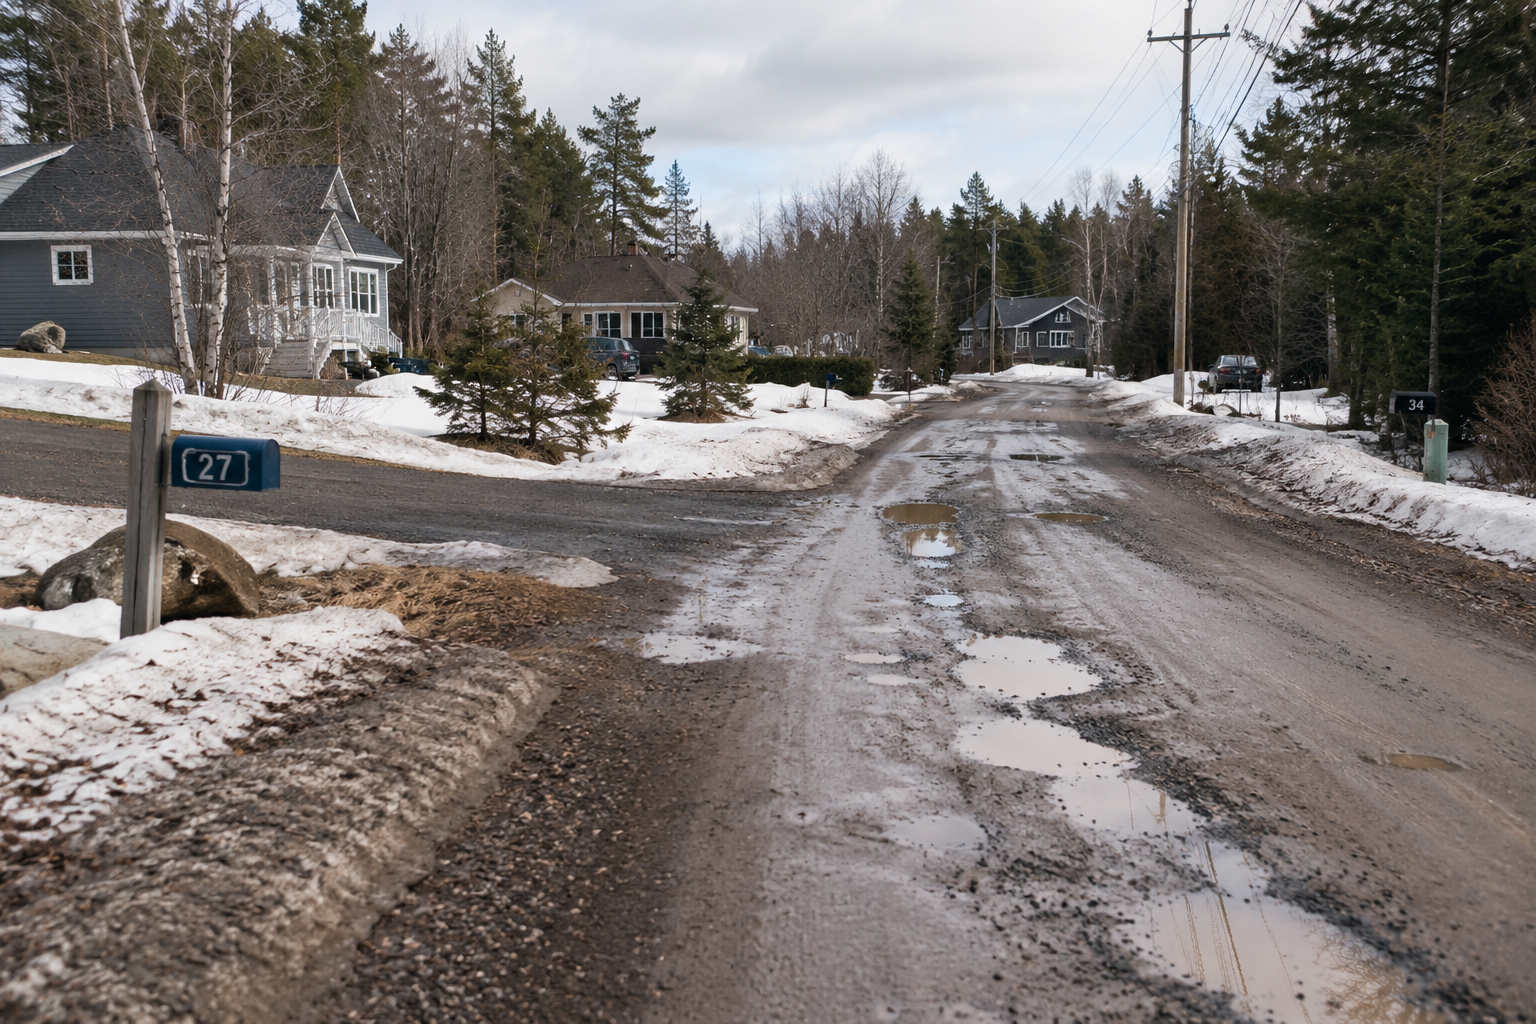
Private rural road serving homes in Nova Scotia

The Road in Front of the House May Not Be Public

A paved road doesn't necessarily mean municipal or provincial maintenance, and a gravel road isn't necessarily private.

When you're looking at a property outside town, determine who owns and maintains the road.

If it's private, you'll want to understand your legal right to use it and how maintenance is handled.

That can include:

  • grading and gravel,

  • pothole repairs,

  • ditching and drainage,

  • snow removal,

  • brush cutting,

  • culvert work, and

  • sharing expenses with other property owners.

Rights-of-way and access can have legal implications as well. Nova Scotia's Private Ways legislation exists partly because access to a public street can affect services such as waste collection and utility repair. Nova Scotia News

A private road isn't necessarily a reason not to buy.

But "Who plows this road?" is a much better question to ask in July than after the first major snowfall.


Then There's Your Own Driveway

Country properties often have longer driveways.

That sounds like a minor detail until you own one.

A 150-metre driveway may need snow clearing, grading, gravel, drainage work and occasional repairs. If it's steep, shaded or exposed to drifting snow, winter maintenance can become even more important.

Look at how water moves around the driveway as well.

Poor drainage can wash gravel away, create potholes or turn sections into mud during spring thaw.

When viewing a rural property, don't treat the driveway as simply the route to the house.

It's part of the property you're buying and maintaining.


Rural Nova Scotia homes where internet and cell service can vary by address

Internet Should Be Checked at the Actual Address

Internet access across Nova Scotia has improved considerably, but buyers should still verify service at the specific property.

Don't assume that because high-speed internet is available in a community, every address has identical service.

The available provider, connection type and actual service options can vary.

This becomes particularly important if you're working remotely, running a business from home, streaming heavily or relying on internet-based telephone service.

Cell service deserves the same attention.

Reception can vary because of terrain, distance from towers and even where you stand on a particular property.

If connectivity is essential, investigate it before making the location part of your lifestyle.


Power Outages May Feel Different in the Country

A power outage affects any home, but some rural properties depend on electricity for more of their essential systems.

For example, a private well typically requires an electric pump. If the power goes out, your water supply may be affected unless you have appropriate backup arrangements.

Internet equipment also requires power, and Nova Scotia's 911 guidance notes that internet-based VoIP calling will not work if either power or internet service is interrupted. Government of Nova Scotia

That's one reason generators are common at some Nova Scotia properties.

If you're considering a home with a generator, determine what type it is, what it powers and how it's connected rather than assuming the presence of a generator means the entire house operates normally during an outage.


Heating Can Be Different Too

Country homes can expose buyers to a wider variety of heating systems.

You may encounter:

  • heat pumps,

  • oil-fired boilers or furnaces,

  • electric baseboards,

  • wood stoves,

  • pellet stoves,

  • wood furnaces,

  • propane systems, or

  • combinations of several systems.

Some older homes may have multiple generations of heating equipment still in use.

The important question isn't simply "What heats the house?"

It's also:

What does it cost to operate?

What maintenance does it require?

Is the equipment insurable?

What happens during a power outage?

Is there a backup heat source?

We'll explore these questions separately in Heating a Home in Nova Scotia: Oil, Heat Pumps, Wood, Electric & More.


Garbage Collection, Deliveries and Other Services Can Change

Moving outside town can also change some less obvious parts of daily life.

Garbage and recycling collection may operate differently.

Courier companies may treat your address differently.

Food delivery may disappear entirely.

Snowplow timing may matter more.

A contractor who can reach a property in town easily may charge additional travel time to reach a more remote location.

None of these things individually should determine where you live.

But together they can affect what everyday life feels like.


Emergency Access Is Worth Thinking About

Nova Scotia uses civic addressing to identify the location of homes and other properties. Civic addresses are important not only for 911 but also for mail, utilities, municipal permitting and other services. GeoNOVA

For rural properties, make sure the civic number is clearly visible from the road. The Province specifically recommends posting it where emergency responders can see it quickly, including at night. Government of Nova Scotia

Also look at the physical access to the house.

Could an emergency vehicle reasonably get up the driveway?

Are there low branches?

Is there enough width?

Would a steep or poorly maintained driveway become difficult during winter?

These aren't questions most buyers think about while standing in a sunny yard during a June showing, but they're worth considering.


Nova Scotia country home with acreage and land to maintain

More Land Usually Means More to Maintain

One of the attractions of moving outside town is space.

But acreage and usable land aren't necessarily the same thing.

A five-acre property could contain a large lawn, forest, wet areas, steep terrain, gardens or some combination of all of them.

Before becoming excited about the acreage number, ask yourself what you'll actually do with the land.

A large lawn means mowing.

A wooded property may involve tree maintenance.

Long boundaries can mean fences.

A large driveway needs upkeep.

Older outbuildings require maintenance even if you aren't using them.

If what you really want is privacy, you may not need ten acres to get it.

Sometimes the shape of the property, surrounding land uses and location of neighbouring homes matter more than the total acreage.


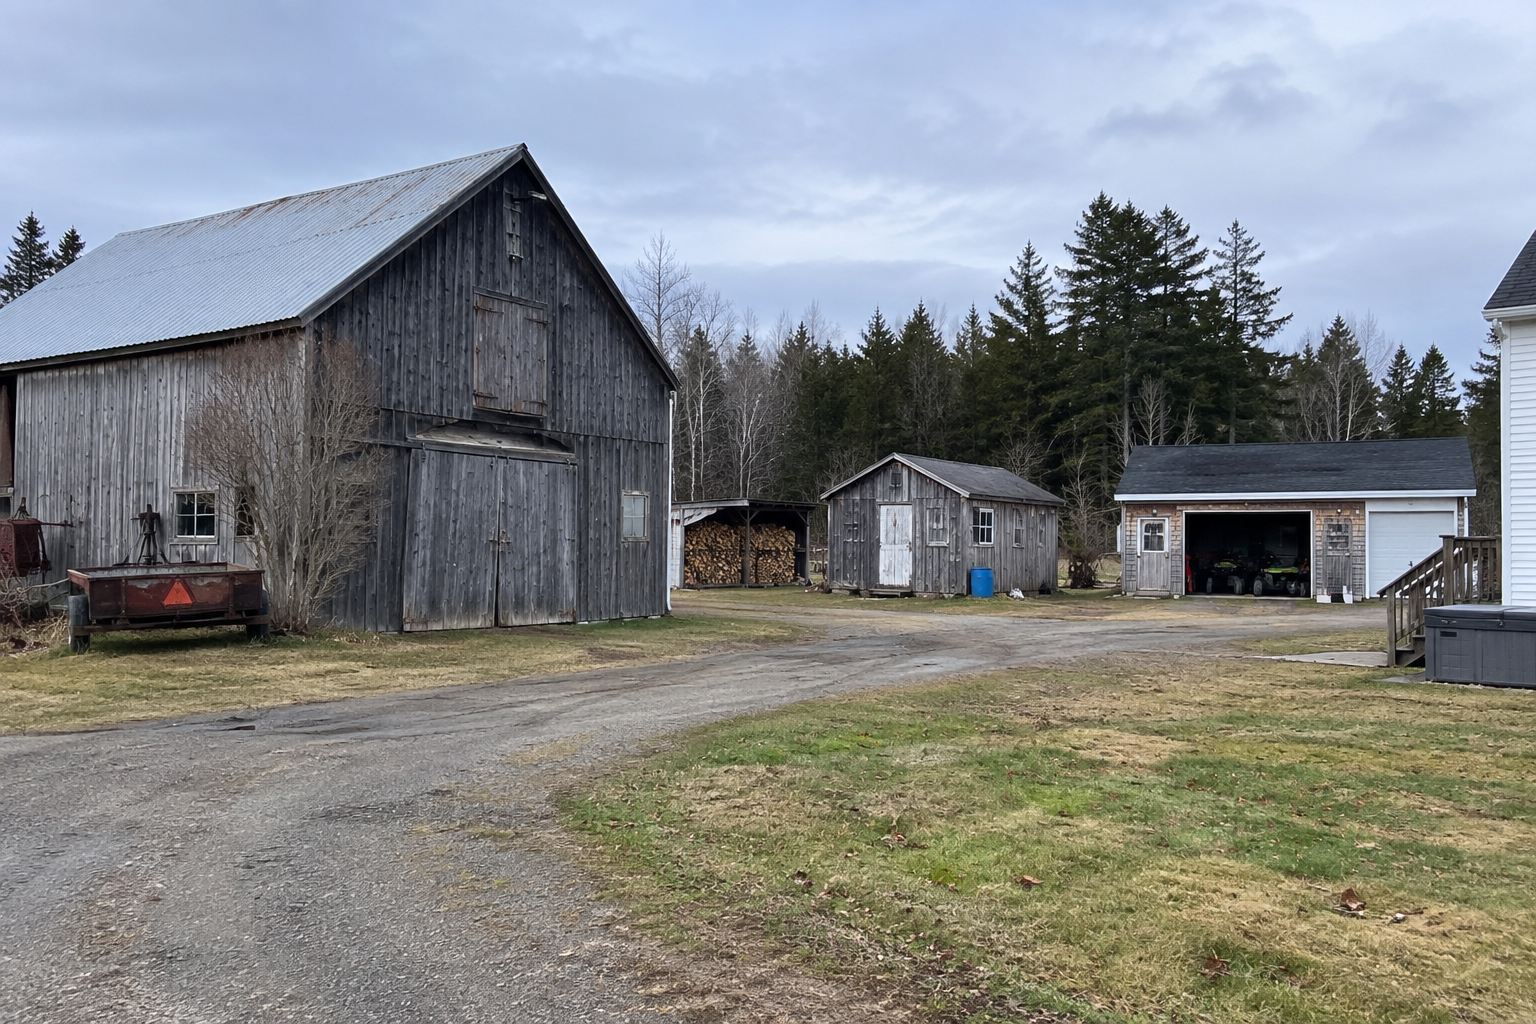
Outbuildings on a rural Nova Scotia property

Outbuildings Deserve Their Own Inspection

Country properties often come with things you won't encounter on a conventional town lot.

Garages.

Workshops.

Barns.

Sheds.

Greenhouses.

Old farm buildings.

They're easy to view as bonuses, particularly if you've always wanted a workshop or extra storage.

But an outbuilding can also have its own foundation, roof, electrical service, structural issues and maintenance costs.

If a building matters to your decision to buy the property, don't give it a five-second glance while spending an hour inspecting the house.

Understand what you're getting.


Check What You Can Actually Do With the Property

More land doesn't automatically mean fewer rules.

If you're buying acreage because you want chickens, horses, a large workshop, a home business, another dwelling or some other specific use, investigate whether that use is permitted.

Municipal zoning and land-use rules still apply outside towns.

There may also be restrictions associated with the property itself.

This becomes particularly important when buyers start looking for hobby farms and larger acreages, which we'll cover separately in Buying a Hobby Farm or Acreage in Nova Scotia.
The rule I suggest is simple:

If your reason for buying the property depends on being able to do something specific there, investigate that before you buy—not afterward.


Privacy Can Come With Different Neighbours

One of the surprises for some buyers moving from an urban or suburban area is that having fewer residential neighbours doesn't necessarily mean having fewer neighbouring activities.

A rural property could be beside:

  • agricultural land,

  • a working farm,

  • woodland,

  • commercial activity,

  • an aggregate operation,

  • seasonal properties, or

  • land that could eventually be developed.

That beautiful field behind the house may not belong to the property you're buying.

Find out what surrounds the property and, where it matters, how neighbouring land is currently used.

You don't need to dislike farming to discover that agricultural activity beside your bedroom window is different from looking at a pastoral landscape in a listing photograph.


Town Services Have Value—Even When You Don't Think About Them

It's easy to compare two houses and conclude that the country property offers more for the money.

Sometimes it does.

But part of the comparison should include the services attached to each property.

A town property might include municipal water, sewer, paved road access, sidewalks and closer proximity to everyday services.

A country property may offer more land and privacy while asking the homeowner to manage a well, septic system, driveway, private road or additional buildings.

Neither arrangement is inherently better.

You're simply paying for—and taking responsibility for—different things.


Rural Nova Scotia home offering space and privacy outside town

Country Living Can Be a Great Fit

This article isn't meant to make buying outside town sound complicated.

For many people, the additional responsibility is a very worthwhile trade for what they gain.

More privacy.

More space.

Room for a workshop.

A large garden.

A few acres for animals.

Woodland.

Waterfront.

Dark skies.

Or simply not having another house ten metres away.

The important part is understanding what comes with that choice.


Look Beyond the House

When you're comparing a town property with one farther into the countryside, don't stop at bedrooms, bathrooms and square footage.

Ask:

Where does the water come from?

Where does the wastewater go?

Who maintains the road?

Who clears the snow?

What internet and cell service are actually available?

How is the home heated?

What else on the property will I have to maintain?

Can I use the property the way I intend to?

Those answers give you a much clearer picture of what owning the property will actually be like.

And that's ultimately the point of the Buyer Resource Centre: not simply helping you find a house, but helping you understand what you're buying before you make the decision.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

How to Choose Where to Live in Nova Scotia

When you're buying a home, it's easy to focus on the property itself.

How many bedrooms does it have? Is the kitchen big enough? How much land comes with it? What kind of heating system does it use?

But there's another decision that can have just as much impact on how much you enjoy the home:

Where do you want to live?

In Nova Scotia, moving even a relatively short distance can change your commute, access to services, internet options, property taxes, water and wastewater systems, road maintenance and the type of property available to you.

The right location isn't necessarily the most popular town or the shortest drive to Halifax. It's the place that works for the way you want to live.


Start With Your Everyday Life

Before comparing communities, think about what an ordinary week will look like after you move.

Where will you work?

How often will you need to commute?

Do you want to walk to shops and restaurants, or are you comfortable driving for almost everything?

Will you regularly need access to healthcare, recreation, schools, groceries or other services?

Do you want neighbours nearby, or would you rather have more privacy and space?

For some buyers, being able to walk downtown for coffee is important. Someone else may happily drive 20 minutes for groceries if it means having several acres and no neighbours in sight.

Neither choice is inherently better.

The important part is recognizing which compromises you'll actually be happy living with.


Don't Choose a Community From the Map Alone

Distances in Nova Scotia can be deceptive.

Two properties might appear similarly located on a map while offering very different day-to-day experiences.

The route matters.

A 25-minute drive primarily on Highway 101 is different from 25 minutes on winding secondary roads. Winter conditions, traffic patterns and the direction of your commute can also affect how a location feels once you're making the trip regularly.

If commuting matters, don't just look at the number of kilometres between the house and your destination.

Drive the route.

Ideally, drive it around the time you would normally travel.

Something that seems perfectly reasonable while browsing listings on your computer may feel very different when you're doing it twice a day.


Town, Village or Countryside?

One of the biggest decisions for many Nova Scotia buyers is how close they want to be to a town or service centre.

Living in or near communities such as Wolfville, Kentville, Berwick, Middleton, Annapolis Royal, Chester or Liverpool can put shops, restaurants, recreation and other services relatively close to home.

Move farther outside those centres and you may find larger lots, more privacy, different property types and more rural surroundings.

But there's a trade-off.

The farther you move from services, the more likely you are to depend on a vehicle for everyday life.

That can be exactly what you want. Just make sure it's a deliberate choice rather than something you discover after moving.

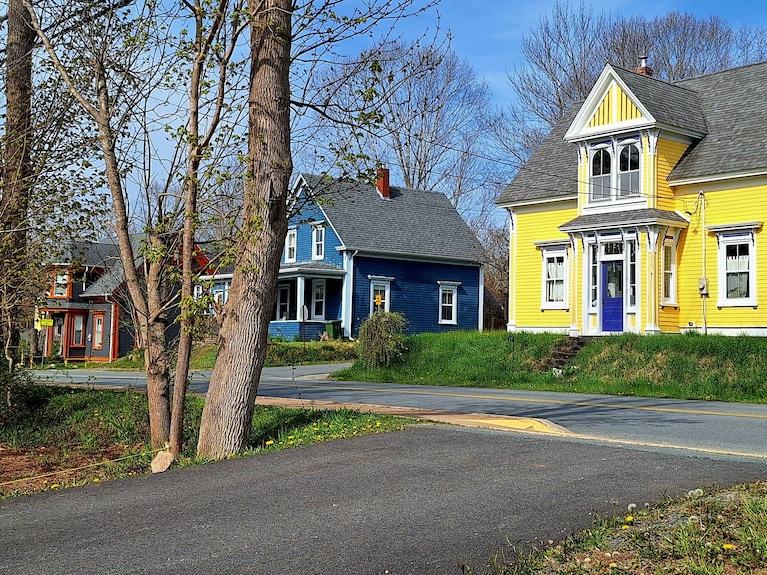
Residential streetscape in a Nova Scotia community

Municipal Services Can Change From One Property to the Next

Don't assume two nearby homes have the same services.

One property may have municipal water and sewer while another a short distance away relies on a private well and septic system.

Municipal infrastructure varies by community and location. Nova Scotia municipalities are responsible for a range of infrastructure and services, including water, wastewater, stormwater, roads and other community infrastructure, but what's actually available depends on the municipality and the particular property. Nova Scotia News

This affects more than convenience.

If you're comparing properties, find out:

  • Is the property on municipal water or a private well?

  • Is wastewater handled by municipal sewer or a septic system?

  • Who maintains the road?

  • Is garbage and recycling collection available?

  • Are there municipal services or charges associated with the property?

These aren't reasons to avoid a particular location.

They're simply part of understanding what you're buying.


Internet and Cell Service Deserve More Attention Than They Usually Get

This is especially important if you work from home.

Don't assume that because a property has internet service, it has the kind of internet service you need.

Availability, provider, technology and speed can vary by location. Cell coverage can also change surprisingly quickly as you travel through parts of rural Nova Scotia.
If reliable connectivity matters to your work or lifestyle, investigate the specific property rather than relying solely on general coverage maps.

Ask what service the current owner uses, check directly with providers and, when possible, verify what's actually available at the civic address.

A beautiful property can become much less appealing if your workday depends on a connection that doesn't meet your needs.

Rural Nova Scotia home where internet and cell service can be important considerations

Think About the Services You Use Regularly

It's easy to say that you don't mind living 30 minutes from town.

The better question is:

What will you be driving 30 minutes for?

Consider your regular trips:

Groceries. Pharmacy. Healthcare. Work. School. Childcare. Restaurants. Recreation. Hardware stores. Veterinary care. Airports. Family and friends.

You don't need to live beside every service you use.

But understanding where those services are located helps you decide whether the lifestyle makes sense.

Healthcare is particularly worth investigating rather than assuming every community offers the same access. Nova Scotia's healthcare system operates province-wide through provincial health authorities and programs, but facilities and individual services are distributed among communities. Government of Nova Scotia

If proximity to a particular type of healthcare is important to you, research that specifically before choosing an area.


What About Schools?

For buyers with children—or those planning for them—schools can be an important part of choosing a location.

But don't assume that the closest school is necessarily the school associated with a particular address.

School boundaries, grade configurations, transportation and programs can change.

If a particular school or program is important to your decision, confirm the current information directly with the appropriate school authority rather than relying on a real estate listing or an old online map.

The same principle applies to childcare.

Availability can matter just as much as location, so it's worth investigating early if childcare will be an important part of your move.


Your Address Doesn't Always Tell the Whole Story

Nova Scotia geography can be confusing when you're unfamiliar with the province.

A mailing address, community name and municipality aren't necessarily the same thing.

Properties described as being “near Wolfville,” for example, may actually be outside the Town of Wolfville. The same is true around many communities throughout the Annapolis Valley and South Shore.

That distinction can affect municipal services, taxation, planning rules and other aspects of the property.

Nova Scotia's Property Online system contains provincial land ownership information and property mapping, and municipal governments maintain their own planning and service information. Government of Nova Scotia

When the exact jurisdiction matters, verify the property rather than relying solely on the community name used to market it.


Property Taxes Can Be Different Between Communities

Property taxes are another reason to look beyond the purchase price.

Municipal tax rates and services vary, so two similarly priced homes in different locations don't necessarily have the same annual property tax.

There's another important Nova Scotia consideration as well: the Capped Assessment Program, commonly called the CAP.

The seller's current property tax bill may not represent what a buyer will pay after purchasing the property.

We'll cover the CAP separately in the Buyer Resource Centre because it deserves its own explanation.

For now, the important point is simple:

Don't compare locations based only on the current owner's tax bill.


The Road to the Property Matters Too

When viewing a property outside a town centre, pay attention to the road itself.

Is it publicly maintained?

Is it a private road?

Who plows it in winter?

Is there a road maintenance agreement?

What condition is it in?

How steep is the driveway?

A long country driveway can be beautiful in July and considerably more work after a January snowfall.

Private roads aren't automatically a problem, either. But buyers should understand who owns the road, who can use it and how maintenance costs and responsibilities are handled.

These questions become particularly important when looking at cottages, waterfront homes, acreages and more remote properties.

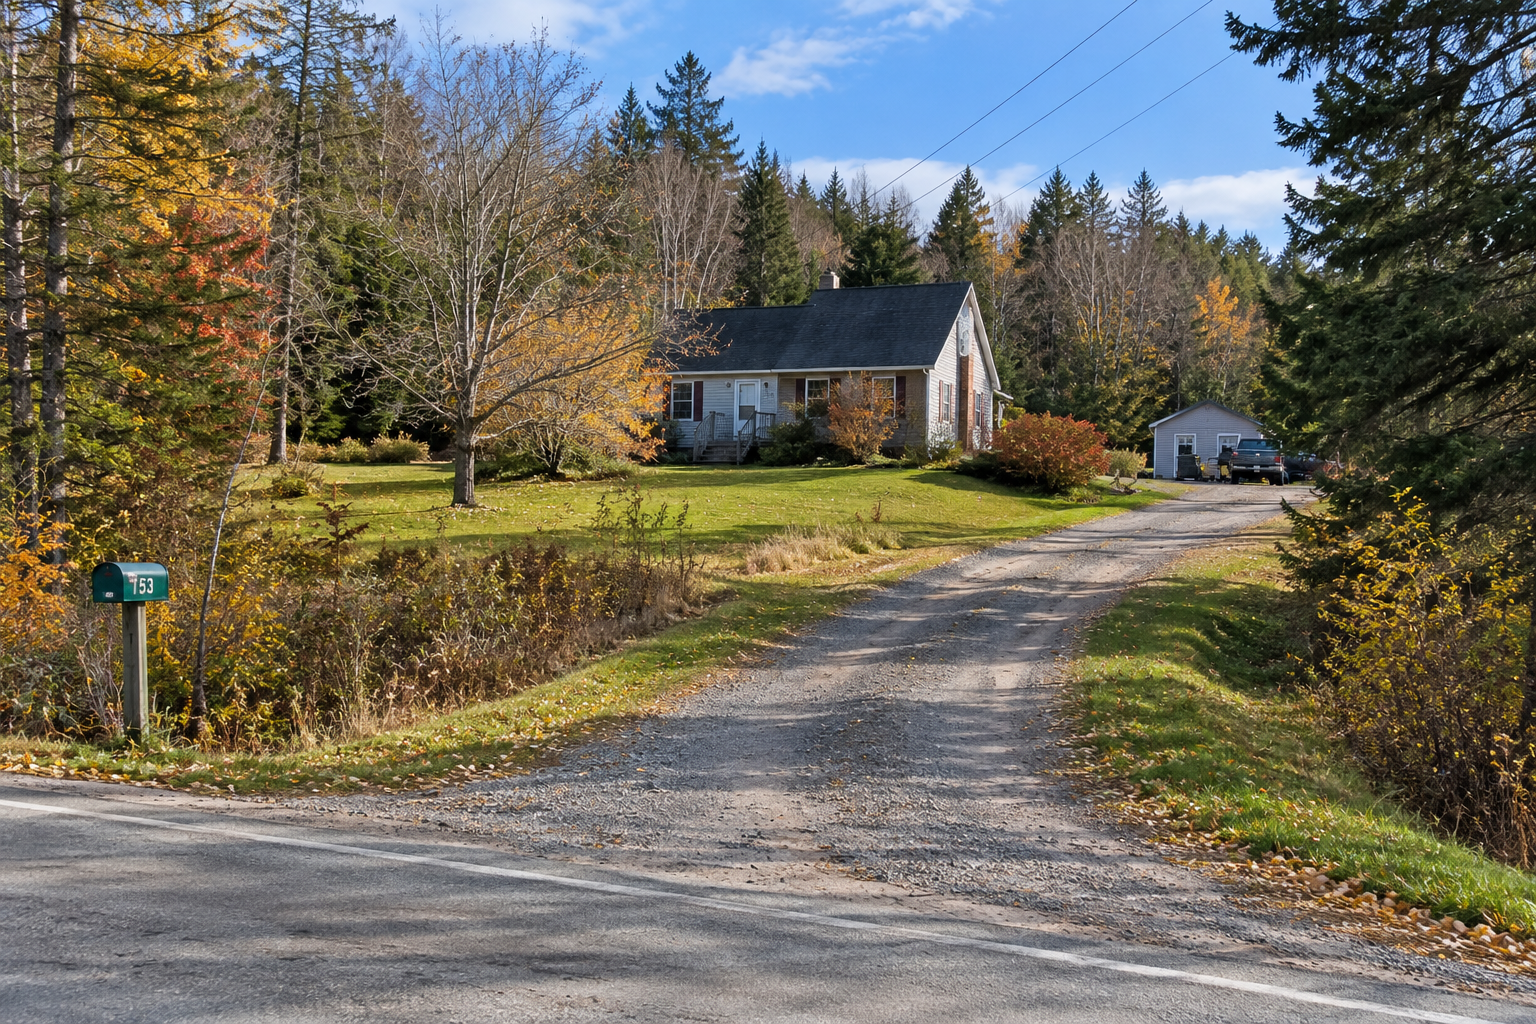
Rural road in Nova Scotia illustrating access and road maintenance considerations

Think About the Property Types Available in Each Area

Choosing a location and choosing a property type often happen together.

If you want a walkable home close to restaurants and shops, your search may naturally concentrate in established towns.

If you're looking for five or ten acres, a large workshop or room for animals, you'll probably need to look farther outside those centres.

Waterfront creates another geographic constraint entirely.

And if you're looking for a historic home, certain communities may offer far more choices than others.

Rather than choosing a location first and then trying to force your ideal property into it, consider the two decisions together:

Where can I find the kind of home I want while still having the lifestyle I want?

That question often produces a much more useful search area.

Different residential settings available to home buyers in Nova Scotia

Visit More Than Once If You Can

If you're seriously considering an unfamiliar community, try to experience it outside a scheduled home showing.

Walk around.

Get a coffee.

Visit the grocery store.

Drive through the neighbourhood in the evening.

See how long it takes to reach the places you'd actually use.

If you're relocating from outside Nova Scotia, this can be particularly valuable.

A community can look perfect in photographs and still not feel right once you're there.

Conversely, a place you barely considered on a map may immediately feel like somewhere you could live.


Don't Assume You Need to Know Exactly Where You Want to Live

This is something I encounter frequently with buyers moving to Nova Scotia.
You might know you like the Annapolis Valley without knowing whether Wolfville, Berwick, Kingston, Middleton or somewhere between them makes the most sense.

Or you may know you want the South Shore without knowing whether you should concentrate around Chester, Mahone Bay, Lunenburg, Bridgewater or farther along the coast.

That's completely reasonable.

You don't need to narrow your search to one town before you start looking.

Sometimes the first few showings aren't just about evaluating houses. They're also about learning what different areas feel like and discovering which trade-offs matter to you.


Use Area Guides for the Next Level of Research

Once you've narrowed your search to a few communities, that's the point where detailed local research becomes much more useful.

Instead of trying to turn this article into a description of every Nova Scotia town, my Area Guides explore individual communities in more detail—including the character of the area, housing, services and some of the practical considerations involved in living there.

That keeps the two questions separate:

This guide helps you decide what kind of location works for you.

The Area Guides help you investigate particular places.

Everyday community life in Nova Scotia for buyers considering where to live

The Best Location Is the One That Works for Your Life

There's no single Nova Scotia community that's right for every buyer.

Someone who wants restaurants within walking distance may make a very different choice from someone who wants a workshop, ten acres and enough room that they can't see their neighbours.

The goal isn't to find the community everyone else thinks is best.

It's to understand the trade-offs well enough to choose a location that fits the way you actually intend to live.

When we begin a home search, that's one of the conversations I like to have early.

Not simply:

“Where do you want to buy?”

But:

“What do you want your life there to look like?”

The answer can lead us to places you may not have considered.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

How Much Does It Really Cost to Buy a Home in Nova Scotia?

When you're planning to buy a home, the purchase price tends to get most of the attention.

But the price of the property isn't the only number you need to plan for.

In addition to your down payment, there can be costs for inspections, legal work, deed transfer tax, property adjustments, moving and other expenses before you ever receive the keys.

Some costs depend on the property. Others depend on where you're buying or how you're financing the purchase.

Understanding them before you start looking can help you answer a much more useful question than simply How much house can I afford?

How much money will I actually need to complete the purchase and comfortably move into the home?


Start With the Down Payment

Your down payment is the portion of the purchase price that you provide rather than finance through your mortgage.

How much you'll need depends on the purchase price, your mortgage and your individual circumstances.

For many buyers, the down payment will be the largest amount of cash required to purchase the property—but it shouldn't necessarily consume all of the money you've saved.

There are other expenses you'll need to pay along the way, and some of them can't simply be added to your mortgage.

If you're working toward a particular purchase price, your mortgage professional can help you understand the down payment requirements that apply to your financing.


Mortgage Loan Insurance May Affect the Cost of Your Mortgage

If your down payment is less than 20%, mortgage loan insurance will generally be required.

Mortgage loan insurance protects the lender, rather than the buyer, if the borrower defaults on the mortgage. The premium is based on the mortgage amount and the size of the down payment. The lender will typically pass that cost on to the borrower, and the premium can generally be paid upfront or added to the mortgage. Canada Mortgage and Housing Corporation

That means it may not always be another cheque you need to write on closing day, but it still affects the overall cost of financing the home.

Your mortgage professional can explain whether mortgage loan insurance applies to your purchase and how it affects your mortgage.


What About the Deposit With Your Offer?

The deposit and down payment aren't the same thing.

A deposit is submitted in connection with your Agreement of Purchase and Sale and demonstrates your commitment to the transaction.

If the purchase proceeds to closing, the deposit is credited toward the money required from you to complete the purchase—it isn't an additional amount on top of the purchase price.

But you still need to have the deposit funds available at the appropriate point in the transaction.

This is worth planning for before you make an offer. Having enough money saved for a down payment doesn't necessarily mean all of those funds are immediately accessible when a deposit is required.


Home inspection as part of the cost of buying a home in Nova Scotia

Budget for Inspections and Property Investigations

A home inspection is one of the more obvious costs buyers may encounter after an offer is accepted, but it isn't necessarily the only investigation worth considering.

Depending on the property, you might also need or choose to investigate things such as:

  • Well water quality or quantity

  • Septic system condition

  • Radon

  • Wood-burning appliances

  • Electrical systems

  • Oil tanks

  • Sewer lines

  • Structural concerns

  • Property boundaries

  • Environmental concerns

You won't need every test for every house.

The appropriate investigations depend on the property, its systems and anything identified during your initial review or home inspection.

These expenses are generally incurred before closing, so they should be part of the cash you've set aside for the purchase rather than something you expect to deal with after moving in.


You'll Need a Lawyer

A lawyer plays an important role in completing a real estate purchase in Nova Scotia.
Your lawyer's work may include reviewing title, preparing and registering documents, handling mortgage documentation, accounting for the money involved in the transaction and completing the legal transfer of the property.

Legal fees can vary depending on the lawyer, the transaction and the work required.

There can also be disbursements and registration-related expenses in addition to the lawyer's professional fee. For example, Nova Scotia's Land Registry currently charges fees for registering or recording documents. Government of Nova Scotia

Rather than relying on a generic online estimate, ask the lawyer you intend to use for an estimate of the legal fees and expected disbursements for your particular purchase.


Residential homes in Nova Scotia where municipal deed transfer tax may apply

Municipal Deed Transfer Tax Can Be a Significant Closing Cost

Nova Scotia municipalities can charge a Municipal Deed Transfer Tax when property changes ownership.

The important thing for buyers to understand is that there isn't one single province-wide municipal rate.

The rate is set by the municipality where the property is located and is calculated based on the sale price. Government of Nova Scotia

For example, the Province's April 2026 rate schedule lists a 1.5% Municipal Deed Transfer Tax for the Municipality of the County of Annapolis, the Town of Annapolis Royal and the Town of Middleton. Rates elsewhere in Nova Scotia can differ. Government of Nova Scotia

On a $350,000 purchase, a 1.5% municipal deed transfer tax would be:

$5,250

That's a substantial amount to discover late in the process.

When you're considering a property, confirm the applicable rate for that municipality rather than assuming it will be the same as somewhere else in Nova Scotia.

Moving to Nova Scotia? There May Be Another Deed Transfer Tax to Consider

This is especially important for buyers coming from outside Nova Scotia.
Nova Scotia also has a Non-resident Provincial Deed Transfer Tax that can apply when non-residents acquire qualifying residential property.

As of September 2026, the rate is 10%, generally calculated using the purchase price or assessed value, whichever is higher, and according to the ownership interest being transferred to non-residents. Government of Nova Scotia

There are exemptions, including provisions for people who intend to move to Nova Scotia and establish residency. The Province announced changes in August 2026 intended to give qualifying buyers more flexibility around proving that residency. Nova Scotia News

Because a 10% tax could represent a very large amount of money, don't make assumptions about whether you qualify for an exemption.

If you're moving to Nova Scotia, discuss your circumstances with your lawyer before closing so you understand how the rules apply to you.


What Are Closing Adjustments?

Some expenses associated with the property may have already been paid by the seller for a period extending beyond the closing date.

Others may need to be divided between buyer and seller.

These amounts can be accounted for through adjustments on closing.

Property taxes are a common example.

If the seller has already paid property taxes covering a period during which you'll own the home, an adjustment may be made so that each party ultimately pays their appropriate share.

Other adjustments can depend on the property and the terms of the transaction.

These aren't necessarily huge expenses individually, but they affect the final amount of money your lawyer will require from you to complete the purchase.


Home features that may affect insurance when buying a property in Nova Scotia

Don't Forget Home Insurance

You'll generally need to arrange home insurance before closing when you're financing the purchase.

The cost can vary considerably depending on the home and the coverage.

Factors such as the age and condition of the property, heating system, electrical system, roof, oil tank, wood-burning appliances and other characteristics can affect whether an insurer will cover a property and what that coverage costs.

This is one reason I recommend buyers investigate insurance before their conditions are satisfied, particularly when purchasing an older or unusual home.

The important question isn't simply:

“How much will insurance cost?”

It's also:

“Can I obtain acceptable insurance on this particular property?”

We'll explore that issue much more deeply in the Buyer Resource Centre's dedicated guide to home insurance.

Moving into a new home after completing a Nova Scotia home purchase

Moving Day Has Costs Too

Closing the transaction isn't the end of the expenses.

Depending on your move, you may need to budget for:

  • Professional movers or a rental truck

  • Travel

  • Temporary accommodation

  • Storage

  • Utility or service setup

  • Changing locks

  • Appliances or furnishings

  • Immediate maintenance

  • Snow removal or lawn equipment

  • Fuel or heating costs

  • Supplies for your first few days in the home

Someone relocating across Canada will obviously have a very different moving budget from someone buying a home ten minutes away.

The important thing is simply to include the move itself in your planning.


Leave Room for the House to Surprise You

Even a carefully inspected home can have expenses after closing.

You may discover that you need a tool you never owned before, want to replace a lock, need to service a heating system or suddenly realize how much it costs to equip a larger property.

An inspection can help you understand the condition of the home, but it doesn't make future maintenance disappear.

This is why using every available dollar for the down payment and closing costs can leave a new homeowner in an uncomfortable position.

If possible, plan to have some money remaining after the transaction is complete.

Owning the home is much easier when the first unexpected repair doesn't immediately become a financial emergency.


Purchase Costs and Ownership Costs Are Different

It's useful to separate your budget into two categories.

Costs to buy the home can include your down payment, inspections, legal expenses, deed transfer tax, closing adjustments and moving expenses.

Costs to own the home can include your mortgage payment, property taxes, insurance, heating, electricity, water and wastewater, maintenance and other recurring expenses.

CMHC recommends planning for both closing costs and the ongoing expenses of homeownership. Its current guidance notes that closing costs can amount to roughly 1.5% to 4% of the purchase price, although the actual amount depends on the transaction and location. Canada Mortgage and Housing Corporation

For a Nova Scotia buyer, that percentage should be treated as a planning guideline rather than a quote. Municipal deed transfer tax varies, property investigations differ, legal costs aren't identical and the non-resident provincial tax can dramatically change the calculation when it applies.


So, How Much Money Should You Have Available?

There isn't one percentage that works for every Nova Scotia home purchase.

A more useful approach is to build the budget from the actual pieces:

Down payment

  • Deposit timing

  • Inspection and testing costs

  • Legal fees and disbursements

  • Applicable deed transfer taxes

  • Closing adjustments

  • Moving costs

  • A reserve for the unexpected

Your mortgage professional can help you understand the financing and down-payment side.

Your lawyer can provide guidance on legal costs, taxes and closing requirements.

Your REALTOR® can help identify property-specific investigations and expenses that may need to be considered as you evaluate a home.

Together, those conversations can give you a much more realistic picture than simply estimating a percentage of the listing price.


Nova Scotia home representing the costs and responsibilities of homeownership

Prepare for the Purchase, Not Just the Mortgage

Saving enough for a down payment is an important milestone.

But being financially prepared to buy a home means looking beyond the down payment.

When you account for the costs that happen before, during and immediately after closing, you can begin your home search with a much clearer idea of what you can comfortably purchase.

And when the right property comes along, you're less likely to discover that the expenses surrounding the transaction have stretched your budget further than you expected.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

Getting Pre-Approved for a Mortgage: What Buyers Should Know

For many home buyers, getting pre-approved for a mortgage is one of the first practical steps in the buying process.

It can help you understand the price range you may be able to consider, give you an idea of what your mortgage payments could look like and make your home search more focused.

But there's an important distinction that buyers sometimes miss:

A mortgage pre-approval is not a guarantee that your mortgage will ultimately be approved.

Understanding what a pre-approval does—and what still has to happen after you find a home—can help you approach your search with more realistic expectations.


What Is a Mortgage Pre-Approval?

A mortgage pre-approval is an assessment completed by a lender or mortgage broker before you've chosen the property you want to buy.

As part of the process, you'll generally provide information about your income, employment, debts, assets and the money you expect to use toward your purchase. A lender will also likely check your credit. Canada

Based on that information, the process may give you an indication of the maximum mortgage amount you could qualify for and an estimate of your payments. Depending on the lender, it may also include an interest-rate hold for a specified period. Canada

That's useful information to have before you begin seriously looking at properties.

But the amount you're pre-approved for should be treated as a financing limit, not necessarily your home-buying budget.


How Much Should You Actually Spend?

Being told you may qualify for a particular mortgage doesn't mean you have to spend that much.

A lender's calculation is primarily concerned with whether you meet its lending requirements. Your personal budget has to account for everything else competing for your income.

That can include:

  • Property taxes

  • Home insurance

  • Heating and electricity

  • Water and wastewater costs

  • Maintenance and repairs

  • Transportation and commuting

  • Other debts and monthly obligations

  • Savings and retirement goals

  • The lifestyle you want to maintain

You may decide that buying below your maximum qualification gives you more financial flexibility.

This is particularly worth considering when comparing Nova Scotia properties because two homes at similar prices can have considerably different operating and maintenance costs.


What Will a Mortgage Professional Need From You?

The exact requirements vary by lender and by your financial circumstances, but you should expect to provide documentation supporting the information in your application.

That may include:

  • Identification

  • Proof of employment and income

  • Information about your bank accounts and other assets

  • Details about loans, credit cards and other debts

  • Information about your down payment

  • Evidence showing where your down payment is coming from

  • Documentation showing you have funds available for closing costs

Self-employed buyers or buyers with income that doesn't fit a conventional employment arrangement may be asked for additional documentation.

Providing complete information at the beginning can help avoid unnecessary delays. CMHC notes that missing or incomplete information is a common reason mortgage applications take longer to process. Canada Mortgage and Housing Corporation


Your Down Payment Is Part of the Conversation

Your mortgage professional will want to know not only how much money you have available for your down payment, but also where it came from.

Depending on your situation, those funds might come from savings, investments, proceeds from selling another property or an eligible gift.

Documentation requirements can vary depending on the source of the money, so it's worth discussing this early rather than assuming you can simply move the funds when they're needed.

You'll also want to remember that your down payment isn't the only cash you'll require.

Legal fees, inspections, applicable deed transfer tax, adjustments at closing, moving expenses and other purchasing costs may all require funds outside the amount you're putting toward the property.


Pre-Approved Doesn't Mean Final Approval

This is probably the most important thing to understand about mortgage pre-approval.

Your lender hasn't approved the house yet because you haven't chosen it.

Once you have an accepted offer, the lender can assess the actual transaction and property.

The final mortgage amount can depend on factors including the purchase price, the property and its value. A lender may require an appraisal or other information before providing final approval. CMHC specifically notes that even a buyer with a pre-approved mortgage still needs final mortgage approval during the conditional-offer period. Canada Mortgage and Housing Corporation

This is one reason a financing condition can be important when preparing an offer.

A strong pre-approval puts an important piece of the financing puzzle in place—but it doesn't eliminate the remaining pieces.


Why Can the Property Affect Your Financing?

When you're buying a home, the lender isn't evaluating only you.

It's also lending money against the property.

Certain characteristics may cause a lender to ask additional questions or require more information. The exact requirements depend on the lender and the property.

This can become particularly relevant when considering properties that are unusual, require substantial work or don't fit neatly into conventional residential lending.

CMHC notes that lenders verify that a property meets their standards before approving a mortgage and that those standards can vary between lenders. Canada

If you're considering a property that's significantly different from a conventional home, involving your mortgage professional early can help identify potential financing questions before they become time-sensitive.


What Is a Mortgage Appraisal?

An appraisal may be one of the steps a lender uses to assess the property.

The purpose isn't the same as a home inspection.

A home inspection is intended to help you better understand the physical condition of the property. An appraisal is concerned primarily with establishing the property's value for lending purposes.

The lender wants to know whether the property's value reasonably supports the mortgage being requested.

CMHC explains that property value is an important part of determining the mortgage amount and that a professional appraisal may be required when a more detailed valuation is needed. Canada Mortgage and Housing Corporation

If the lender's valuation doesn't support the amount required for the purchase, the buyer may need to discuss the available options with their mortgage professional and REALTOR®.


Try Not to Change Your Financial Situation Before Closing

Getting pre-approved doesn't freeze your financial circumstances.

Your lender may review or verify information again before the mortgage is finalized.

Because of that, it's worth speaking with your mortgage professional before making significant financial changes while you're in the process of buying a home.

For example, taking on new debt, financing a vehicle or making another substantial credit purchase could affect the financial picture on which your mortgage qualification was based.

The same principle applies if something significant changes with your employment or income.

If your circumstances change between pre-approval and closing, tell your mortgage professional rather than assuming it won't matter.


What Should You Ask During the Pre-Approval Process?

A pre-approval meeting isn't just about receiving a maximum mortgage number.

It's also an opportunity to understand how your financing will work.

Useful questions might include:

  • How much could I potentially qualify to borrow?

  • What might the monthly payment look like?

  • How long is the pre-approval valid?

  • Is an interest rate being held, and for how long?

  • What documentation will you need from me?

  • Are there property types that could present financing challenges?

  • How quickly can financing be reviewed once I have an accepted offer?

  • What could cause final approval to differ from the pre-approval?

  • Who should I contact if my income, debts or down payment change?

FCAC specifically recommends asking how long a pre-approved rate is guaranteed, whether a lower rate would apply if rates fall during that period and whether the pre-approval can be extended. Canada

Don't hesitate to ask your mortgage professional to explain anything you don't understand.


Your REALTOR® and Mortgage Professional Have Different Roles

Your mortgage professional and REALTOR® are both important during a purchase, but they provide different expertise.

Your mortgage professional can advise you about mortgage qualification, financing products, interest rates and lender requirements.

Your REALTOR® can help you understand the property, the market and the real estate transaction—and can make sure your mortgage professional receives the property and offer information they need when financing is being reviewed.

Neither replaces the other.

The process generally works best when the professionals involved can communicate efficiently once you've found a property you want to purchase.


Get the Financing Conversation Started Before You Find the House

It's much easier to work through questions about income, credit, down payment or documentation before you're working against the deadlines of an accepted offer.

A pre-approval can give you a clearer starting point and help focus your search on properties that make sense for your circumstances.

Just remember what it actually represents.

It tells you something about your potential financing before you've selected a property. Final approval comes later, once both you and the property have satisfied the lender's requirements.

That distinction is worth understanding before you begin your home search.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read

How to Prepare to Buy a Home in Nova Scotia

Buying a home often starts long before you book your first showing.

A little preparation can make it easier to understand what you can comfortably afford, narrow down where and what you want to buy, and recognize when the right property comes along.

You don't need to have every detail figured out before you start talking to a REALTOR® or mortgage professional. But getting some of the important pieces in place early can make the home-buying process much easier to navigate.


Start With Your Financial Picture

Before focusing on listings and asking prices, take some time to look at your overall financial situation.

The question isn't simply how much a lender may be willing to lend you. It's also how much you're comfortable spending each month while still leaving room for everything else in your life.

Consider your existing monthly expenses, debts, savings and the amount you expect to have available for a down payment. Then think about the costs that will come with owning the type of property you're considering.

Two homes with the same purchase price can have very different ongoing costs. Property taxes, insurance, heating, electricity, water and wastewater services, maintenance and commuting can all affect what a home actually costs to own.

A realistic budget should consider both what it costs to buy the property and what it will cost to live there.


Talk to a Mortgage Professional Before You Start Looking

Getting pre-approved for a mortgage can give you a better idea of the price range you may be able to consider.

A mortgage professional can review your income, debts, credit and down payment and explain the financing options that may be available to you.

This is also a good opportunity to ask questions about the documentation you'll need and whether there are factors that could affect your eventual mortgage approval.

Keep in mind that a pre-approval isn't the same as final mortgage approval.

Once you have an accepted offer, your lender may still need to approve the property itself, review the purchase price and possibly obtain an appraisal before providing final financing.

Understanding that distinction before you begin your search can help prevent surprises later.

Home buyers discussing mortgage pre-approval with a mortgage professional

Know How Much Cash You May Need

Your down payment isn't the only money you may need when buying a home.

Depending on your purchase, you may also need funds for expenses such as:

  • The deposit submitted with your offer

  • Home inspection and other property investigations

  • Legal fees

  • Deed transfer tax

  • Adjustments made at closing

  • Moving expenses

  • Immediate repairs or maintenance

  • Utility or service setup

The exact costs will depend on the property and your circumstances, but it's worth leaving some room in your budget rather than using every available dollar for the purchase itself.

Having money available after closing can also make the first few months of homeownership considerably less stressful when an unexpected repair or expense appears.


Residential community in Nova Scotia showing homes and surrounding landscape

Think About Where You Want to Live

Before setting up a search based solely on price and bedroom count, think about how location will affect your everyday life.

Nova Scotia can change considerably within a relatively short drive. A home in town may have municipal water and sewer, nearby services and a short commute, while another property twenty minutes away may have a well, septic system, private road or significantly more land.

Neither is necessarily better. They're simply different ways of living.

Consider things such as:

  • Commute and travel time

  • Access to shopping and everyday services

  • Healthcare

  • Schools, if they're important to your household

  • Internet and cellular service

  • Road maintenance and winter driving

  • Municipal versus private water and wastewater systems

  • Property size and maintenance

  • Proximity to family, recreation and community activities

If you're relocating to Nova Scotia, spending some time understanding the communities you're considering can be just as important as researching the houses themselves.


Separate Your Needs From Your Wants

Most buyers begin with an idea of their ideal home. The challenge is deciding which parts of that picture are essential and which ones are flexible.

One useful approach is to divide your priorities into three groups.

Needs

These are the things the property realistically must have for it to work for you. That could include a certain number of bedrooms, accessibility requirements, a manageable commute or space for a particular use.

Wants

These are features you'd really like to have but could compromise on for the right property. A garage, finished basement, particular kitchen layout or larger lot might fall into this category.

Deal Breakers

These are characteristics that would cause you to rule out a property regardless of its other advantages.

Making these distinctions before you start looking can help when you eventually have to compare homes that each offer something different.

Your priorities may also change once you've seen a few properties—and that's perfectly normal.


Nova Scotia home with land illustrating different property types buyers may consider

Consider the Type of Property You Want to Own

Nova Scotia offers much more than conventional subdivision homes.

Depending on where you're looking, you may encounter older homes, waterfront properties, acreages, hobby farms, cottages, mini or modular homes, vacant land and properties with private roads or unusual construction.

Different property types can bring different responsibilities and questions.

For example, owning several acres may sound appealing until you consider driveway maintenance, snow removal and the time required to maintain the land. Waterfront may be a priority, but shoreline conditions, insurance, access and exposure can become part of the decision.

The goal isn't to avoid properties that are different. It's to understand what comes with the type of property you're considering.


If You Already Own a Home, Think About How the Two Transactions Fit Together

Buying becomes more complicated when the money or timing for your next home depends on selling your current one.

Before beginning your search, it's worth understanding approximately what your existing property may sell for, how much equity you may have available and how the timing of a sale could affect your purchase.

Depending on your circumstances, you may need to consider questions such as:

  • Do you need to sell before you can buy?

  • Can you qualify to own both properties temporarily?

  • Would bridge financing be an option?

  • What happens if the closing dates don't line up?

  • Would your offer on another property need to depend on selling your current home?

Your REALTOR® and mortgage professional can help you understand how these pieces may fit together before you're trying to solve them in the middle of an offer.

Homeowners discussing buying and selling a home with their REALTOR®

Understand the Basic Buying Process

You don't need to become an expert in real estate contracts before you start looking for a home, but knowing the broad stages of the process can make everything feel much less unfamiliar.

A typical purchase may involve:

  1. Preparing your finances and getting pre-approved

  2. Identifying your priorities and beginning the property search

  3. Viewing and evaluating potential homes

  4. Preparing and negotiating an offer

  5. Completing financing, inspections and other agreed conditions

  6. Working with your lawyer, lender and other professionals toward closing

  7. Completing a final walkthrough

  8. Closing the transaction and taking possession

The details can vary from one purchase to another, particularly when you're buying a property with unusual features or circumstances.

That's why understanding the process is useful—but having the right professionals involved is equally important.

Home buyers viewing a property with their REALTOR® in Nova Scotia

When Should You Contact a REALTOR®?

You don't have to wait until you're ready to book showings.

Speaking with a REALTOR® earlier in the process can help you understand local property types, communities, current listing conditions and some of the questions that may come up during your search.

It can also be useful if you're still trying to determine whether your expectations around location, property type and budget line up with what's available.

A REALTOR® isn't a substitute for your lender, lawyer, inspector, insurance provider or other specialists. Each professional has a different role.

Part of the REALTOR®'s job is helping you navigate the real estate transaction and recognize when a question should be answered by one of those other professionals.

Nova Scotia home representing the end goal of a home buyer's search

You Don't Need to Have Everything Figured Out

Preparing to buy a home doesn't mean predicting every question you'll encounter.

It means getting enough of the important pieces in place that you can start your search with a clearer understanding of your finances, priorities and options.

Your ideas may change as you explore communities and see different properties. You may discover that something you originally considered essential isn't as important as you thought—or that a feature you hadn't considered becomes a priority.

That's part of the process.

The objective isn't to create the perfect checklist before you begin. It's to put yourself in a position to make informed decisions as the right property comes along.


Part of the Buying a Home in Nova Scotia Buyer Resource Centre: Practical guides to help you prepare, evaluate a property and navigate the home-buying process.

Read
×

Do you have questions?

Call or text today.
I am always here to help!

902-300-8674